S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

The coffee market in the grip of weather and empty warehouses: The paradox of record Brazil harvests

Although coffee has lost value since the beginning of this year, looking at the last months or days, we observe a very strong growth dynamic. In recent days, the demand force has been gaining strength and coffee prices are marking the strongest increases in a long time. Arabica futures rose by almost 10% in just two sessions. This situation seems logical on the surface, given the highly optimistic harvest forecasts from Brazil. To understand why prices are rising despite the promise of record harvests, one must look at the market through the prism of what is happening “here and now,” not what will happen in a few months. Price changes in the commodities market in the last month
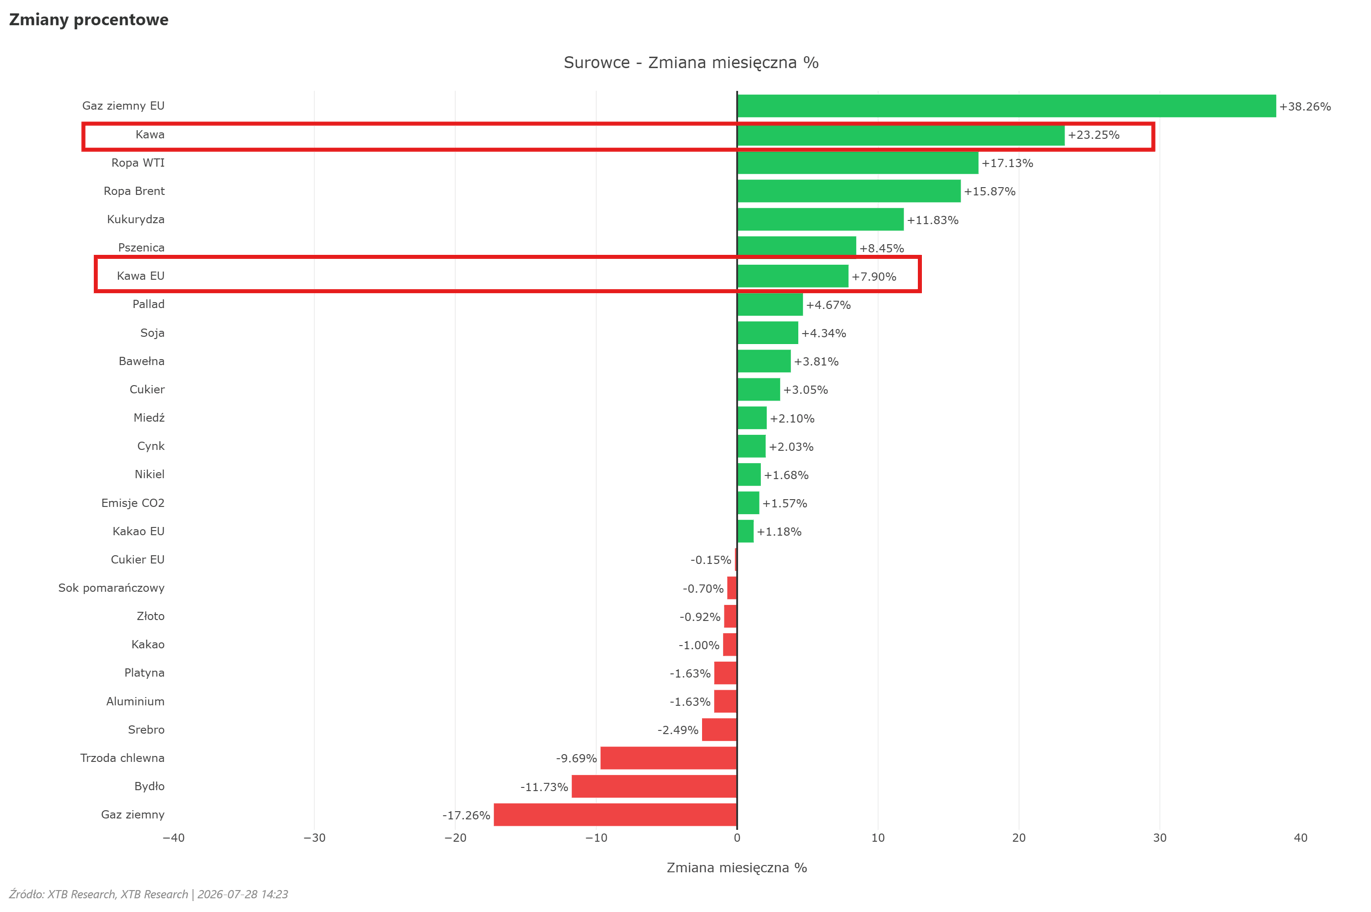
Coffee is growing very strongly from the perspective of the last 30 days. Source: XTB
What about record harvests in Brazil?
The US Department of Agriculture’s (USDA) expectations for a massive harvest in Brazil (exceeding 70 million bags) are still valid, but long-term market fundamentals are one thing, and the physical availability of the commodity at a given time is another. The main culprit for the current increases is the weather, which is brutally delaying harvests and may indicate that earlier forecasts were overly optimistic. Although the USDA pointed to forecasts at the level of 70 million bags of coffee in Brazil, the assessments of other institutions, including the Brazilian CONAB, remain significantly lower. In Minas Gerais, the largest Arabica growing region in Brazil, just over 32 mm of rain fell in just one week, which is as much as 2700% of the historical average for this period. These heavy rains mean that farmers have huge problems not only in harvesting but also in drying and transporting the beans. Although the potential supply on paper is huge, this coffee has not yet reached the market. What’s more, market commentators point out that although the quantity of coffee will be sufficient, growers will face problems regarding the quality of the beans. Although Brazil is the world’s largest coffee producer and its coffee is available as part of deliveries on the ICE exchange, the lack of quality harvests may lead to drained stocks of the commodity on the ICE not increasing, despite record harvests.
Warehouse collapse: Stocks almost lowest since the 90s.
Delays in deliveries from Brazil are hitting the market at the worst possible moment, when exchange warehouses are empty. Stocks of certified Arabica monitored by the ICE exchange are falling drastically, recently recording the largest single-day drop (by 5.9%) since the beginning of 2025. In the course of 25 consecutive trading sessions, these stocks have shrunk by a total of as much as 26%. From historical data and inventory curves, it appears that the level of reserves is indeed approaching critical minimums not seen since the turn of the 90s and 2000s (currently falling below the limit of 300 thousand bags). In addition, the supply situation is complicated by tensions in the Red Sea. Extended transit times for ships, higher freight costs, and the need for logistics companies to maintain larger inventories mean that deliveries to consumer markets are seriously delayed. Arabica coffee price along with ICE inventories (inverted axis)
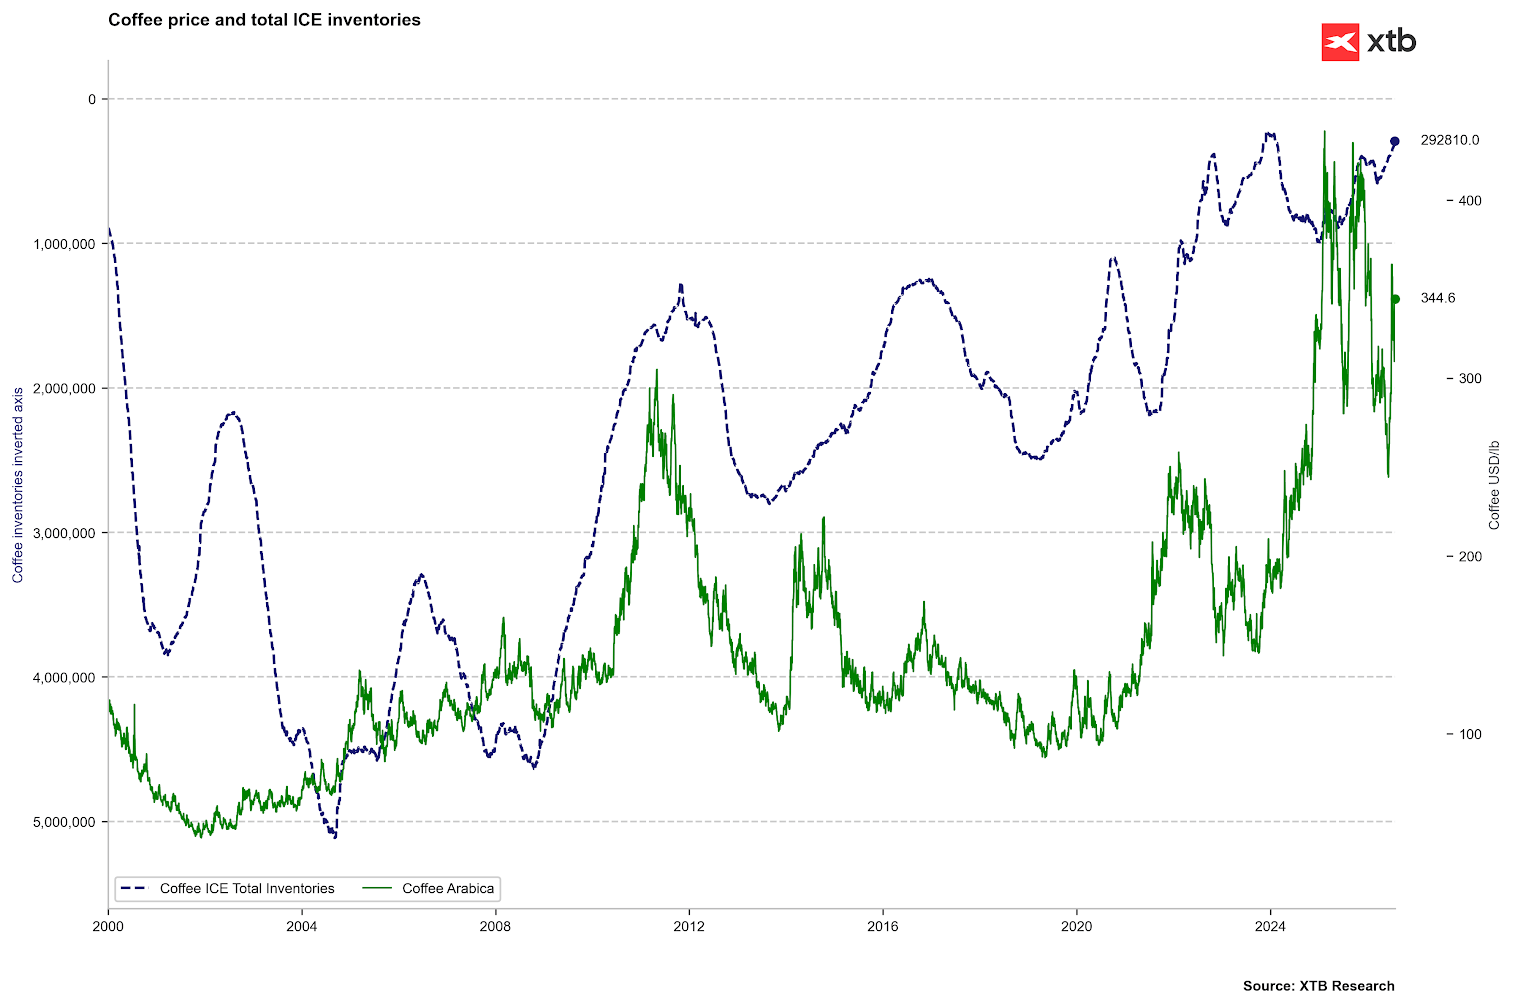
Stocks tracked by ICE have fallen to their lowest levels since the turn of 2023/2024, which in turn are the lowest since the 90s. All this is taking place despite the expected record harvests in Brazil. Source: Bloomberg Finance LP, XTB
Is this already a change in trend to a permanently upward one?
The current strong price increase is largely a short-term supply panic effect, although at the same time due to the unpredictable weather, one cannot rule out a situation in which the current increases end with reaching new historical highs. The extremely strong El Nino weather phenomenon usually affects excessive rainfall in South America and droughts in Southeast Asia, which can mean potential support for coffee crops in Brazil, but worsening logistics, while simultaneously hitting supply in Asia hard. However, the market believes that supply will not be a problem in the future. This is evidenced by the structure of the futures market itself. The difference (spread) in price between September and December contracts has widened to a record level of over 24 cents per pound. This means a powerful phenomenon of backwardation. Roasters and buyers are willing to pay a huge premium for the delivery of coffee immediately because they are afraid that it will run out in warehouses in a moment. Contracts for subsequent years are priced much lower. Forward curve for Arabica coffee currently (black line) and 6 months ago (orange line)
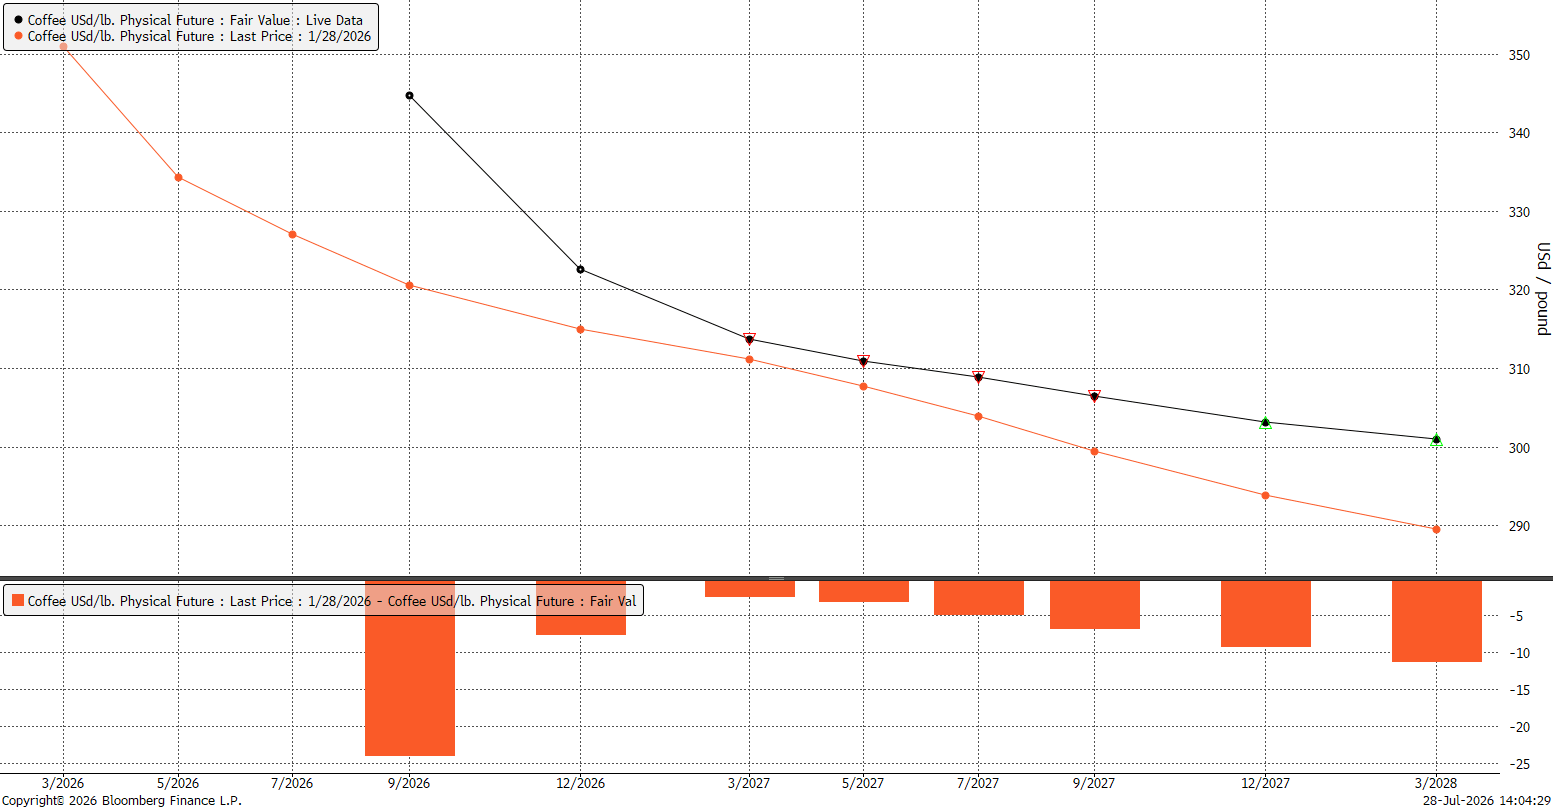
The forward curve for coffee continues to indicate that short-term supply is the problem, while higher coffee production is expected in the future. Source: Bloomberg Finance LP
Summary and conclusions
The coffee market is currently showing considerable concerns about short-term supply, similar to what happened in the cocoa market just a few weeks ago. However, if production is to continue to grow, and in the near future it will affect the recovery of stocks, it may turn out that prices will have difficulty rising to the highest levels in history. Theoretically, when all the coffee is harvested and starts reaching consumers around the world, we should observe this in the price already in the autumn period. If, however, prices do not start to fall from currently high levels then, it may mean that the physical situation is indeed tight, and we can simply throw paper expectations regarding high production into the bin. Coffee technical chart on the D1 interval
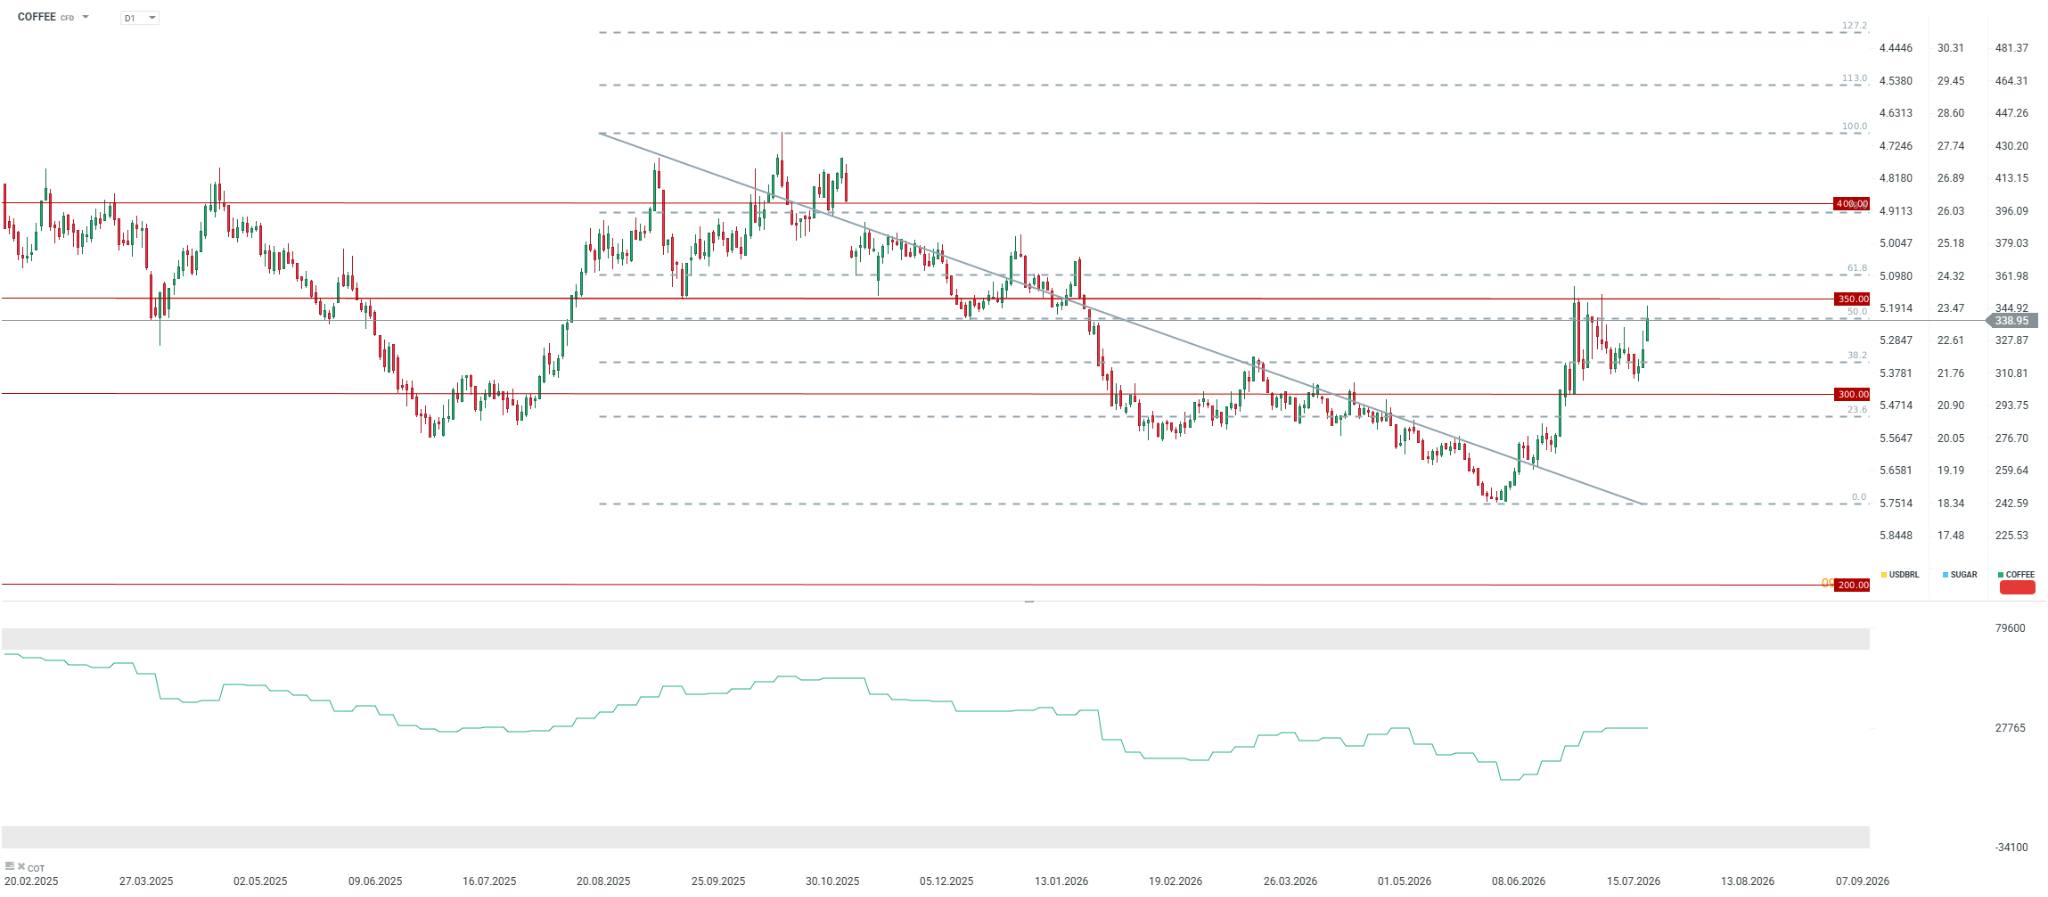
Coffee prices have been rising very strongly since the beginning of this week, and the price is already testing the vicinity of half of the last entire large downward wave. The 350-360 cents per pound of coffee zone will be crucial. If these levels can be permanently broken, it may mean an attempt to return to 400 cents, and even an attack on historical peaks. If, however, it turns out that coffee production in Brazil will indeed be record-breaking, the price may return to 300 cents per pound faster than would follow from the forward structure, which assumes such a level only in March 2028. Source: xStation5