S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

BOE Takes a Hawkish Tilt While Oil Spikes And The Risk Sell-off Continues

The dust has settled on the BOE decision, although there was no change in rates, for the first time in 4.5 years the BOE voted unanimously to keep interest rates on hold as the conflict in the Middle East causes the BOE’s doves to shift to a more hawkish stance.
BOE will react to inflation spike
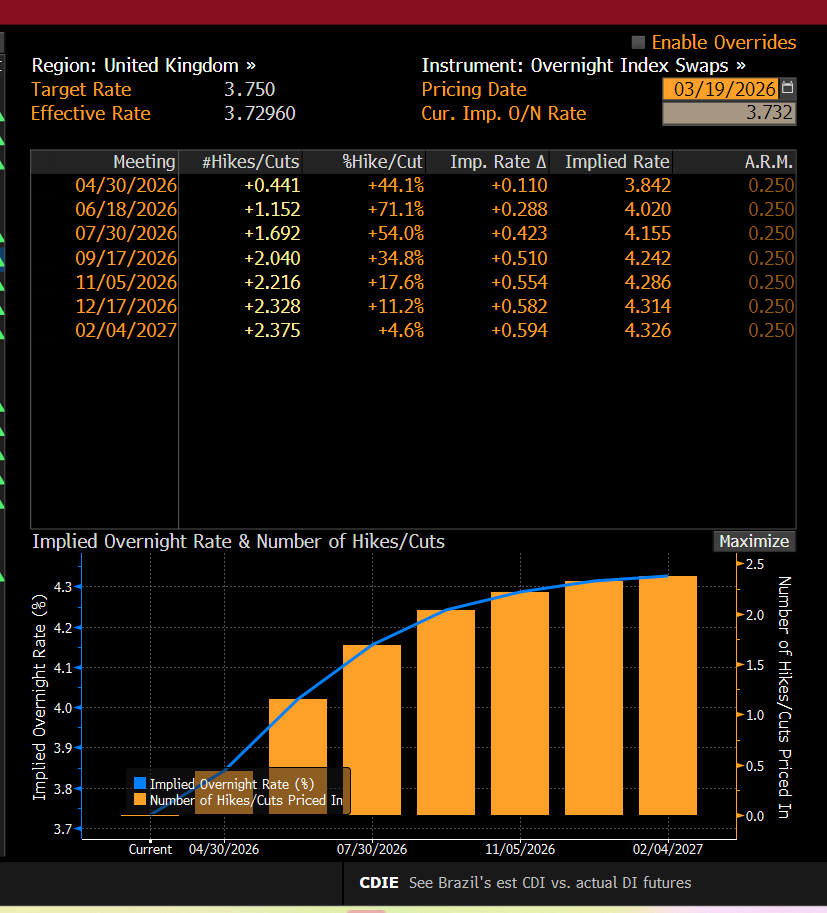
The BOE signaled that it would not look through this period of higher oil prices, they revised up their inflation expectations to 3.5% for this month, and the interest rate swaps market is now pricing in nearly 3 rate hikes from the BOE for this year. This is another massive recalibration in UK rate expectations, just this morning less than one hike was expected. UK interest rates are now expected to end the year just below 4.5%.
This is bad news for the 1.8 million mortgage holders who are due to refinance this year, especially since the economic backdrop remains weak. It’s also bad news for any borrowers, from consumer credit cards to corporate loans, as Gilts are leading a global bond sell off. The 2-year yield is higher by 35bps, at 4.46%, which is the highest level since January 2025. This is the biggest one day move in 2-year UK yields since this crisis started, and we would need to go back to August 2024 to get a larger daily percentage change in UK yields.
Central banks ignore risks to growth
Central banks including the Fed, who also prioritized the inflation risks at their meeting last night, along with the BOE and the RBA, have all repriced energy price risks, and they have repriced the risk to bonds, sending yields surging and causing unprecedented volatility in the interest rate futures market. At this point, they have not priced in the risks to growth. What happens to demand? The BOE does not seem to be prioritizing the risks to growth, which could be very damaging down the line.
Confidence slips away from UK assets
It is worth noting that 5-year 5-year swaps rates, which is used to price mortgages, is also at its highest level since early 2025, which is another nail in the coffin for the Labour government’s growth strategy, which hinged on lower interest rates. The government may need to step in to boost demand, now that the BOE is stepping back. However, this is a government that raises taxes and exacerbates our energy crisis, which is why confidence is rapidly exiting the UK economy.
Is the BOE making a policy mistake?
Has the BOE made a policy mistake? We will need to see. For now, the Bank is worried about the second-round inflation effects and the impact it could have on wages. An oil price spike was one of the scenarios included in the BOE’s new model that they use to set interest rates. However, the BOE seems to be forgetting that the Uk’s labour market is weak, employers have the power now, not employees, so the impact of inflation will be very different to 2022. Even so, they stand willing to tighten monetary policy if energy prices remain elevated. It is also worth noting that the market no longer sees the FOMC cutting rates this year.
The pound is the second-best performer in the G10 FX space today and GBP/USD is higher by 0.33%, GBP/USD is back above $1.33, EUR/GBP is also coming under pressure and is trading around £0.8630, having found support at £0.8600.
Elsewhere, the oil price has pulled back this afternoon after the US Treasury secretary touted the possibility of more reserve releases. Ironically, the US has also said that it could lift sanctions on Iranian oil that is already at sea to relieve pressure on the global oil price.
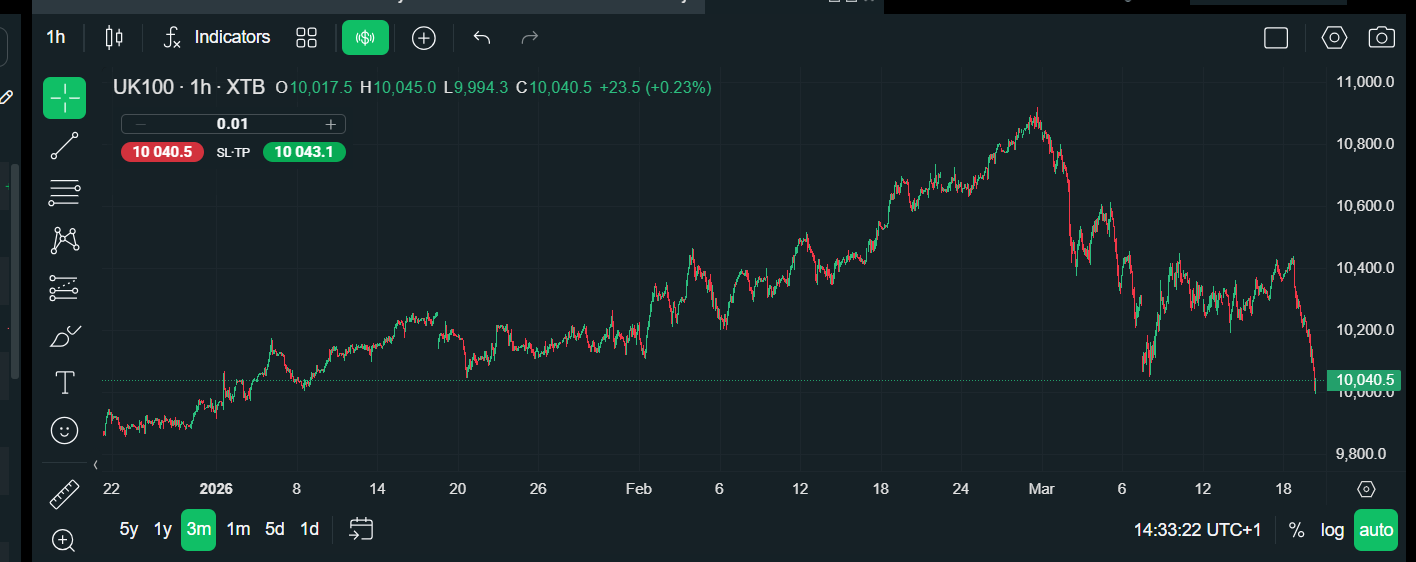
FTSE 100 at risk of dropping below 10,000
The metals market is getting slammed today. Aluminum has fallen by the most since 2018, and the gold and silver price is declining sharply. The gold price is lower by 5% and the silver price by 11%. This is weighing heavily on the miners, who are dragging the FTSE 100 lower today, it is down by 2.7%, as gold miners including Endeavour and Fresnillo are both down 8% so far today. Even the energy sector is lower today, after Shell’s gas assets in Ras Laffan in Qatar were also hit by the Iranian attack. The FTSE 100 is at risk of dropping below the 10,000 level on the back of this crisis.
Economically damaging phase of the war leads to pressure on Trump to find a solution
The energy price shock is a result of the conflict moving from a shipping crisis to a supply crisis, with both sides targeting energy assets. This is a much more damaging stage of the war for the global economy. From a political perspective, the US President is finding himself more isolated, with growing pressure from Europe to find a solution to this conflict. We will need to see if the White House will heed these complaints, and if there is any sign to deescalate the situation as we move towards the end of the week. For now, it is a bad day for UK asset prices like stocks and bonds.
Chart 1: UK rate expectation, 3 hikes now expected for 2026
Source: XTB and Bloomberg
Chart 2: UK 100 at its lowest level since early January on the back of the risky asset sell off
Source: XTB
The material on this page does not constitute financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other specific needs. All information provided, including opinions, market research, mathematical results and technical analyzes published on the Website or transmitted To you by other means, it is provided for information purposes only and should in no way be construed as an offer or solicitation for a transaction in any financial instrument, nor should the information provided be construed as advice of a legal or financial nature on which any investment decisions you make should be based exclusively To your level of understanding, investment objectives, financial situation, or other specific needs, any decision to act on the information published on the Website or sent to you by other means is entirely at your own risk if you In doubt or unsure about your understanding of a particular product, instrument, service or transaction, you should seek professional or legal advice before trading. Investing in CFDs carries a high level of risk, as they are leveraged products and have small movements Often the market can result in much larger movements in the value of your investment, and this can work against you or in your favor. Please ensure you fully understand the risks involved, taking into account investments objectives and level of experience, before trading and, if necessary, seek independent advice.