S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Partly outside the spotlight of retail investors and public opinion, one can observe changes in the bond market which, although not very impressive in nominal terms, have enormous implications. The buzz of speculation, theories, and fears was partly fueled by Kevin Warsh’s speech at Jackson Hole. Many investors and analysts expected the new Fed chair to, in a sense, support efforts to fight for low interest rates and an election victory being pursued by Donald Trump and Scott Bessent. But it turned out differently. Kevin Warsh struck a very hawkish tone, though in his usual style, avoiding specifics.
Politics Is Theater
Many people like to think that monetary policy is a unique bastion of technical expertise, verifiable data, and de facto technocracy that maintains decorum even when surrounded by the sensation and populism of the mainstream. But that conclusion is very superficial. Monetary policy is just as much theater, rhetoric, and spectacle as, for example, presidential debates or campaign rallies. The differences in messaging stem from the nature of the target audience, but the pattern of shifts remains the same. The actors on stage have now become Kevin Warsh and Scott Bessent. So where does the idea come from that the intentions and declarations of probably the two most important people in the world of finance may be insincere? A collision course between fiscal and monetary policy inside the administration forces us to consider three possible variants of the situation:
- Kevin Warsh was appointed by D. Trump with full awareness that Trump would sabotage his policy and plans.
- Scott Bessent suddenly starts making mistakes he spent most of his career trading against.
- The Fed and the Treasury Department are coordinating actions as part of a broader strategy under a specific plan of the president’s administration.
Everyone involved in the process understands that the current U.S. strategy of managing the yield curve has no chance of long-term success and is only a temporary measure. So why is the U.S. administration digging in its heels? High long-term bond yields are painful for the U.S. because they not only force borrowing at a fixed, high rate, but long-term bonds are also a benchmark for, for example, mortgage loans. Neither the Fed nor the Treasury can solve the root cause, namely the budget deficit and inflation, so they try to manage the curve through issuance. By limiting issuance of long-term paper, its supply falls, and thus its price rises, which mechanically lowers yields.
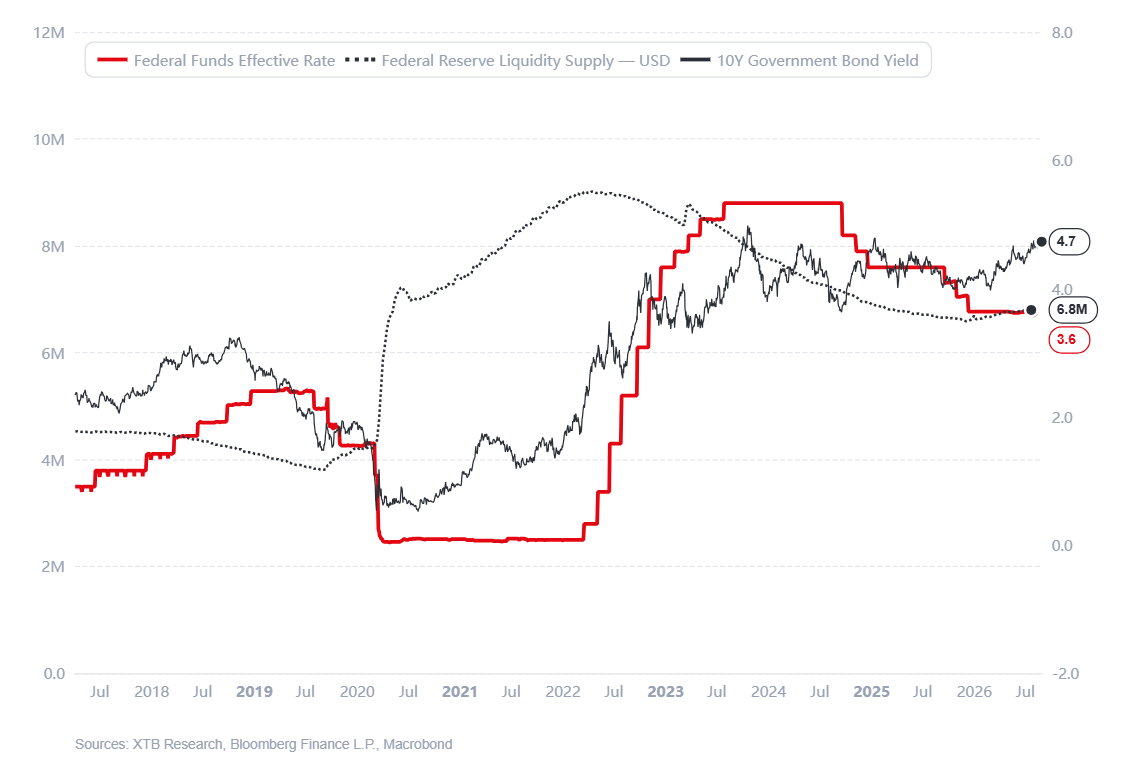
However, borrowing needs remain, so the U.S. borrows at shorter maturities. For now, the success of this strategy is limited. The problem is not the disappointing effect of this financial engineering, but the potential risk.
Rollover
Shorter maturities mean more frequent debt rollovers, which carries a number of implications and risks. Long-term bonds have higher yields because they include a risk premium: more time to maturity means more risk. But if the U.S. government shifts more debt into the short term, the risk does not disappear. It is simply that with long-term bonds the government pays for the risk upfront, while with short-term bonds it pays for it at rollover.
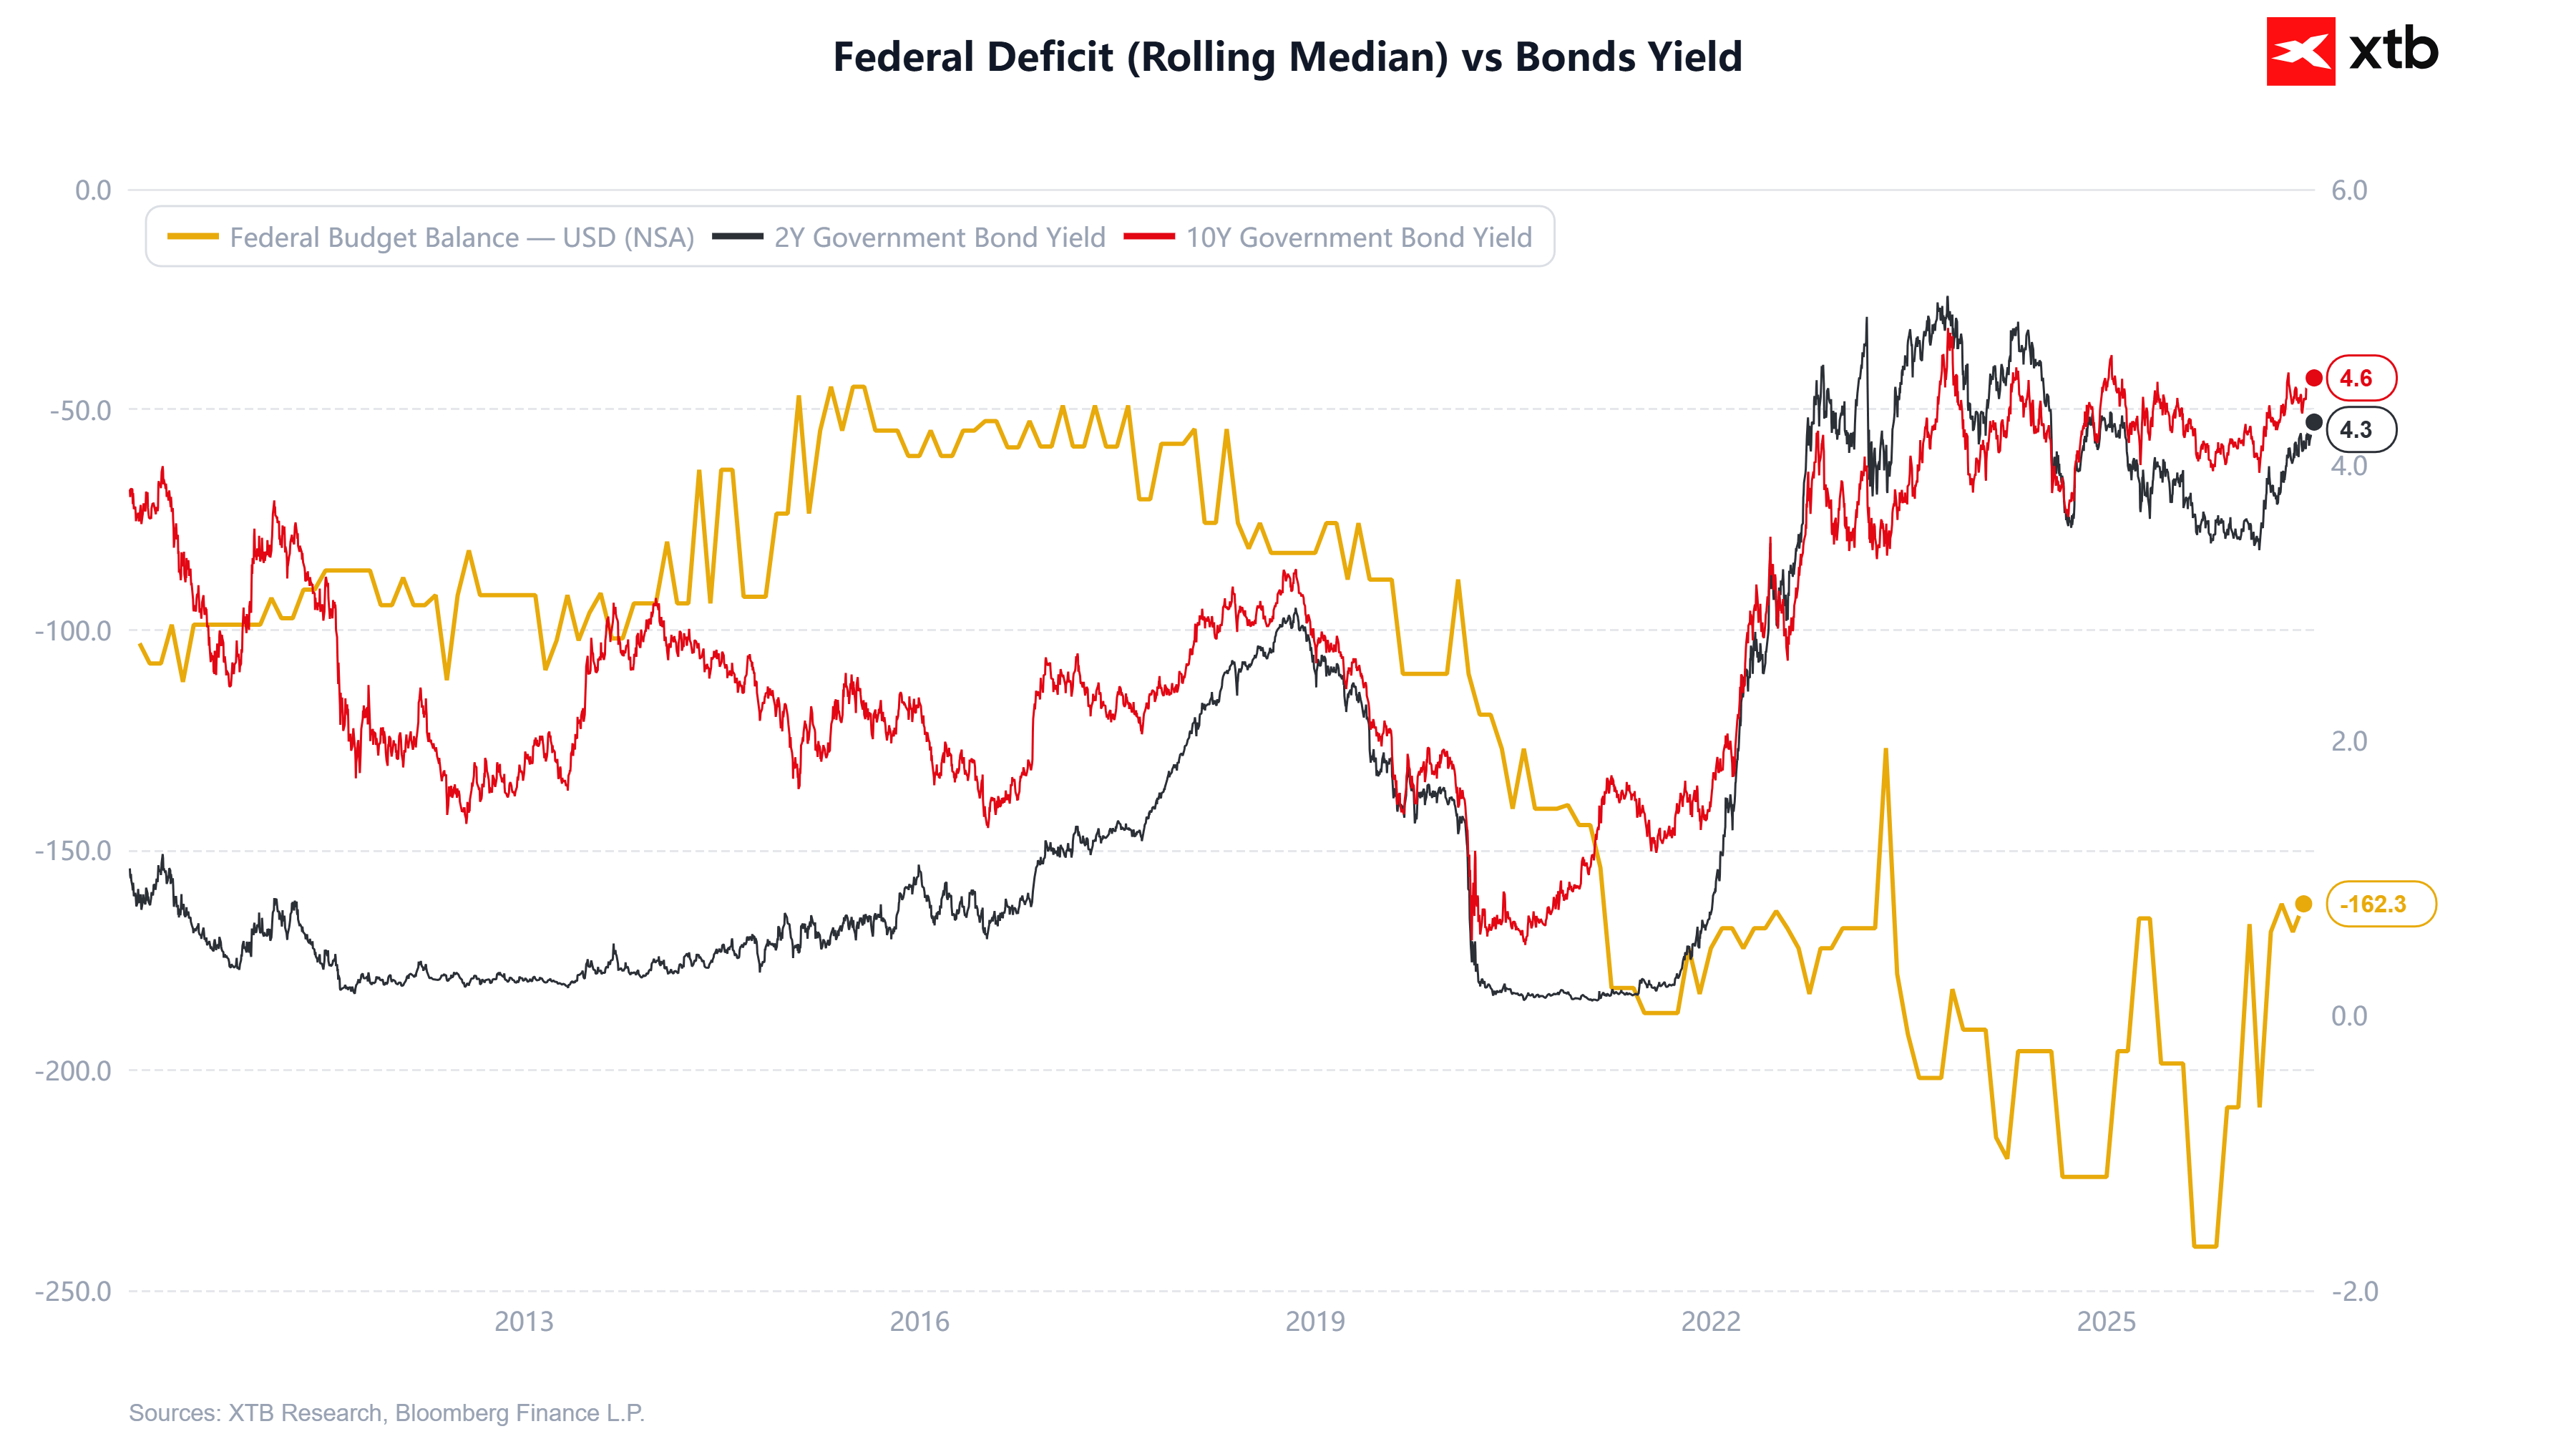
If inflation and the deficit grow faster than the economy, yields will also rise faster; and with more frequent rollovers, the results of fiscal policy will be reflected in the debt market more quickly, because they will be stripped of long-term inertia. After some time, the government may find itself in a situation even worse than the problem it wanted to solve. Unless this is only part of a larger and longer strategy.
Informational Advantage
In one of his recent statements, Scott Bessent noted that the Treasury has a “ disproportionate informational advantage .” These are words with huge, almost ominous implications. Why? A desperate attempt to manage yields through issuance makes long-term sense only if we expect long-term yields to fall to attractive levels (as quickly as possible), one way or another. One particularly interesting phenomenon in this context is the so-called yield curve inversion, the moment when short-term bonds pay more than long-term ones. Almost universally, this phenomenon accompanies financial crises or recessions. Does Scott Bessent see an approaching crisis that justifies his poker moves? Is it the bursting of the AI bubble? Or a military conflict that will shake the market again?
Or could the cause be another of Scott Bessent’s initiatives?
The Treasury Secretary is heavily involved in developing the “stablecoin” market, i.e., crypto tokens backed by safe assets, which in theory is meant to make them safe digital money. Setting aside the usefulness of such an instrument, it is important to Scott Bessent for another reason. Stablecoins have to buy short-term U.S. Treasuries to back their assets and maintain liquidity. That is why Scott Bessent is working so hard on their expansion: these instruments will implement his policy. And how could this lead to a crisis? Bessent himself points out that hundreds of billions of dollars of deposits could flow into stablecoins. But those billions are already somewhere today: they are in banks. Draining liquidity from the financial sector is almost a textbook recipe for a financial crisis. This is especially important in the context of Bessent’s frequent and vocal comments (and those of the rest of the U.S. administration) about the need for further deregulation of the banking sector. If Bessent managed to push large funds into stablecoins and then into bonds, he would obtain cheaper short-term debt and at the same time lay the foundations for a financial crisis that would force the Fed to cut rates deeply. That would allow a return to a normal issuance mix at prices significantly lower than what the market sees today. This is not a forecast or even a base-case scenario, but the hypothesis may prove to be a valuable reference point in the context of future comments and decisions by the Fed chair and the Treasury Secretary.