S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

The Nasdaq-100 Index (US100) has found itself caught between two forces that will dictate its direction in the coming weeks: the Federal Reserve’s continued hawkish stance and disappointing earnings reports from Wall Street’s largest companies, despite their strong results. The Fed kept rates in the 3.75–4.0 percent range, and the market interpreted the 10–2 vote as slightly less hawkish than expected. However, Chairman Kevin Warsh raised several points that tipped the scales. On the one hand, his comments that “the monetary remedy is starting to take effect” and that the economy is not “overheated” weakened the dollar and pulled two-year bond yields down by about 7–8 basis points, to 4.70–4.71 percent.
On the other hand, one sentence was crucial for tech companies. Warsh explicitly acknowledged that there had previously been a theory that rate hikes would not affect the development of AI, but since September he has observed changes in this regard and believes that “interest rates matter in this context.” This is a direct link between the cost of money and the financing of the AI revolution—precisely what drives Nasdaq valuations. The market currently prices in an interest rate hike at the December meeting with a probability of about 85%, and three consecutive rate hikes remain the base-case scenario, although they are no longer fully priced in. For an interest-rate-sensitive index, this is an environment in which the valuations of growth stocks remain under pressure from higher capital costs.
This was compounded by the earnings reports from two Wall Street giants. Microsoft posted a solid quarter, with revenue up 19% and Azure accelerating to 48% year-over-year—well above the forecast of 45%. The stock rose about 3% in after-hours trading. The problem, however, was capital expenditures. CAPEX skyrocketed by 103% to $39.4 billion, pushing free cash flow down and reducing its coverage of net income to 51% from 92% a year earlier. The company is softening the impact of these changes through an accounting policy adjustment—extending the depreciation period for data centers from 15 to 25 years—and a voluntary “buyout” of 60,000 employees, which the market interpreted as active margin management.
Alphabet was received much more negatively; despite a 25% increase in revenue and a 103% surge in Google Cloud, its stock fell more than 8% by the end of the session, testing the psychological barrier of $300. Net income disappointed, falling 25% due to an $8.7 billion loss on equity investments, and EPS came in at $2.12 versus expectations of nearly $3. CAPEX rose 114% to $51.4 billion, while free cash flow turned negative at $9.1 billion. The message to the market is clear: Wall Street is no longer rewarding the mere pace of AI development and the massive scale of investments, and is beginning to ask about actual returns and shrinking cash flows. Source: XTB On the one hand, strong performance by Azure and Google Cloud confirms that the boom is continuing; on the other hand, the Fed’s hawkish stance and rising costs of financing AI expansion are dampening risk appetite.
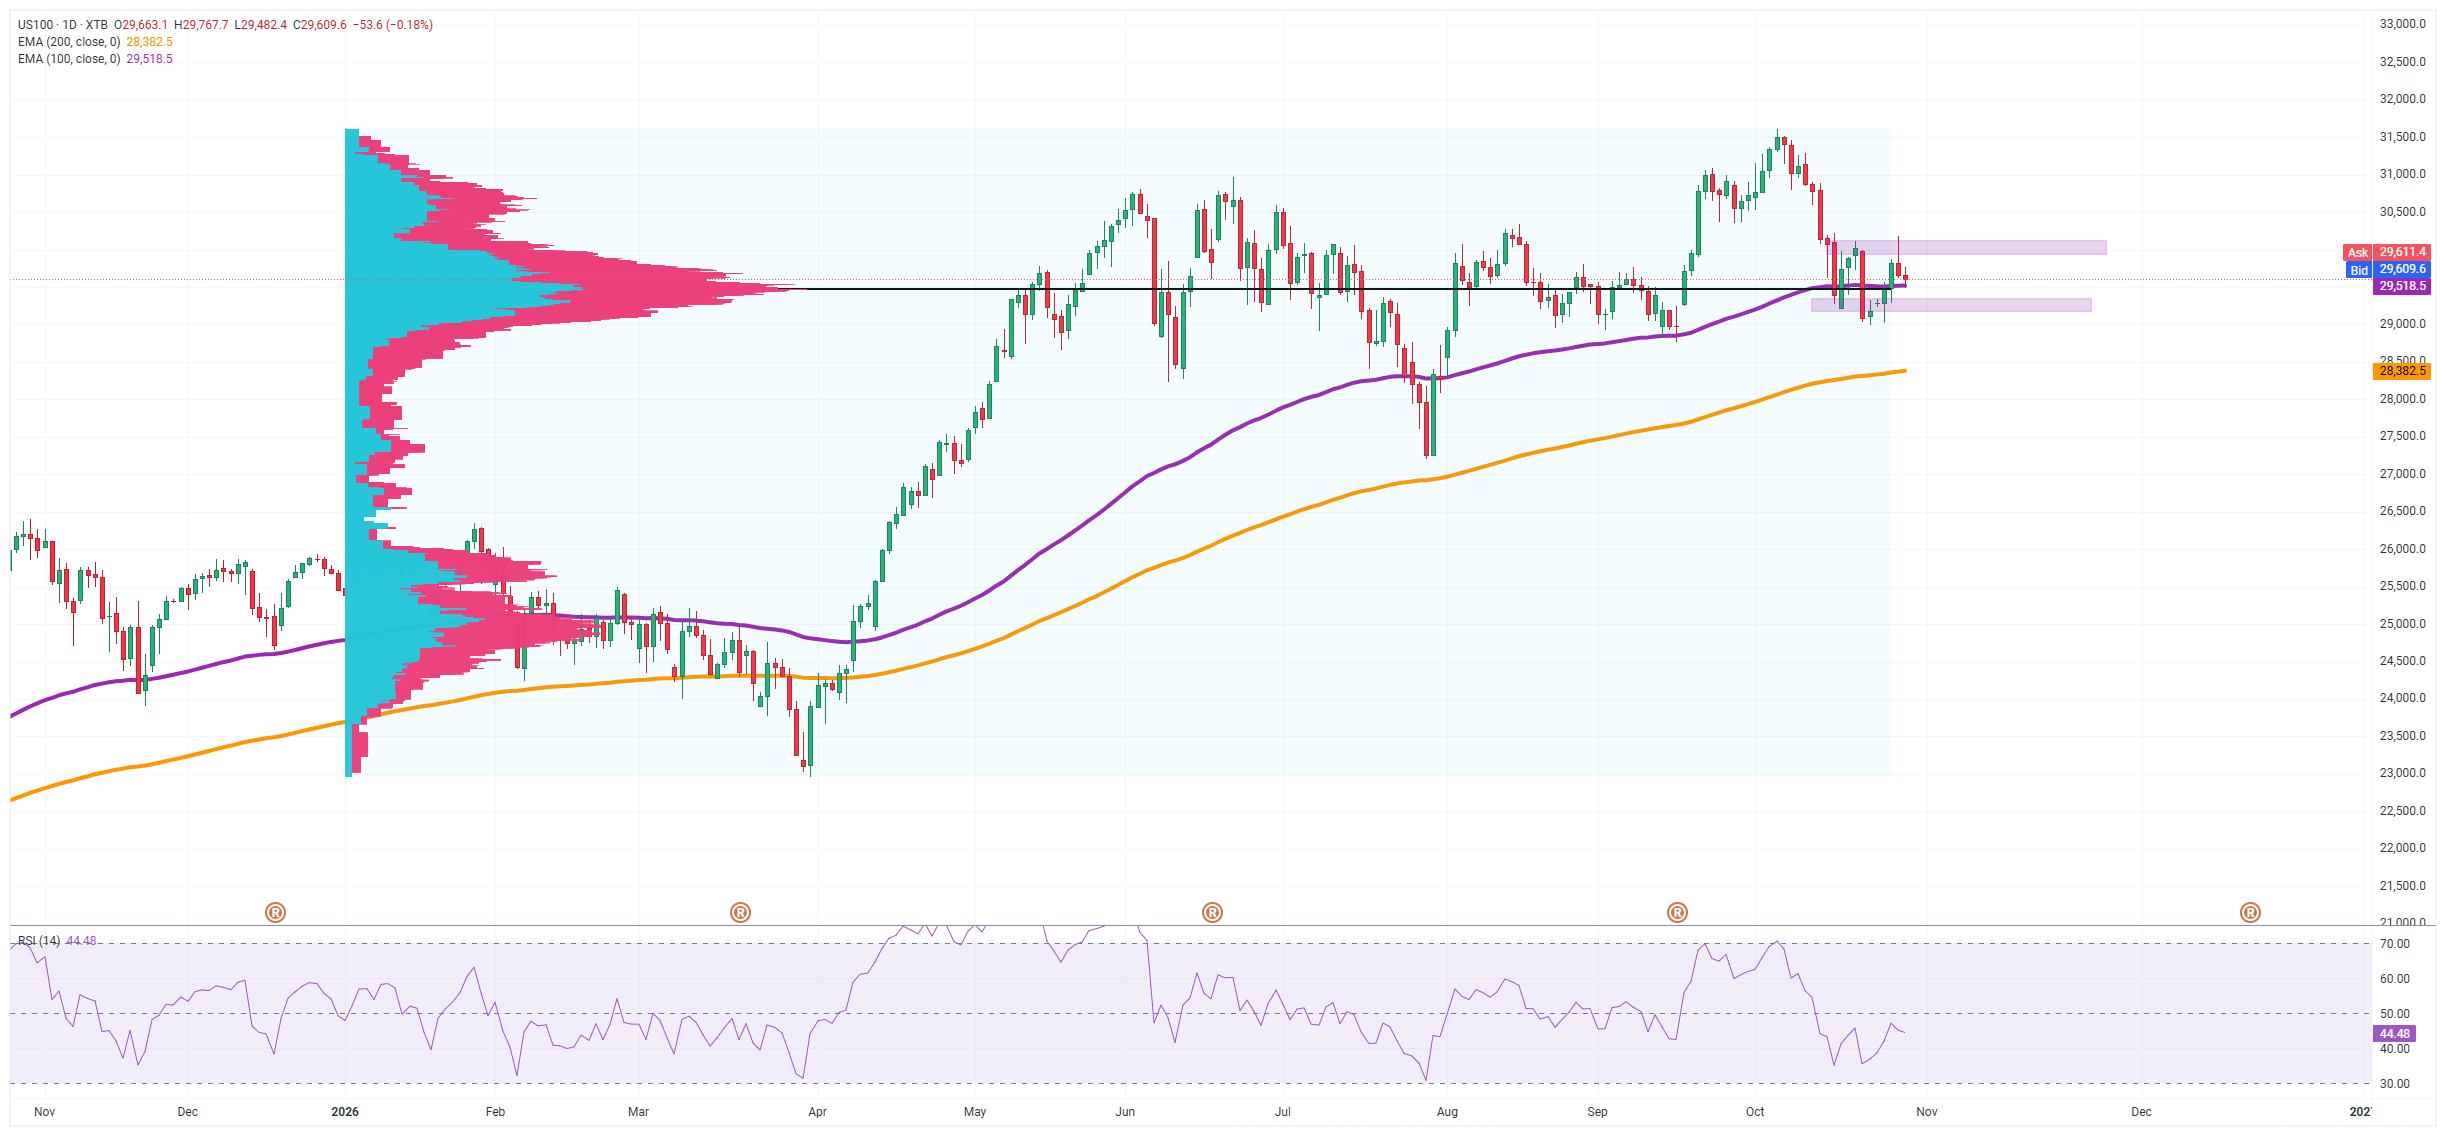
From a technical standpoint, the US100 is indecisive. The index is trading around 29,600 points, just above a cluster of moving averages—namely, the 100-session EMA at 29,518 and the higher consolidation zone. The key factor here is the marked purple resistance zone, stretching roughly between 29,500 and 29,700 points, where prices have been stuck since pulling back from October’s highs around 31,500 points. It is precisely there that the battle between supply and demand is currently taking place, and the index has already attempted to break through it several times without lasting success. Below the market, the 200-session EMA at 28,382 remains a solid support level; it has effectively sustained the uptrend throughout the year, including during the April and August sell-offs. As long as the US100 stays above this average, the long-term uptrend remains intact.
The RSI, at around 44, is neutral, with a slight tilt toward weakness, confirming that the index is more in a phase of consolidation and consolidation than in a clear trend. For the bulls, a sustained break above the purple zone at 29,700 points will be crucial, as this would pave the way for a push toward the October highs. A failure to break through and a drop