S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

U.S. stock indices recovered a small part of their recent losses yesterday as oil prices and bond yields declined, modestly improving risk appetite ahead of Nvidia’s earnings release after the U.S. market close — a key event for the broader AI rally. The Nasdaq 100 outperformed, while semiconductor stocks rebounded after several weaker sessions. Today, Wall Street futures are slightly lower, with attention focused not only on Nvidia’s results but also on U.S. PCE data at 1:30 PM GMT and the oil market, where prices have fallen sharply to around $85 per barrel.
- Brent crude futures (OIL) fell to around $85 per barrel amid hopes that oil shipments through the Strait of Hormuz could resume and signs that the risk of further conflict escalation may be easing. Lower energy prices reduced inflation concerns and supported government bonds.
- Gold is down around 0.3% today, pulling back to $4,650 per ounce, while Bitcoin is holding in the $78,000–79,000 range. The MSCI Asia Pacific Index rose about 1%, supported by gains of nearly 3% in Samsung and SK Hynix and broader strength across the semiconductor sector. The U.S. 10-year Treasury yield fell by around 7 bps as oil prices declined. The Canadian dollar weakened following an escalation in the Canada-U.S. trade dispute.
- AUDUSD is rising after stronger-than-expected inflation data from Australia. Headline CPI increased by 3.5% y/y versus 3.3% expected and 3.8% previously, while trimmed mean inflation came in at 3.6% y/y versus 3.5% expected and 3.6% previously. ANZ Bank expects the Reserve Bank of Australia to raise interest rates by 25 bps in November.
- Yesterday’s macroeconomic data were mixed. U.S. consumer confidence fell to its lowest level since the beginning of the year as assessments of business conditions and labor-market prospects deteriorated. Investors remain relatively cautious ahead of today’s release of the Federal Reserve’s preferred inflation gauge.
- According to unconfirmed media reports, the U.S. and Iran may have reached an agreement on a ceasefire, with an official announcement potentially coming in the coming days. Russian outlet RIA Novosti was among the first to report the information, which markets interpreted as lending some credibility to such a scenario.
- The potential agreement is said to include freedom of navigation through the Strait of Hormuz and a resumption of negotiations under the Islamabad memorandum. Earlier, Axios reported that Marco Rubio had indicated that attacks on Iran would be suspended, at least temporarily.
- Washington and Tehran have not confirmed any agreement , although Oman and Iran have separately proposed an interim mechanism aimed at restoring traffic through the strait. Iranian sources suggest that negotiators are still demanding that the U.S. return to the original memorandum and implement Clause 5, which Tehran interprets as granting it the right to determine transit rules through the Strait of Hormuz.
- The positions of both sides therefore appear relatively unchanged, suggesting that progress remains limited. Yesterday, five vessels carrying commodities passed through the Strait of Hormuz, well below the 10-day average of 15 vessels.
- ECB Executive Board member Isabel Schnabel said the European economy appears to be developing at an increasingly solid pace and that a stronger economy requires higher interest rates. At the same time, she noted that the situation in energy and gas markets remains concerning.
- Intuit and Zoom Communications reported earnings after the U.S. close yesterday. Despite relatively solid results, their shares are down around 10% and 5%, respectively.
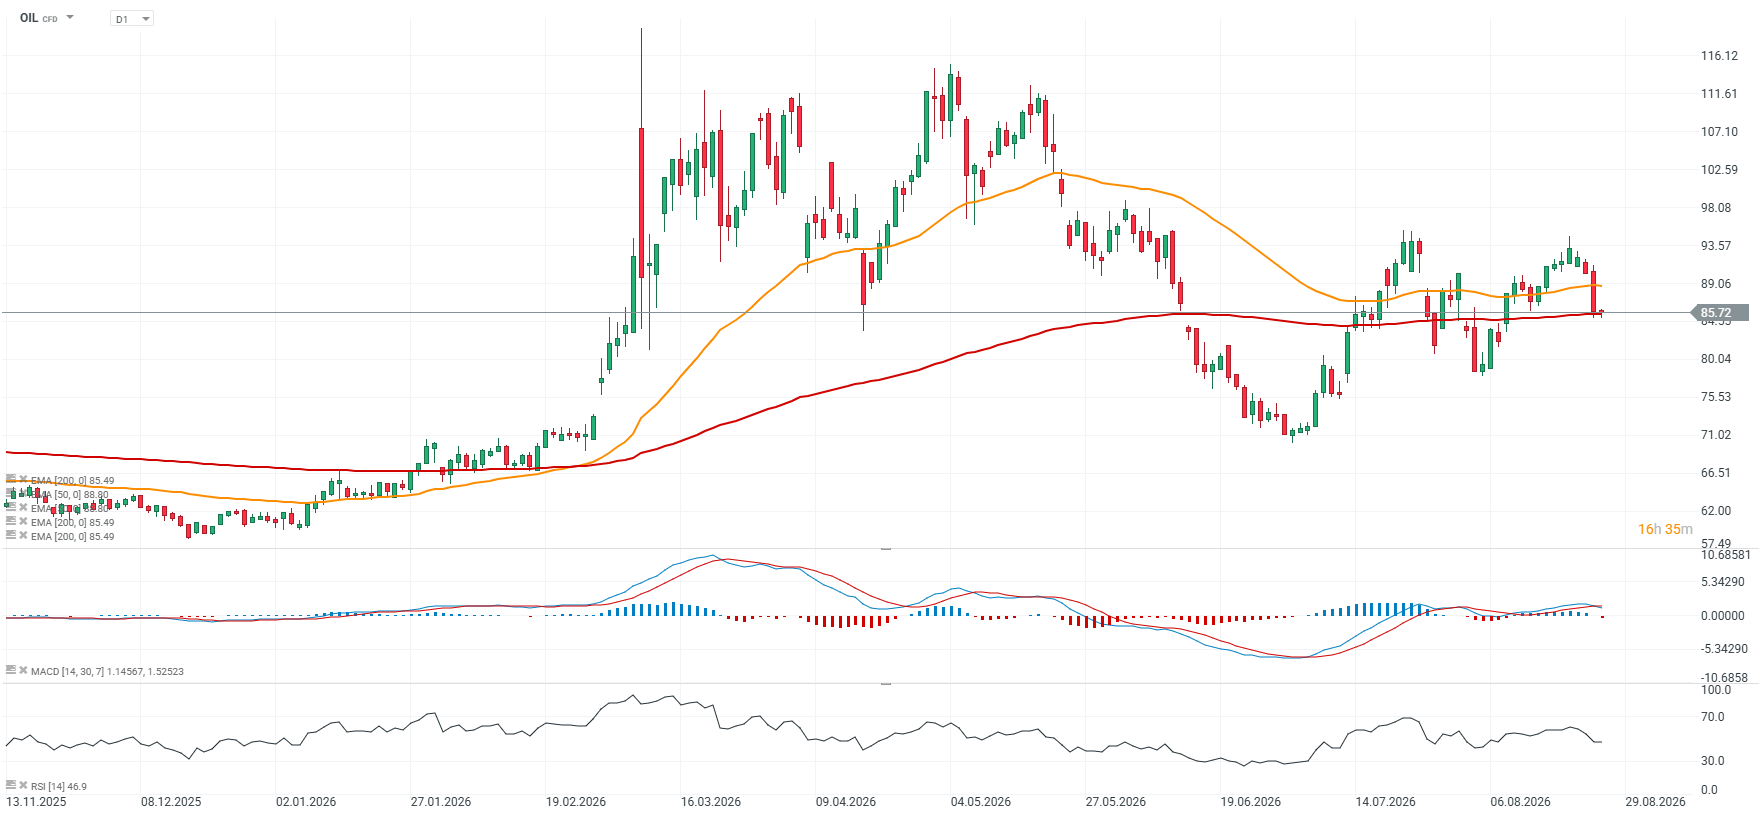
Oil chart (OIL, D1 interval)
Oil futures have reached the 200-session EMA200 for the first time since mid-June and have so far stabilized around that level, as indicated by the lower candle wicks. The technical setup still appears to favor the bears, with a double top visible near $93.5-94. If the $85 level fails to hold as support, the next key zone lies between $78 and $80 per barrel based on price action.
Source: xStation5