S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Economic Calendar – ECB decision and hawkish Bank of Japan in focus

Today’s session on the financial markets will be dominated by the European Central Bank’s interest rate decision (14:15) and the subsequent press conference (14:45). Consensus assumes a 25 basis point hike in the main refinancing rate to 2.65%, and the deposit rate to 2.5%. Another key point of the day will be afternoon US publications (14:30) regarding producer inflation (PPI) and weekly jobless claims, which will shape expectations ahead of the upcoming Federal Reserve meeting. Overnight, investor attention focused on hawkish comments from the Bank of Japan, which translated into a strengthening yen. The geopolitical situation remains tense following reports of damage to US military aircraft in Jordan and Ukrainian attacks on a Russian Caspian Sea port.
Key publications from the Asian session
- United Kingdom: RICS House Price Balance for August showed a reading of -28% against a consensus of -30% (previously -29%). The decline in housing market prices turned out to be slightly milder than expected.
- Australia: MI Inflation Expectations came in at 4.9%, remaining unchanged from the previous month and suggesting price pressures remain anchored at an elevated level.
- Japan: Bank of Japan (BOJ) Board Member Masu signaled the need to quickly raise interest rates to a neutral level and exit negative real rate territory, triggering a surge in the yen.
- President Trump during his speech promised a $5,000 voucher payout for every American if Republicans win the midterms. Earlier, he also indicated that he has no intention to negotiate with Iran, but does not rule out the possibility and wants to end the war after the midterms.
Macroeconomic calendar
- 08:00 Germany – Final CPI MoM. Consensus: 0.2%. Previous reading: 0.2%.
- 10:00 Italy – Industrial Production MoM. Consensus: 0.3%. Previous reading: -1.0%.
- 14:15 Eurozone – Interest Rate Decision (main refinancing rate). Consensus: 2.65%. Previous reading: 2.40%.
- 14:15 Eurozone – Monetary Policy Statement.
- 14:30 US – Core PPI MoM. Consensus: 0.3%. Previous reading: 0.2%.
- 14:30 US – PPI MoM. Consensus: 0.4%. Previous reading: 0.0%.
- 14:30 US – Jobless Claims. Consensus: 205k. Previous reading: 206k.
- 14:45 Eurozone – ECB Press Conference.
- 15:00 Poland – Post-MPC decision press conference featuring Prof. Glapiński.
- 16:00 US – Existing Home Sales. Consensus: 3.98M. Previous reading: 4.06M.
- 16:00 US – Final Wholesale Inventories MoM. Consensus: 1.2%. Previous reading: 1.3%.
- 16:30 US – Natural Gas Storage Change. Consensus: 35 billion cubic feet (bcf). Previous reading: 30 billion cubic feet (bcf).
- 18:00 US – Crude Oil Inventories Change. Consensus: -1.3M barrels. Previous reading: -4.5M barrels.
- 19:01 US – 30-Year Bond Auction. Previous reading: 5.22|2.4.
Corporate earnings
Oracle – after market close
Markets to watch
- EURUSD – The currency pair will come under heavy volatility pressure due to a concentration of key events: the ECB decision (14:15), press conference (14:45), and US PPI inflation readings (14:30).
- USDJPY – The hawkish tone of Masu from the BOJ regarding necessary rate hikes supports the Japanese currency. An additional factor is the record yield spread (316.7 bps) between 10-year Chinese and US bonds.
- Natural Gas (NATGAS) – The release of the weekly US gas storage report at 16:30 (expected increase of 35 billion cubic feet) will determine the price direction for this instrument in the second half of the day.
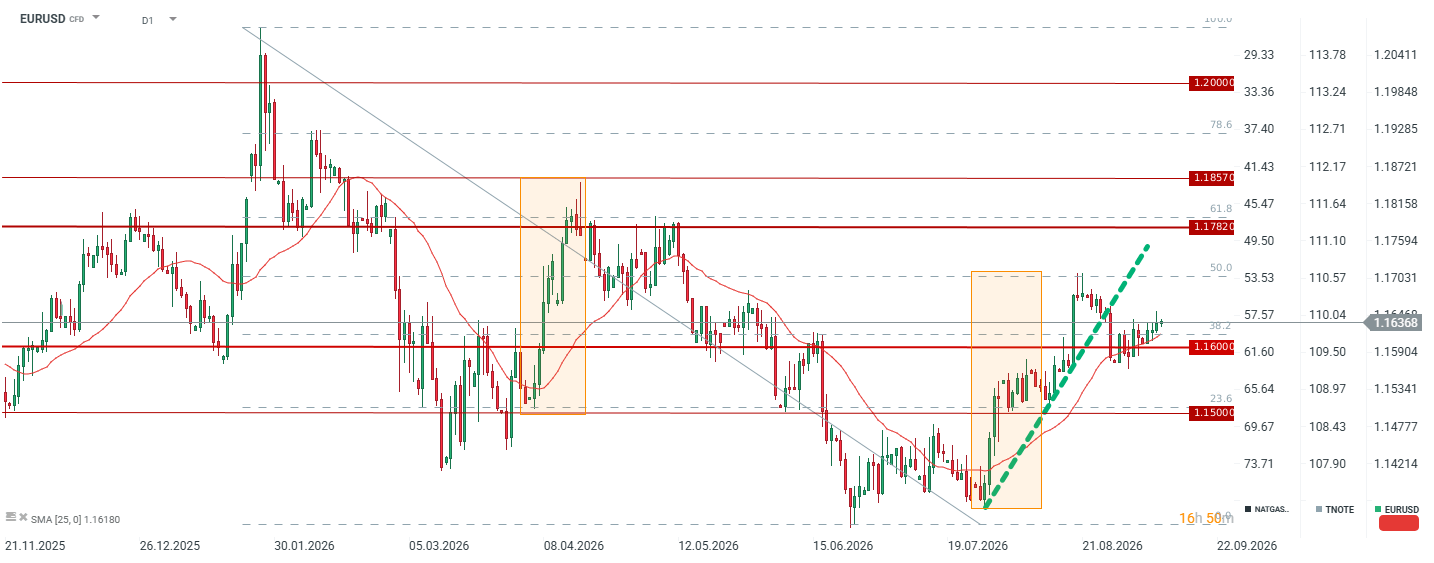
EURUSD returns to an upward trend, but position behavior shows that significant selling pressure remains in the market. EURUSD will need a very hawkish ECB and ambiguous signals from the US ahead of next week’s Fed decision. Source: xStation5