S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Economic Calendar: ECB decision, Oracle results, and US inflation – what to expect?

This week will be dominated primarily by Friday’s release of US inflation data for August. For many FOMC policymakers, these figures could ultimately tip the balance towards either a pause or an interest rate hike at next week’s meeting.
CPI Inflation (Friday, 11.09)
In this context, it is worth recalling the words of Christopher Waller, who stated last Thursday that the disinflation process is progressing, and core inflation actually looks even better than the headline indicators suggest. He noted at the time that if the upcoming CPI inflation reading does not present a negative surprise, he will most likely support keeping interest rates unchanged at the next meeting.
ECB Meeting (Thursday, 10.09)
When discussing monetary policy, it is impossible not to mention Thursday’s decision by the European Central Bank. Figure 1: ECB Implied Policy Path [Number of Priced Hikes] (2026 – 2027)
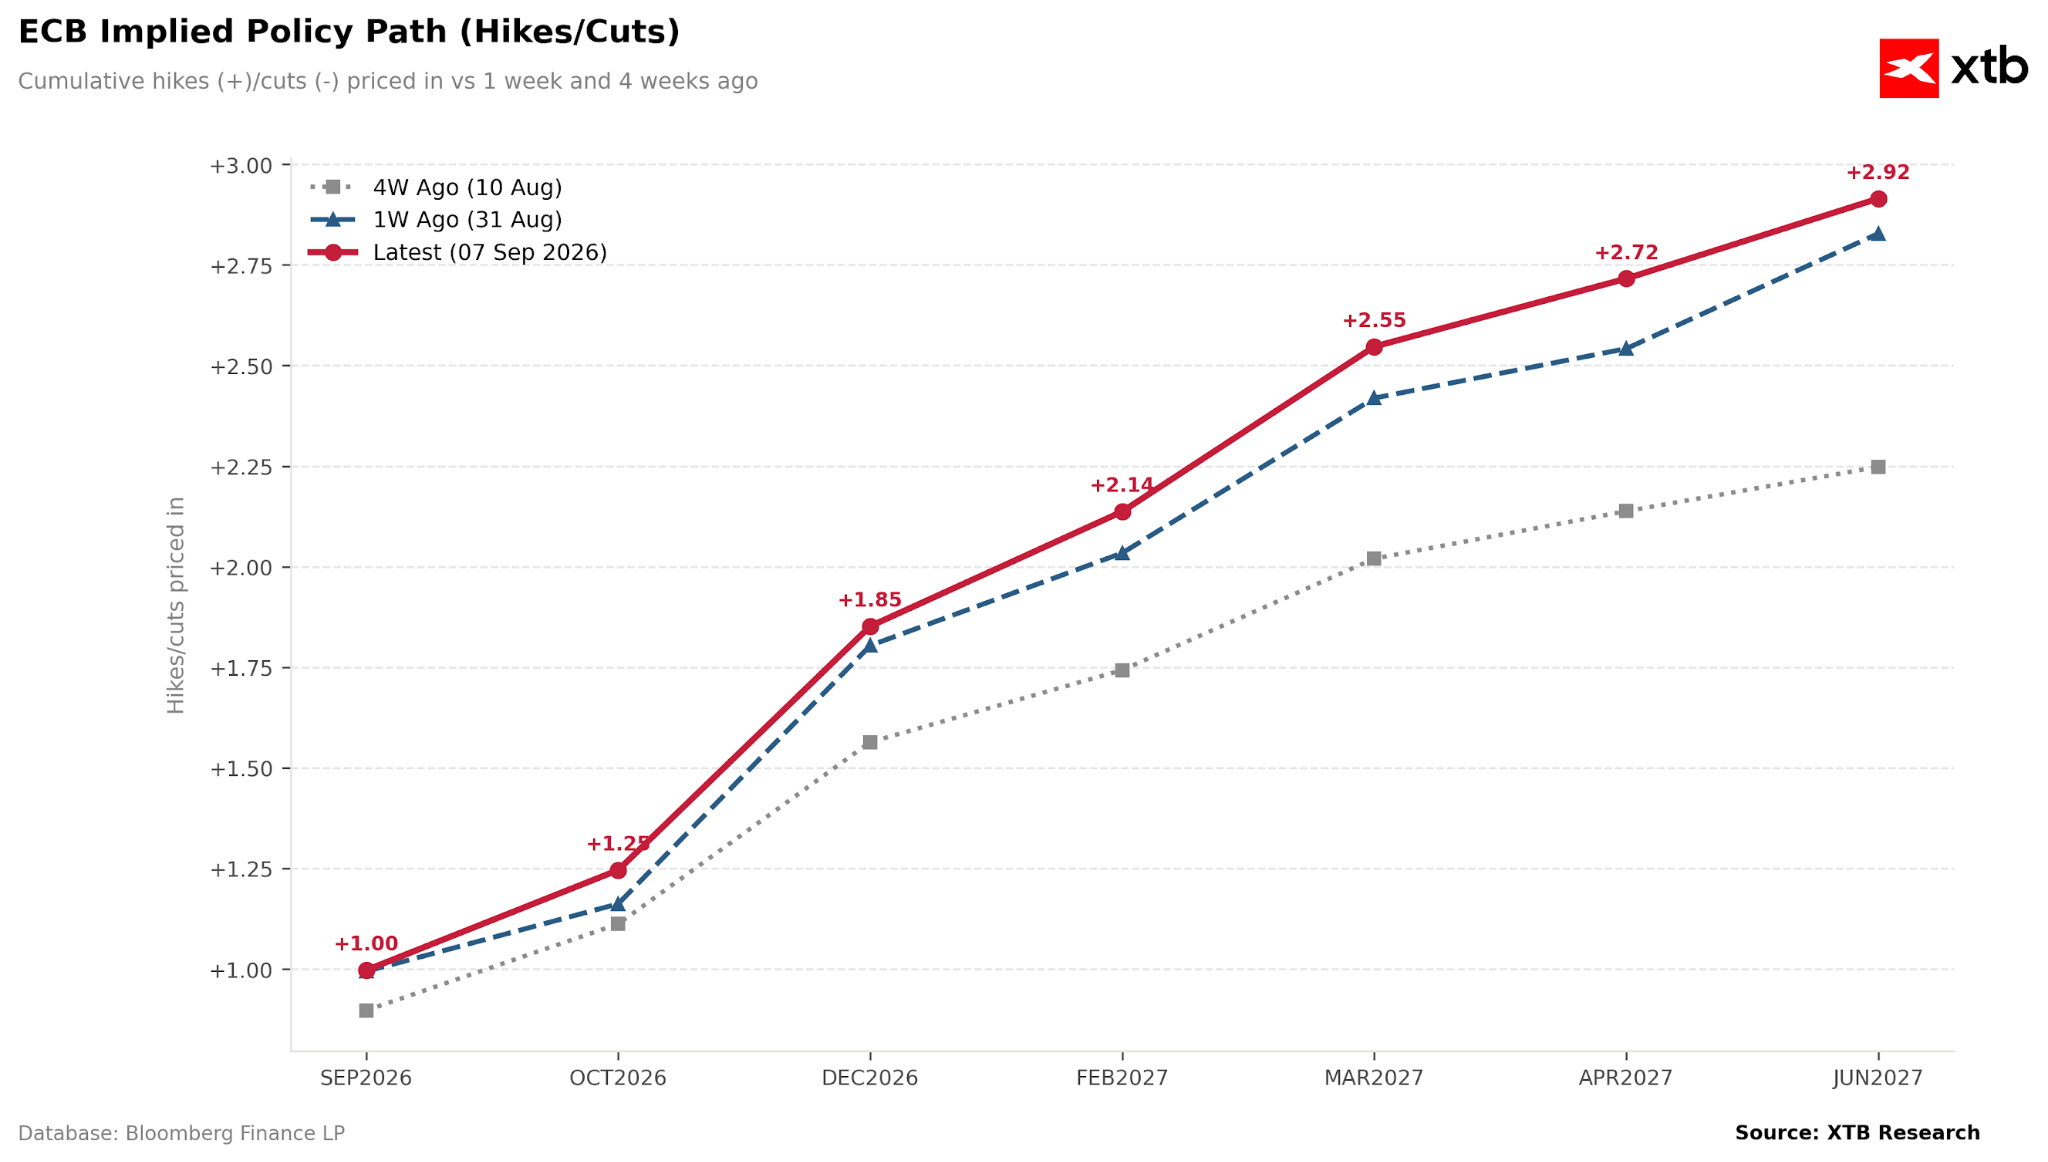
Source: XTB Research, 07.09.2026 As a rate hike is currently fully priced in by the markets, attention will focus on any guidance regarding subsequent moves. Recently, bets on more aggressive monetary policy tightening have increased (primarily due to the dynamic rise in TTF gas prices). The market expects a total of three upward moves by mid-2027.
Oracle Results (Thursday, 10.09)
On Thursday, after the Wall Street market close, Oracle will present its financial results. Investors’ attention will focus primarily on the revenue growth in the cloud segment and the value of the backlog of future orders, which serve as the main indicator of monetising the growing demand for AI infrastructure. As with other companies in the broader AI ecosystem, the bar is set exceptionally high. Current data will be highly important, but the guidance will be critical.
🌏 Key Macroeconomic Releases
The end of last week was dominated by the key release of NFP data. This week has started quietly – with inflation data from Sweden and industrial production from Germany.
Friday
United States
- The headline reading, i.e. the change in non-farm payrolls, rose to its highest level since March (162k), landing significantly above expectations.
- Food services (+59k) and local government education (+42k) accounted for over 60% of the August increase. However, the share of industries expanding employment rose to 55.6% (the highest level since December 2024).
- The data for the previous two months were revised upwards by 55k.
- However, the market reaction was not as strong as might be inferred from the above figures. The key unemployment rate remained unchanged (4.1%), and wage growth surprised only very slightly on the upside in annual terms (3.1%).
- The lack of a decline in the unemployment rate was largely due to an increase in the participation rate (to 61.6%).
The market-implied probability of a September rate hike rose to 60% (compared to approximately 50% before the release). Figure 2: Change in the Market-Implied Probability of a September Rate Hike (2025 – 2026)
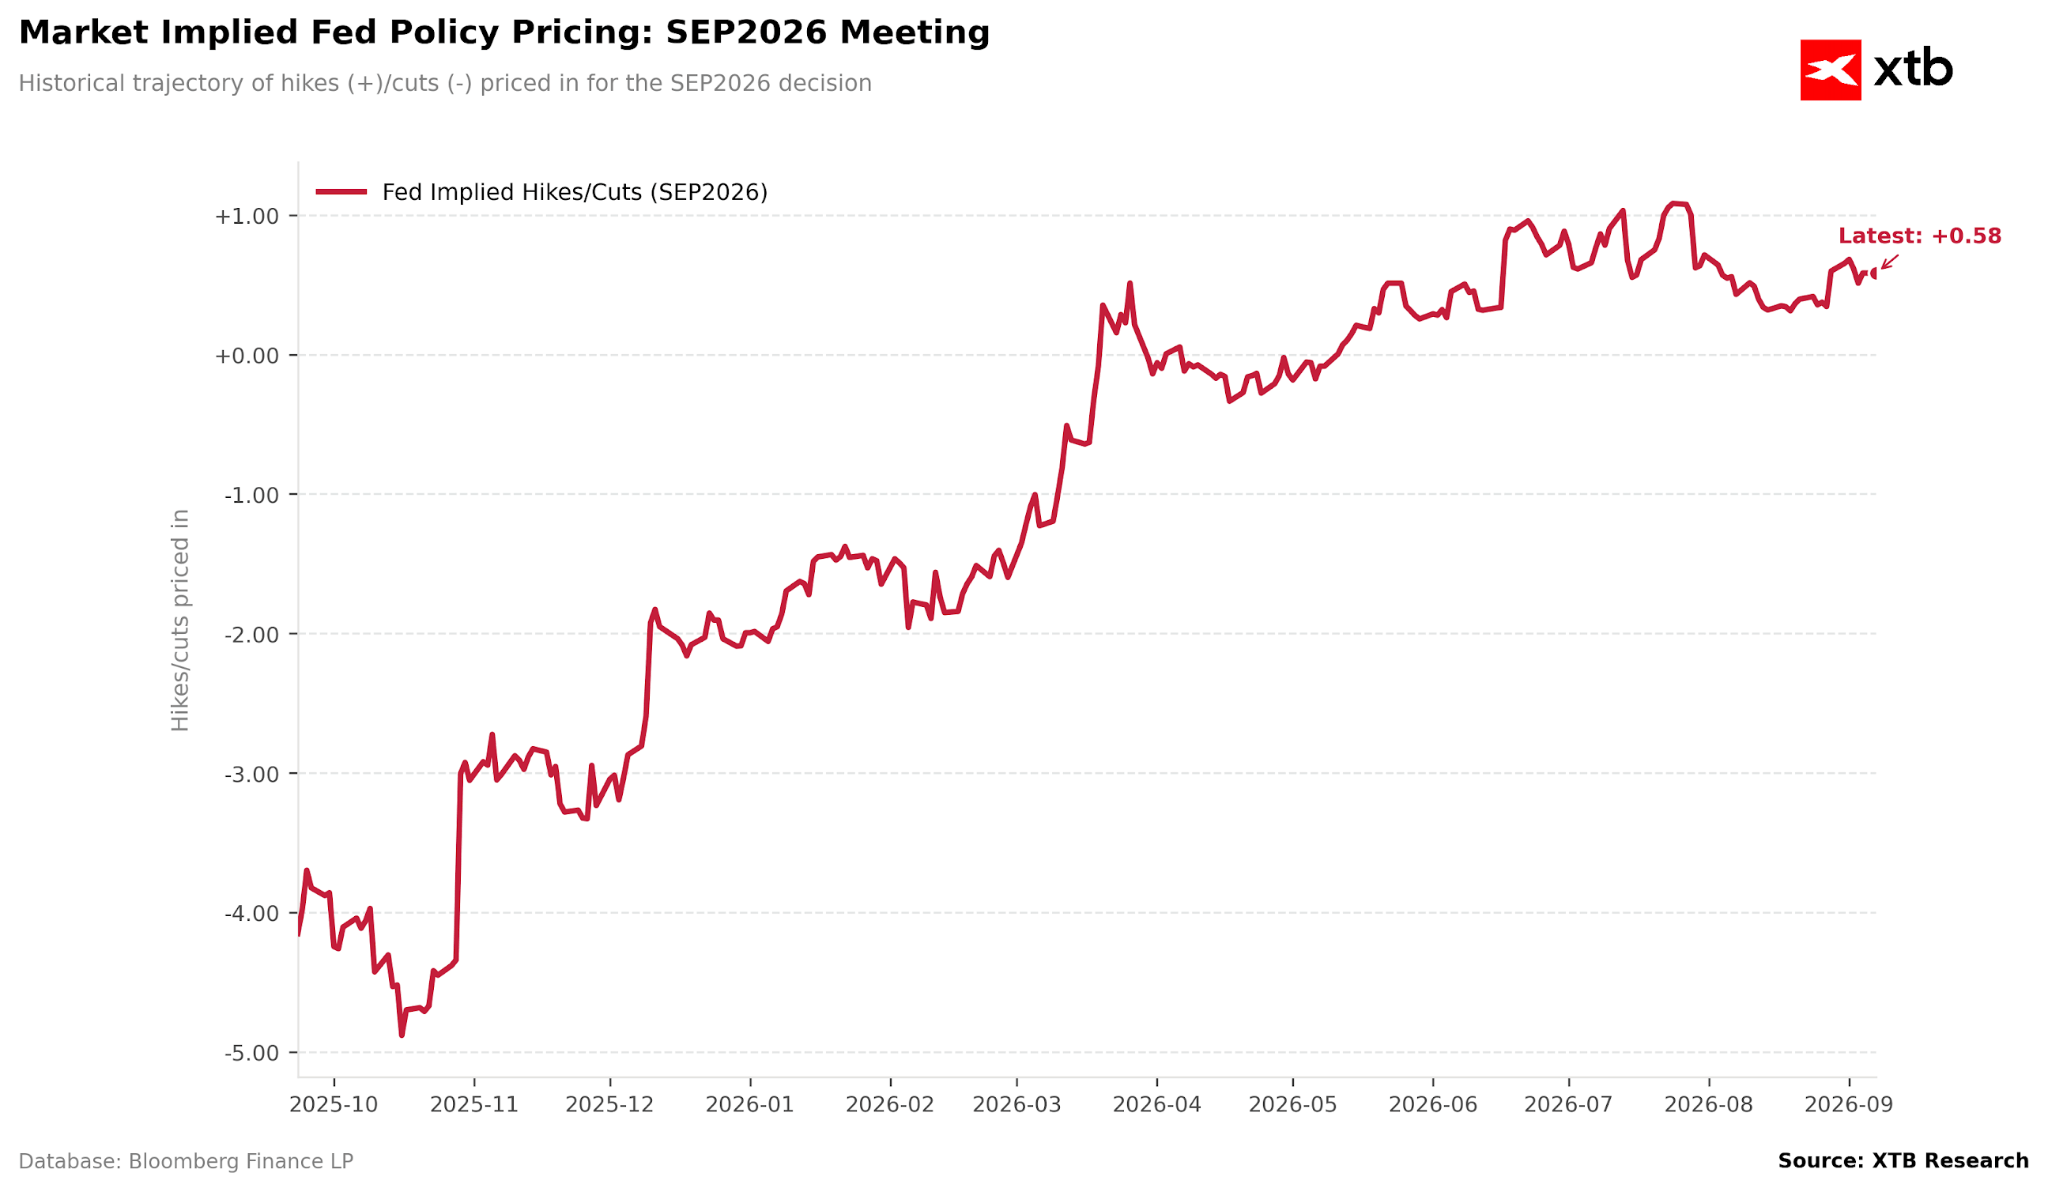
Source: XTB Research, 07.09.2026
Monday
Sweden
Inflation data surprised on the downside. Both the CPIF (0.7%; calculated at constant interest rates) and the CPI (0.3%) came in lower than expected. A rate hike in September is currently not considered a realistic option by investors (approx. 10% market-implied probability). The base scenario is an upward move only in December.
Germany
Hard data on industrial production for July failed to match the trend previously outlined by the leading PMI figures. The indicator fell by 1.1% month-on-month.
📆 Economic Calendar
Today, Labour Day is celebrated in the United States, meaning Wall Street will remain closed. Attention will shift to European markets. However, from a macroeconomic perspective, it will not be an intensive day.
Monday
- Eurozone: GDP growth in Q2 (revision)Time: 10:00 AMPreliminary reading: 0.4% q/q
- Time: 10:00 AM
- Preliminary reading: 0.4% q/q
Tuesday
- Japan: Wage growth in JulyTime: 12:30 AMPrevious: 2.8%Consensus: 3.9%
- Time: 12:30 AM
- Previous: 2.8%
- Consensus: 3.9%
- Hungary: CPI inflation in AugustTime: 07:30 AMPrevious: 1.2%Consensus: 1.4%
- Time: 07:30 AM
- Previous: 1.2%
- Consensus: 1.4%
🗂️ Corporate earnings releases
None – Labour Day in the US. 3 markets to watch
- OIL: The lack of optimistic headlines from the Middle East has led to further increases in the prices of key energy commodities. A barrel of Brent crude is currently trading near 100 dollars (an increase of over 10% on a weekly basis).
- EU50: In the absence of trading on the US market, market attention will focus on European indices. Red dominates in early trading.
- EURUSD: A stronger-than-expected NFP reading supported the dollar, though the move was modest. The pair is waiting for two events of fundamental importance: Thursday’s ECB meeting (especially guidance from President Lagarde) and Friday’s CPI inflation data from the United States.