S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

EUR/USD Under Renewed Selling and Central Bank Narritives

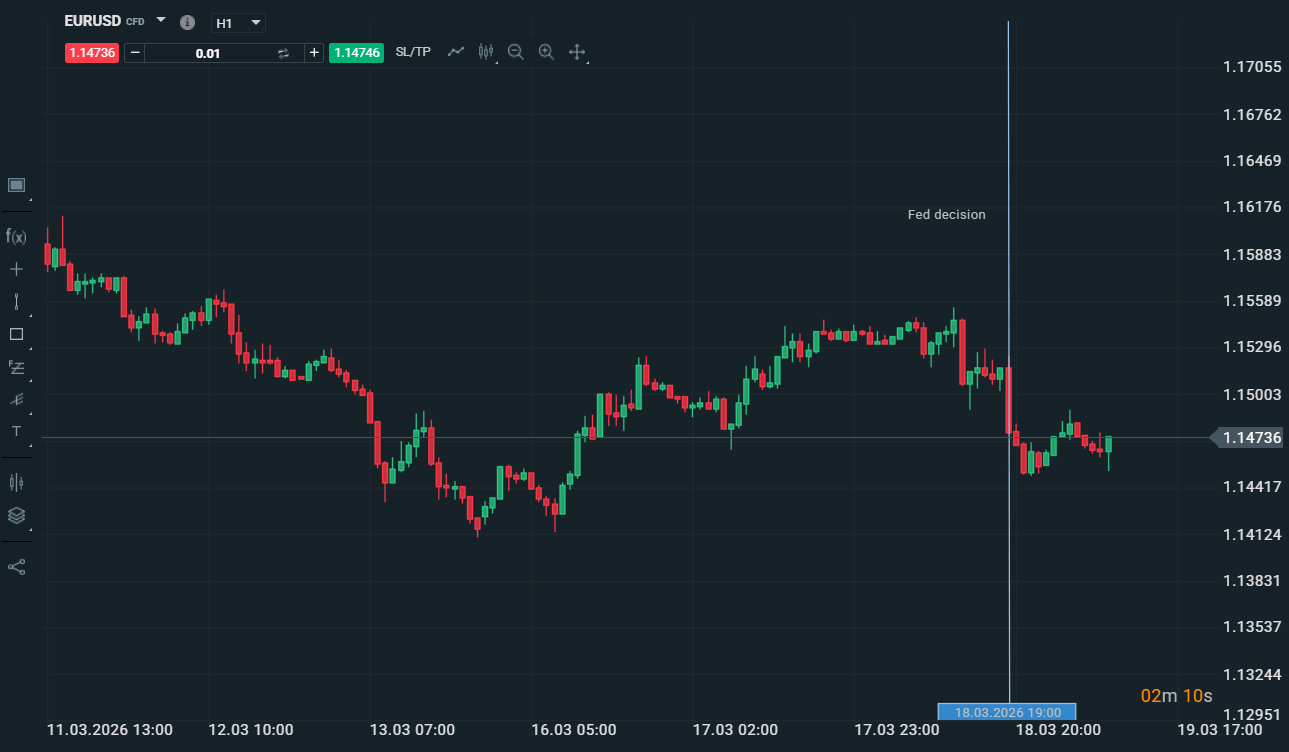
EURUSD is currently under renewed downward pressure, approaching the 1.1450–1.1500 area. A stronger US dollar and rising geopolitical uncertainty are dominating the macro environment. The key driver of recent moves is the energy shock related to the conflict with Iran, which has significantly altered expectations for both the Fed and European central banks.
As for the Federal Reserve, yesterday’s decision was in line with expectations – interest rates remained at 3.50%–3.75%. However, the overall message was more hawkish than the market had initially assumed. The Fed maintained its forecast for rate cuts in 2026–2027, but fewer FOMC members now support easing, and inflation risks have clearly increased. Jerome Powell emphasized that higher oil prices could push inflation back above 3% in the short term, while also noting that policy remains data-dependent and moderately restrictive.
The market reaction reflected this mixed but hawkish message:
- the initial weakening of the dollar was quickly reversed
- EURUSD briefly moved higher but then fell below 1.1500 and has remained in that zone since
Overall, the Fed remains in a “wait-and-see” mode, but with a more cautious and slightly hawkish bias, which supports the dollar in the short term.
On the European side, the situation has shifted much more dynamically. The conflict with Iran has once again highlighted stagflation risks, which are more significant for the euro area than for the US. Although Europe is better prepared than in 2022 (stronger euro, more diversified energy sources, improved supply chains), it remains much more sensitive to an oil market shock. Oil prices in the 100–120 USD range would have a clearly negative impact on both growth and inflation in Europe.
This has already led to a significant shift in ECB communication and market expectations:
- a transition from a “wait-and-see” narrative to a slightly hawkish tone (Lagarde, Nagel)
- upward revisions of inflation forecasts (e.g., Nomura: 2.1% → 2.7%)
- a shift in market pricing from rate cuts toward potential rate hikes
Despite this shift, the ECB is expected to keep rates unchanged today at around 2.0%. The lack of hard data and the desire to avoid signaling panic argue against immediate action, but the medium-term policy path is becoming increasingly dependent on energy prices. If oil prices remain elevated, a rate hike later this year becomes a realistic scenario.
Today is particularly important for EURUSD, as several European central banks are announcing decisions in quick succession. The SNB is likely to keep rates at 0.00%, balancing between deflation risks and a strong franc. The Bank of England is also expected to leave rates at 3.75%, with the vote split being key. The Riksbank is likely to remain at 1.75%.
Across Europe, a common trend is visible: expectations for rate cuts have been pushed back, and central banks are shifting toward a more cautious or even hawkish stance due to geopolitical and inflation risks. However, this is not yet fully reflected in actual policy decisions.
EURUSD stands between a hawkish Fed and rapidly shifting expectations for the ECB. However, the energy shock and Europe’s greater sensitivity to oil prices tilt the short-term balance in favor of the dollar, leaving the pair with a slightly bearish bias ahead of today’s central bank decisions. The market will closely monitor upcoming events.
The material on this page does not constitute financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other specific needs. All information provided, including opinions, market research, mathematical results and technical analyzes published on the Website or transmitted To you by other means, it is provided for information purposes only and should in no way be construed as an offer or solicitation for a transaction in any financial instrument, nor should the information provided be construed as advice of a legal or financial nature on which any investment decisions you make should be based exclusively To your level of understanding, investment objectives, financial situation, or other specific needs, any decision to act on the information published on the Website or sent to you by other means is entirely at your own risk if you In doubt or unsure about your understanding of a particular product, instrument, service or transaction, you should seek professional or legal advice before trading. Investing in CFDs carries a high level of risk, as they are leveraged products and have small movements Often the market can result in much larger movements in the value of your investment, and this can work against you or in your favor. Please ensure you fully understand the risks involved, taking into account investments objectives and level of experience, before trading and, if necessary, seek independent advice.