S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

European stock indices opened Monday’s session with slight gains—the German DAX rose 0.86%, the Italian FTSE MIB rose 0.51%, and the French CAC 40 rose 0.57%, and the pan-European STOXX 600 edged up 0.4% to 613 points. Market sentiment is primarily shaped by geopolitical developments in the Middle East and expectations ahead of key central bank meetings this week. According to Axios reports, Iran has proposed to the United States that the Strait of Hormuz be reopened and the war ended, while postponing nuclear negotiations—a move the market received with cautious optimism, although President Trump had previously canceled a planned diplomatic mission to Pakistan.
Brent crude rose by more than 2% to about $107.50 per barrel, while WTI rose by about 1.8% to over $96, after Iran’s Islamic Revolutionary Guard Corps seized two container ships near the Strait of Hormuz, fueling fears of disruptions to oil supplies.
The U.S. dollar weakened slightly across the board—the USDIDX index fell by 0.2%, while the EUR/USD exchange rate remained above 1.174. On European stock markets, the oil & gas sector performed best, gaining nearly 0.9% thanks to rising oil prices, as did the banking sector, where companies such as BBVA (+1.6%), BNP Paribas (+1.8%), and UniCredit (+1.3%) posted solid gains. The worst performers were the consumer staples sector (food & beverage -0.5%) and the technology sector, weighed down by capital rotation toward commodity and defense companies.
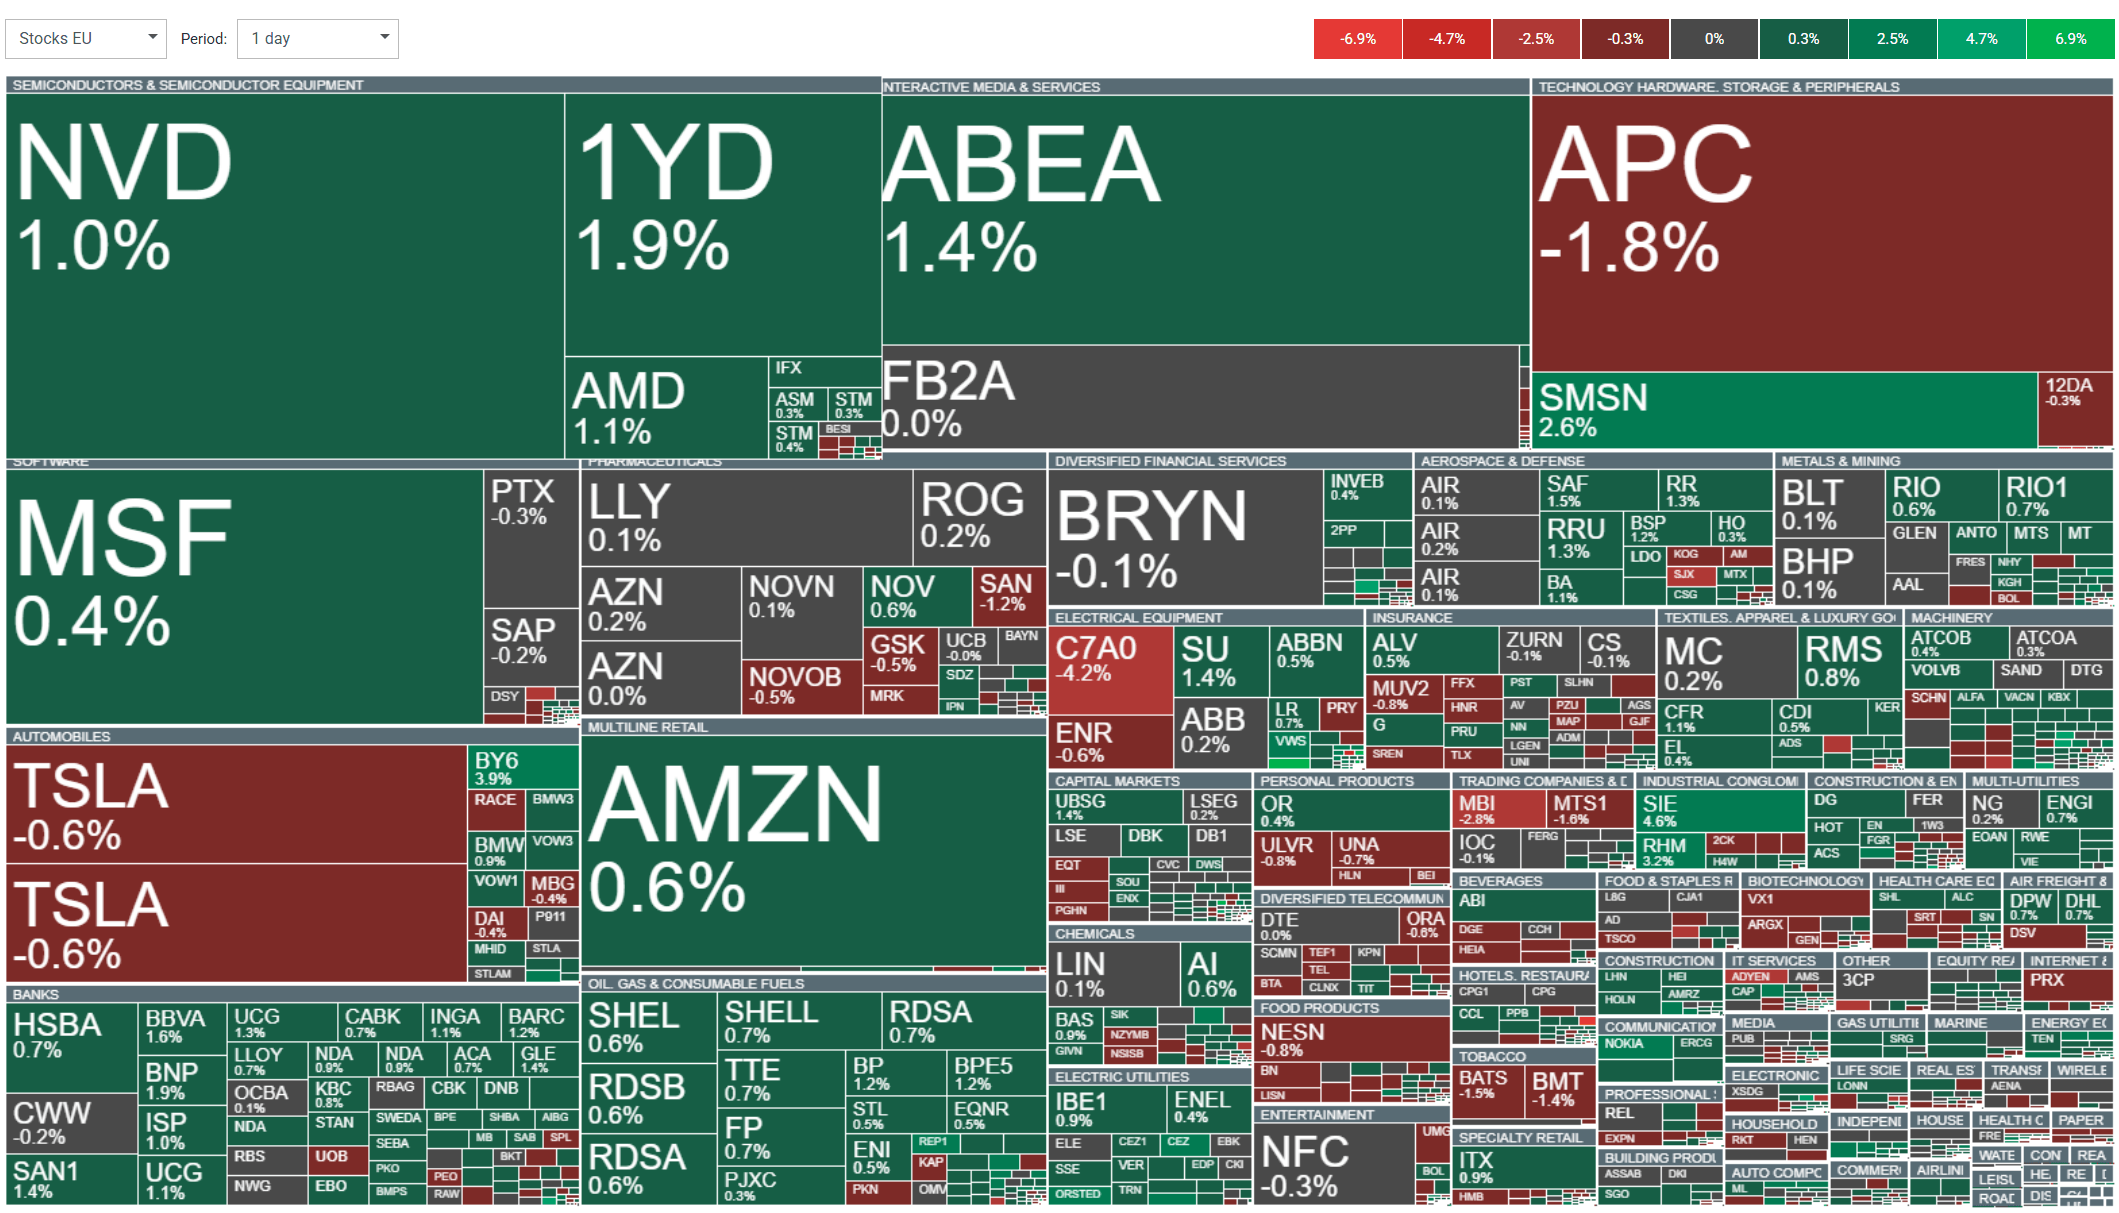
Source: xStation Company information:
- The clear leader in gains on the STOXX 600 was German wind turbine manufacturer Nordex, whose shares soared by more than 12% following the release of its first-quarter results—net profit rose to €53.6 million from €7.9 million a year earlier, while revenue increased by 10.6% to €1.6 billion, beating market consensus. The positive sentiment spread across the entire sector—Denmark’s Vestas gained 3%, and Oersted rose 3.9%.
- Sartorius shares rose by more than 4% after Berenberg upgraded its rating to “buy,” noting that the sell-off following the first-quarter results was an overreaction and pointing to improved prospects in the bioprocessing segment.
- French auto parts supplier Forvia fell by about 2.8% despite announcing the sale of its automotive interiors division to Apollo Funds for €1.82 billion—the transaction is expected to reduce net debt by €1 billion, but investors were concerned about pricing terms in a challenging market environment.
- British company Intertek fell 3.3% after rejecting an increased takeover bid from Swedish fund EQT of £54 per share.
- Germany’s Rheinmetall continued its upward trend (+3.5%), buoyed by the SIPRI report released on Monday, which showed record global defense spending reaching $2.89 trillion, with Europe as the main driver of growth (+14% year-over-year).
Global defense spending reached a record high of $2.89 trillion in 2025, marking the eleventh consecutive year of growth, according to a report released Monday by the Stockholm International Peace Research Institute (SIPRI). The main driver of growth was Europe, where defense spending jumped 14% year-over-year, reaching $864 billion. Germany—excluding Russia—became Europe’s largest contributor to defense spending, increasing its outlays by 24% to $114 billion. For the first time since 1990, Berlin exceeded the 2% of GDP threshold set by NATO, reaching 2.3%. Spain, in turn, increased its spending by as much as 50% to $40.2 billion, also exceeding the 2% of GDP threshold for the first time since NATO’s target was established in 1994.
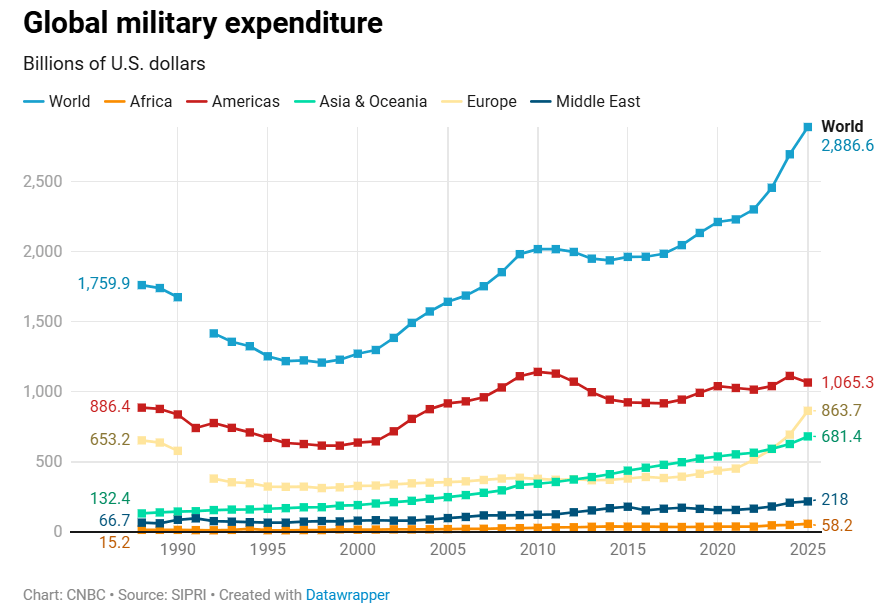
Source: SIPRI via CNBC