S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- The British Pound trades firmly at around 1.3500 against the US Dollar.
- Investors await the US CPI data for July and the UK Q2 GDP data.
- The Fed is not expected to raise interest rates in September anymore.
The British Pound (GBP) holds onto two-day gains marginally at around 1.3500 against the US Dollar (USD) during the Asian trading session on Tuesday. The GBP/USD pair remains firm as the British Pound outperforms despite financial markets pricing out the possibility of an interest rate hike by the Bank of England (BoE) in the near term.
Pound Sterling Price This week
The table below shows the percentage change of British Pound (GBP) against listed major currencies this week. British Pound was the strongest against the Japanese Yen.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 0.08% | -0.18% | 0.89% | -0.14% | 0.08% | 0.12% | 0.29% | |
| EUR | -0.08% | -0.27% | 0.79% | -0.29% | -0.06% | -0.06% | 0.11% | |
| GBP | 0.18% | 0.27% | 1.01% | -0.03% | 0.21% | 0.23% | 0.36% | |
| JPY | -0.89% | -0.79% | -1.01% | -0.71% | -0.47% | -0.59% | -0.39% | |
| CAD | 0.14% | 0.29% | 0.03% | 0.71% | 0.25% | 0.12% | 0.47% | |
| AUD | -0.08% | 0.06% | -0.21% | 0.47% | -0.25% | 0.00% | 0.14% | |
| NZD | -0.12% | 0.06% | -0.23% | 0.59% | -0.12% | -0.00% | 0.15% | |
| CHF | -0.29% | -0.11% | -0.36% | 0.39% | -0.47% | -0.14% | -0.15% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the British Pound from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent GBP (base)/USD (quote).
Strategists at Rabobank point out that “for the UK, the market is currently pricing in a reduced expectation of a rate hike by the end of the year,
This week, the major trigger for the British currency will be the preliminary United Kingdom (UK) Q2 and the June month Gross Domestic Product (GDP) data, which will be released on Thursday. In the April-June period, the UK economy is expected to have grown at a moderate pace of 0.4% vs. the previous reading of 0.6%. On a monthly basis, the GDP is seen contracting by 0.1%.
Meanwhile, the US Dollar Index (DXY) trades almost flat at press time, holding onto Monday’s recovery move at around 99.80. The USD Index is expected to remain sideways as investors await the United States (US) Consumer Price Index (CPI) data for July, which will be released on Wednesday.
US inflation seen firming but not reaccelerating in July
Brown Brothers Harriman’s Elias Haddad expects the upcoming US July CPI report to show inflation “firm modestly but stop short of signaling a renewed acceleration in inflation.” He notes that “headline CPI is expected to rise +0.1% m/m vs. -0.4% in June and ease to 3.4% y/y vs. 3.5% in June,” while “core CPI is expected to rise +0.2% m/m vs. 0.0% in June and ease to 2.5% y/y vs. 2.6% in June.” The data are due Wednesday and, in Haddad’s view, should confirm a gradual cooling in underlying price pressures rather than a renewed upswing.
The US inflation data will have a significant impact on the Federal Reserve’s (Fed) interest rate expectations, as the July monetary policy statement showed heightened concerns among policymakers toward upside inflation risks.
Lately, traders have priced out the possibility of a Fed interest rate hike in the September meeting after the release of weak US Nonfarm Payrolls (NFP) data for July.
GBP/USD Technical Analysis
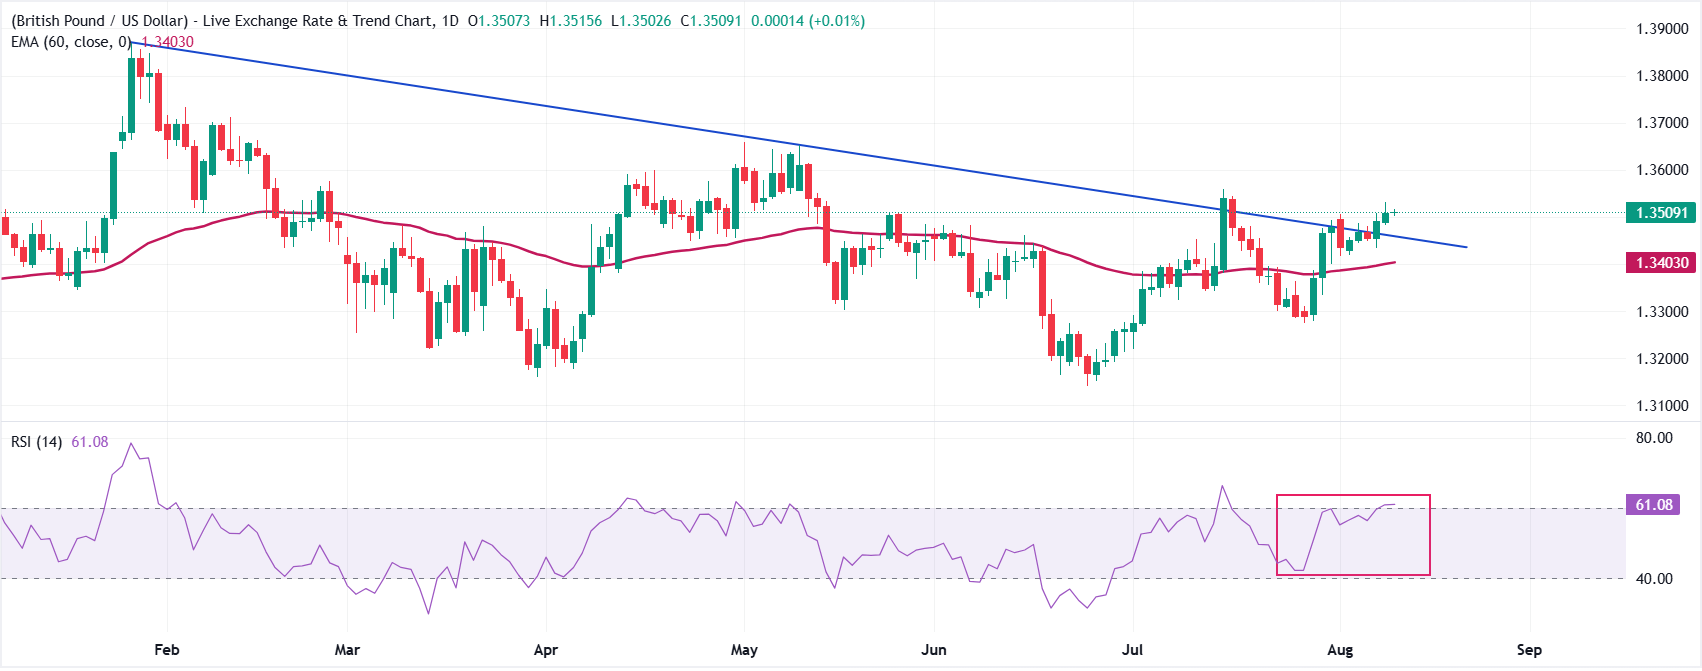
In the daily chart, GBP/USD trades at 1.3500, retaining a bullish near-term tone as spot holds above the 60-day exponential moving average (EMA) at 1.3403 and the broken downward resistance trend line now offering support around 1.3456. The Relative Strength Index (14) at 61.1 leans into positive territory, suggesting buyers remain in control while momentum is not yet stretched into overbought conditions.
On the downside, immediate support emerges at the former trend-line cap turned floor near 1.3456, followed by the 60-day EMA at 1.3403, where a deeper pullback would be expected to attract fresh demand. As long as GBP/USD defends these layers of underlying support, the pair would likely continue to favor the topside, with bulls eyeing further gains above the recent 1.3509 close in the sessions ahead.