S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- The Indian Rupee opens on a negative note against the US Dollar.
- The US Dollar gains as surprisingly strong US NFP numbers boost hawkish Fed bets.
- Renewed Israel-Iran war has prompted oil prices.
The Indian Rupee (INR) starts the week on a negative note against the US Dollar (USD), with the USD/INR pair rising to near 95.30. The pair gains at open as surprisingly upbeat United States (US) Nonfarm Payrolls (NFP) data for May has strengthened the US Dollar, and rising oil prices due to re-escalating conflicts between Iran and Israel have weakened the Indian Rupee.
During the press time, the US Dollar Index (DXY), which tracks the Greenback’s value against six major currencies, holds onto Friday’s gains around 100.00, the highest zone seen in two months.
Upbeat US NFP data prompts hawkish Fed bets
On Friday, the US Bureau of Labor Statistics (BLS) reported surprisingly upbeat official employment data for May. The US NFP arrived significantly higher at 172K against 85K estimates. Meanwhile, the April reading was also revised higher to 179K from 115K. The Unemployment Rate remained steady at 4.3%, as expected. Strong job growth data, compounded with already high inflationary pressures, have resulted in a significant increase in hawkish Federal Reserve (Fed) bets.
The CME FedWatch tool shows that the possibility of the Fed delivering at least one interest rate hike this year has increased to 73.8% from 45.2% seen a week ago.
Oil prices jump on renewed Middle East conflicts
The attacks from Israeli Defense Forces (IDF) in western and central Iran over the weekend, despite US President Donald Trump urging Israeli Prime Minister Benjamin Netanyahu not to retaliate against Iran’s attacks, have renewed fears of an all-out war in the Middle East.
Iran fired ballistic missiles at Israeli military targets over the weekend in retaliation for Israeli aggression in Lebanon.
Rising hostilities in the Middle East have raised concerns over the US-Iran peace deal, prompting fears of a prolonged closure of the Strait of Hormuz, which has resulted in a sharp increase in oil prices. As of writing, the MCX Crude Oil contract expiring on June 18 is up 4.6% to near 9,020.
Currencies from economies, such as India, which rely heavily on oil imports to meet their energy needs, tend to underperform in a high oil price environment.
FIIs continue to remain net sellers in Indian stock market
So far in June, Foreign Institutional Investors (FIIs) have remained net sellers on all trading days, and offloaded their stake worth Rs. 30,814.47 crore. Overseas investors also remained net sellers in May and pared their stake worth Rs. 55,963.33 crore. Foreign investors are dumping their investments in the Indian stock market due to growing concerns over India Inc.’s earnings projections amid higher oil prices.
Technical Analysis: USD/INR attarct bids near 95.00
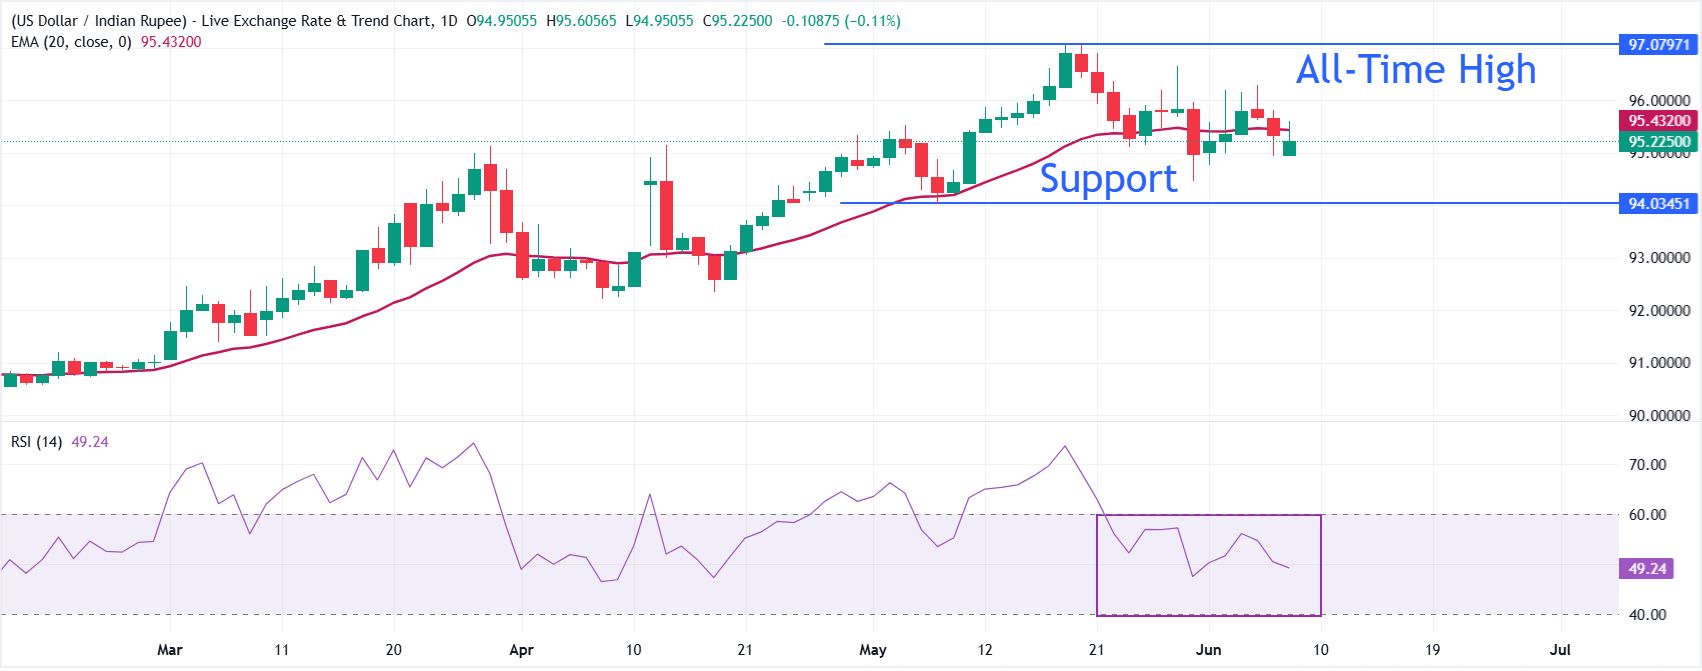
USD/INR trades higher at around 95.30 with a mildly bearish near-term bias, holding just under its 20-day exponential moving average (EMA) at 95.4320. The pair has retreated from recent highs and the loss of traction against this short-term EMA hints that upside momentum is fading, while the Relative Strength Index (RSI) around 49 suggests neutral momentum rather than a clear directional push.
On the downside, immediate focus is on whether sellers can keep the pair capped beneath the 20-day EMA at 95.4320, which now acts as the first area of supply limiting rebounds. A sustained daily close back above this moving average would ease the current pressure and open the door to a further slippage towards the May 7 low around 94.00. Looking up, the pair needs to return above the 20-day EMA to ease downside pressure, and a further rally above the June 4 high at 96.30 would allow it to reclaim the all-time high around 97.10.