S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

NY Fed Survey Signals Inflation Spike in The U.S.

Rising inflation expectations are re-emerging as a key macro risk, driven primarily by energy shocks linked to geopolitical tensions in the Middle East. The data from NY Fed survey reinforces a familiar pattern: short-term expectations react sharply to shocks, while longer-term inflation credibility remains intact – for now.
- One-year inflation expectations in the New York Fed’s March survey rose to 3.4%, vs 3.5% exp. and up from 3% previously and back at the levels seen in December.
- Three-year inflation expectations increased only slightly, to 3.1% from 3.0%. Five-year inflation expectations remained unchanged at 3.0%.
- The overall message is that short-term inflation fears have clearly intensified, but longer-term expectations still look relatively anchored. The main driver of the move was energy.
- Expected gasoline price growth jumped to 9.4% year-on-year, up 5.3 percentage points month-on-month.
- That is the highest reading since March 2022, which underlines how strongly consumers react to energy shocks.
- The link to headline inflation is straightforward, because higher fuel costs feed directly into inflation expectations.
- All of the inflation measures are still running above the Fed’s 2% target.
- That suggests the disinflation process remains incomplete, even if inflation is no longer accelerating across every category.
- Geopolitical tensions and tariffs are now making the path back to target more difficult.
- John Williams kept a relatively calm tone despite the stronger survey readings.
- He said policy is still “well positioned,” which signals that the Fed is not ready to react mechanically to one inflation-related shock.
- He also said headline inflation could run at around 2.75% in 2026, with more visible pressure around the middle of the year.
- The current policy rate remains in the 3.5% to 3.75% range, and the Fed is still pointing to one cut this year.
- From a macro perspective, this looks more like a supply-side inflation shock than a sign of overheating demand.
- The immediate issue is not excessive consumption, but the pass-through from higher energy prices.
- The bigger question is whether this remains temporary or starts to generate second-round effects in broader prices and wages.
- The survey also showed a weaker consumer backdrop. Households became more pessimistic about their current and future financial situation.
- Expectations for unemployment one year ahead rose to the highest level since April 2025, that suggests the labor market is not cracking yet, but sentiment is becoming softer at the margin.
For markets, the report strengthens the higher-for-longer narrative, especially if energy pressure remains elevated. At the same time, stable longer-term inflation expectations reduce the risk of an aggressive hawkish repricing. In other words, the data is uncomfortable for the Fed, but not yet alarming enough to force a policy shift.
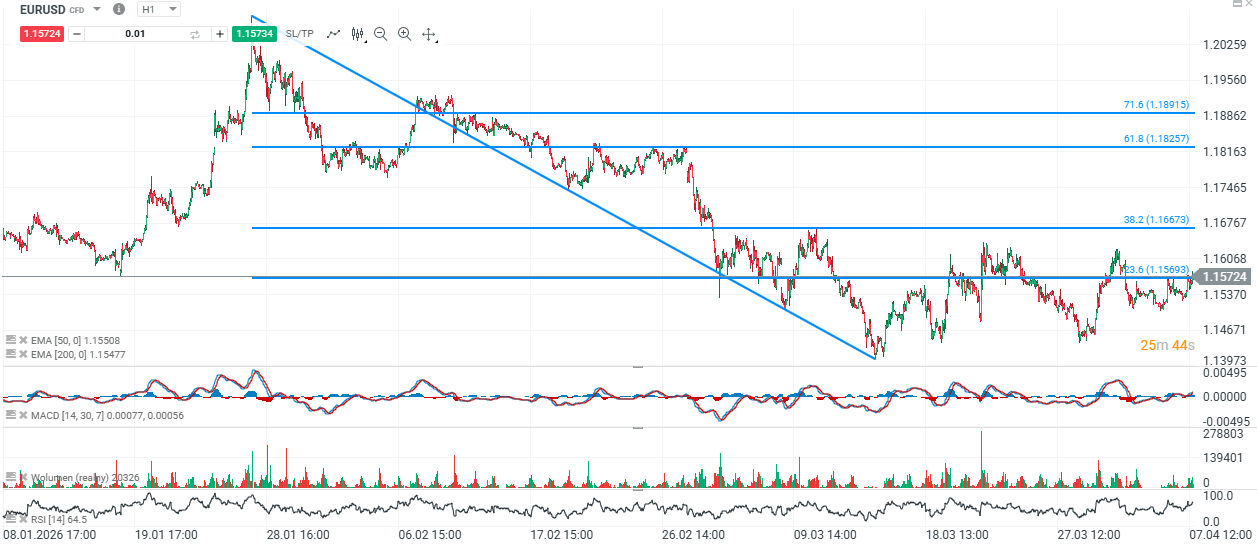
Source: xStation5
The material on this page does not constitute financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other specific needs. All information provided, including opinions, market research, mathematical results and technical analyzes published on the Website or transmitted To you by other means, it is provided for information purposes only and should in no way be construed as an offer or solicitation for a transaction in any financial instrument, nor should the information provided be construed as advice of a legal or financial nature on which any investment decisions you make should be based exclusively To your level of understanding, investment objectives, financial situation, or other specific needs, any decision to act on the information published on the Website or sent to you by other means is entirely at your own risk if you In doubt or unsure about your understanding of a particular product, instrument, service or transaction, you should seek professional or legal advice before trading. Investing in CFDs carries a high level of risk, as they are leveraged products and have small movements Often the market can result in much larger movements in the value of your investment, and this can work against you or in your favor. Please ensure you fully understand the risks involved, taking into account investments objectives and level of experience, before trading and, if necessary, seek independent advice.