S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Risk sentiment has picked up as we move through Thursday. Stock prices have been bolstered by strong earnings reports and a decline in the oil price, which surged to $126 per barrel for Brent crude at one stage. Fears about escalation in the conflict between the US and Iran fueled the initial move higher before the market calmed down. The oil price is lower by 3.5% so far, and Brent is back below $114 per barrel. This has ended a multi-day rally in the oil price, which has soured overall risk sentiment this week, and comes even though the US central command is set to present the President with plans for more military action against Iran. Tech stocks are also in focus, and the market is digesting news from a raft of central bank meetings.
BOE on hold for the long term
The market reaction to the BOE meeting has been muted. The BOE kept rates on hold, as expected, and the vote split was 8-1, with only one member, Huw Pill, in favour of a rate hike. This suggests that there is no hawkish shift at the BOE, and for now, the Bank remains on hold. Added to this, although CPI in the UK rose to 3.3% in March, inflation is expected to fall back to 3% in April before picking up again in the Autumn, according to the BOE. This could be enough to keep the BOE on hold this year, even if there are some calls for rates to rise.
FTSE 100 surges on corporate resilience
This has triggered a paring of UK bets on future rate hikes, and bond yields are also falling. The 2-year Gilt yield is lower by 8bps. As we mentioned in our preview, there was a lot of hawkishness already priced into the UK bond market, and today’s BOE meeting does not warrant higher yields for the UK. The FTSE 100 is also the top performer in the European equity space and is higher by 1.56% today. The gainers in the index include the miners, Standard Chartered and Rolls Royce, which is higher by 6.4%.
Solid earnings from Rolls Royce, Standard Chartered, Unilever and Glencore are boosting demand for the index, as it suggests corporate resilience in the UK to events in the Middle East. Combined with the paring back of UK rate hike bets, this is a good day for UK equities. The case to remain on hold is strong. The BOE stated that there is a real risk of second round inflation effects for price and wage-setting, but balancing this out is a softer labor market and a weaker economy could contain inflationary pressures. The BOE is buying itself time here, even if the direction of rates will depend upon the outcome of the war in Iran and what oil prices do next. The Fed echoed a similar message, and the ECB’s Christine Lagarde is also keeping calm and holding interest rates in a very uncertain economic environment.
Meta gets slammed as Google is new AI poster child
This has been a massive week for event risk, and it seems like sentiment is improving as we move towards the end of the week and the end of the month. However, there is a clear divergence happening in the tech trade. Meta is down nearly 10% today on the back of its earnings report on Wednesday. Although earnings were higher than expected, the company raised capex spending for this year, which has spooked investors.
There are two concerns that investors have with Meta right now: 1, it is not a full stack AI provider and it needs to pay for AI inputs to build AI into its apps, and 2, its latest product from the Superintelligence Labs division is free for users. This means that investors cannot assess its impact on profitability, which is a key metric for investors this earnings season. Added to this, Meta’s share price had risen sharply this month, so there is room for an unwind. At the other end of the AI spectrum, Alphabet’s share price is surging and it is one of the top performers on the S&P 500 so far on Thursday, and is higher by 5%. The market was impressed by its profit growth, 80% in the past year, and there is clear evidence that its AI investments are paying off, cloud revenue rose by 40%.
Nvidia is lower by more than 1% today, partly in response to the news that Google is releasing new TPUS, which will be cheaper and more efficient than Nvidia’s models. These models are designed to accelerate AI, including machine learning and deep learning workloads. Alphabet is fast becoming the poster child of AI, and this could be represented in the share price in the short term. Overall, sentiment has turned around today and is being driven by a falling oil price, calm central bankers and strong earnings results, especially in Europe. Headline risk around the Strait of Hormuz and the war in Iran is still a concern and the oil price remains volatile, especially around communication from the White House.
Chart 1: Brent Crude Futures price, 1-day chart
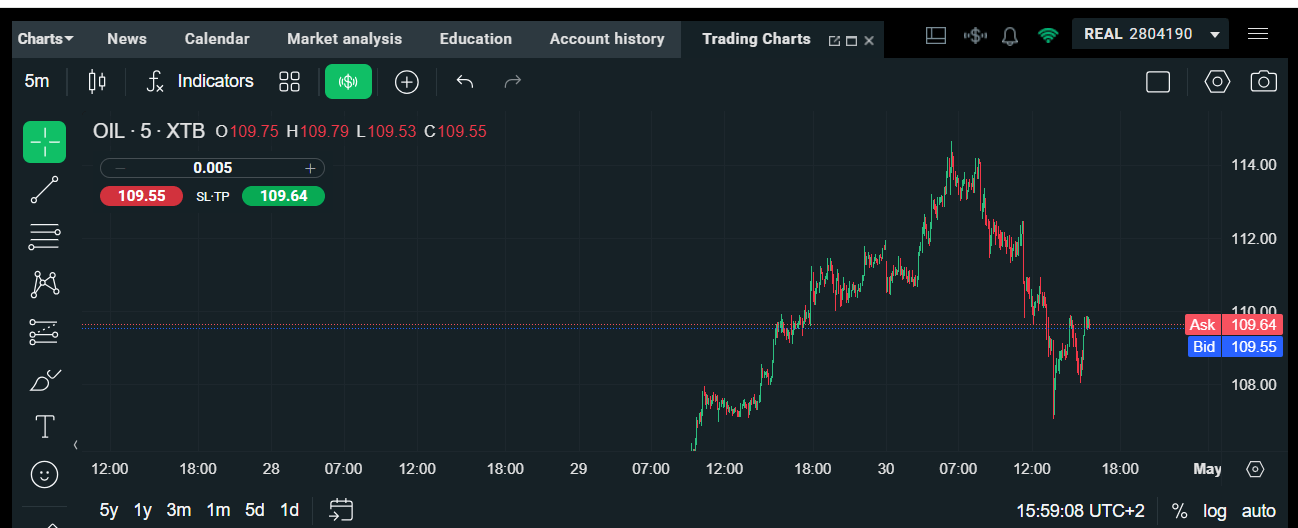
Source : XTB