S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Palo Alto Networks Shares Rally 3.5% as KeyBanc Upgrade Signals Major Cybersecurity Spending Opportunity

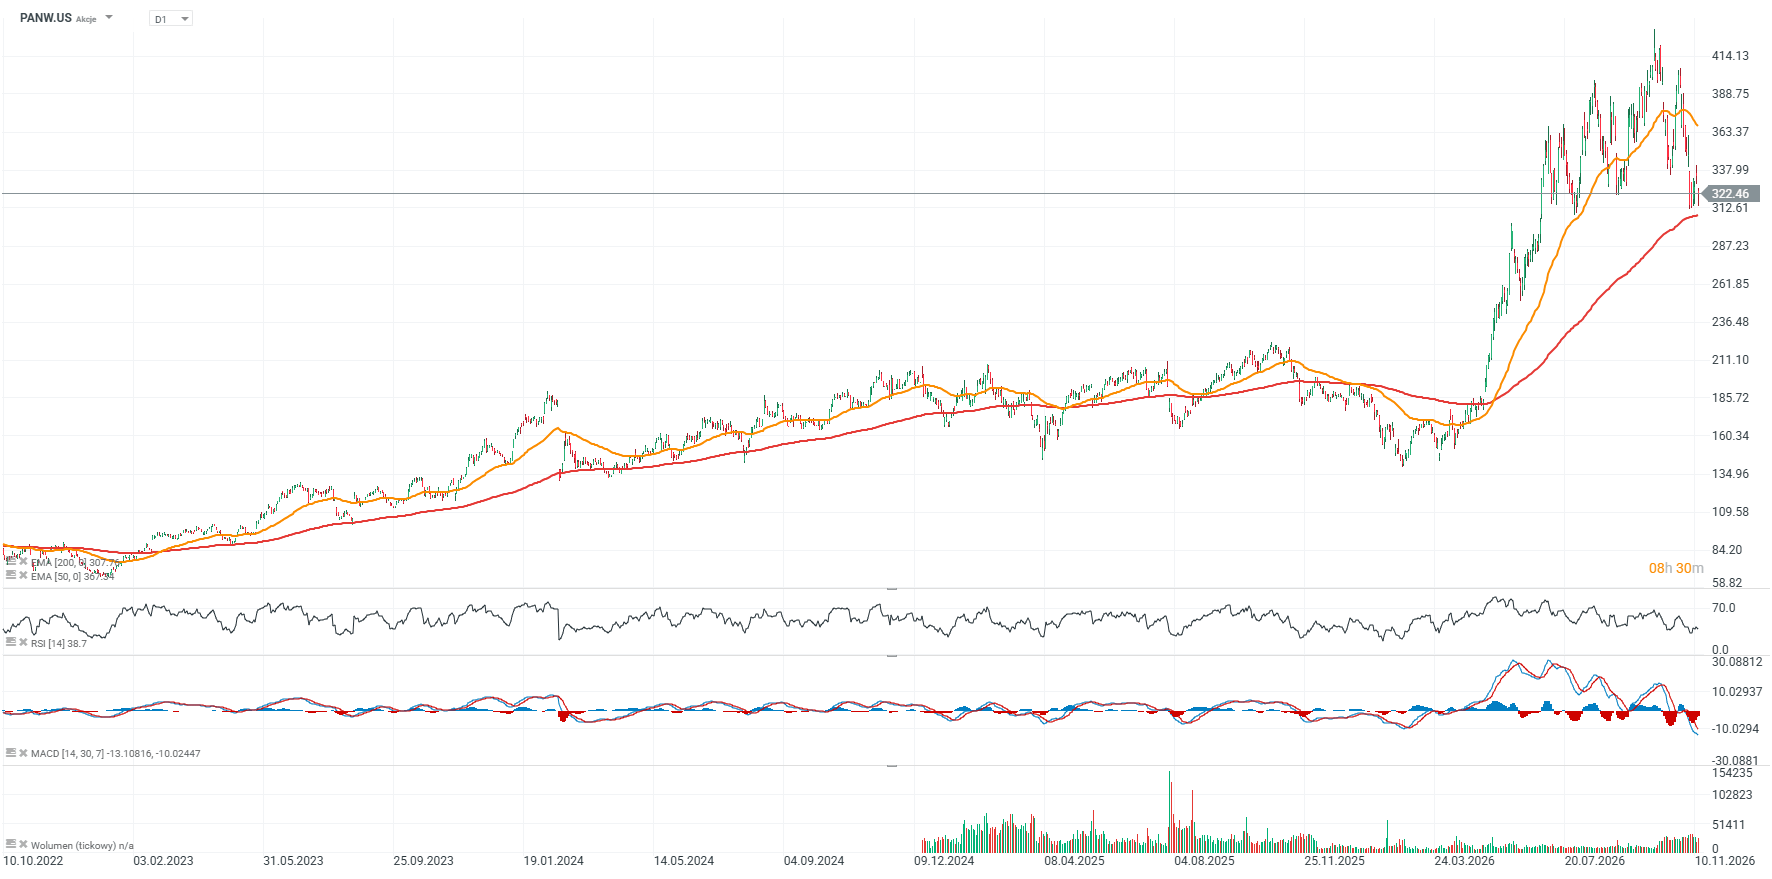
Palo Alto Networks shares advanced nearly 3.5% in pre-market trading after KeyBanc upgraded the cybersecurity company from Sector Weight to Overweight, setting a price target of $380 against the previous closing price of $322.
The upgrade follows a decline of approximately 20% in Palo Alto Networks’ share price over the previous month, which KeyBanc believes could represent an attractive entry point ahead of accelerating cybersecurity expenditure in 2027.
The investment outlook is increasingly supported by the growing complexity of artificial intelligence-related cyber threats, rising enterprise security budgets and a shift towards integrated cybersecurity platforms. Palo Alto Networks and CrowdStrike are identified as potential beneficiaries of industry consolidation as businesses seek to reduce the number of separate security vendors they use.
Investors are now looking towards November 18, when Palo Alto Networks is scheduled to release its fiscal first-quarter 2027 earnings. The results could provide an important indication of whether the company’s growth outlook is matching expectations for a stronger cybersecurity spending cycle.
Palo Alto Networks Market Snapshot
| Market Indicator | Latest Reading |
|---|---|
| Previous closing share price | $322 |
| KeyBanc price target | $380 |
| Implied upside to price target | Approximately 18% |
| Pre-market share movement | +3.5% |
| Recent share-price decline | Approximately 20% over one month |
| KeyBanc rating | Upgraded to Overweight |
| Previous rating | Sector Weight |
| Next earnings announcement | November 18, 2026 |
| Fiscal Q1 2027 revenue guidance | $3.30–$3.31 billion |
| Fiscal Q1 2027 NGS ARR guidance | $9.54–$9.56 billion |
Current Market Performance: KeyBanc Upgrade Sparks Recovery
Palo Alto Networks shares attracted renewed buying interest after KeyBanc upgraded its investment rating, arguing that the recent share-price weakness may have created an opportunity.
The $380 price target represents approximately 18% upside from the November 12 closing price of $322.
The upgrade reflects growing confidence in the cybersecurity industry’s spending outlook, with KeyBanc expecting enterprise security budgets to accelerate significantly during 2027.
The analysts believe the market may be underestimating the potential benefits of increasing cybersecurity expenditure, particularly as businesses face more sophisticated threats associated with artificial intelligence.
However, the anticipated recovery will depend on whether enterprise budgets actually increase as expected and whether Palo Alto Networks can convert stronger industry spending into sustainable revenue and earnings growth.
Cybersecurity Spending: Budgets Could Increase More Than 20% in 2027
One of the central arguments behind KeyBanc’s upgrade is the expected acceleration in cybersecurity spending.
Based on discussions with Chief Information Security Officers (CISOs), the bank believes cybersecurity budgets could increase by more than 20% in 2027.
This would represent a significant acceleration compared with single-digit growth at the beginning of 2026 and an expected increase of approximately 15% by the end of this year.
The anticipated increase reflects the growing importance of protecting corporate infrastructure, sensitive information and increasingly sophisticated digital environments.
Artificial intelligence is adding another dimension to the cybersecurity challenge. As organisations adopt AI applications and autonomous agents, the potential attack surface expands, creating additional requirements for monitoring, threat detection and incident response.
If these spending expectations materialise, cybersecurity providers could benefit from stronger enterprise demand, larger contracts and increased investment in integrated security platforms.
Artificial Intelligence: Why Palo Alto Networks Could Benefit
Artificial intelligence is creating opportunities for cybersecurity companies while simultaneously increasing the complexity of the threats they must defend against.
AI-powered attacks can potentially operate at greater speed and scale, making traditional security arrangements less effective against increasingly sophisticated threats.
Businesses therefore face growing pressure to strengthen protection across multiple areas, including:
- Network security and threat prevention.
- Cloud infrastructure and application protection.
- Identity management and access controls.
- Security operations centres (SOCs).
- Automated threat detection and incident response.
- Protection of enterprise AI systems and autonomous agents.
Palo Alto Networks is positioned to benefit through its integrated cybersecurity platform strategy, known as platformization.
Rather than relying on multiple standalone security products, enterprises are increasingly looking to consolidate their security requirements with a smaller number of comprehensive providers.
This approach could increase customer contract values, strengthen recurring subscription revenue and create higher switching costs as businesses integrate more of their security operations into a single platform.
Platformization: Consolidation Could Strengthen Market Leaders
Industry consolidation is another important factor supporting KeyBanc’s positive outlook.
Enterprises often operate multiple cybersecurity products from different vendors, creating complexity across monitoring, management and threat response.
A move towards integrated platforms could simplify these arrangements and reduce the number of providers organisations need to manage.
Palo Alto Networks and CrowdStrike are identified as potential beneficiaries of this trend.
For Palo Alto Networks, platformization could generate several commercial advantages:
- Higher contract values: Customers purchasing multiple integrated security services may increase their overall spending with the company.
- Recurring subscription growth: Greater adoption of platform-based services could strengthen predictable subscription revenue.
- Higher switching costs: Integrating multiple security functions into one ecosystem may make it more difficult for customers to move to competing providers.
- Cross-selling opportunities: Existing customers could adopt additional network, cloud and security operations products.
- Competitive positioning: Larger proprietary datasets and integrated solutions could create barriers to entry for smaller competitors and emerging AI-focused security providers.
The development of agentic AI could further strengthen this model as organisations increasingly require automated security monitoring and response capabilities.
Financial Performance: Revenue and NGS ARR Demonstrate Growth
Palo Alto Networks’ recent financial performance provides important support for the platformization investment thesis.
For fiscal Q4 2026, the company reported revenue of $3.41 billion, representing year-on-year growth of 34%.
Next-Generation Security annual recurring revenue (NGS ARR) increased by 63% to $9.1 billion.
More than 65% of NGS ARR came from customers using integrated platforms, highlighting the growing contribution of the platformization strategy to the company’s recurring revenue base.
| Financial Indicator | Fiscal Q4 2026 |
|---|---|
| Revenue | $3.41 billion |
| Revenue growth | +34% year-on-year |
| Next-Generation Security ARR | $9.1 billion |
| NGS ARR growth | +63% year-on-year |
| NGS ARR from integrated platform customers | More than 65% |
These figures suggest that platform adoption is already playing an important role in Palo Alto Networks’ growth.
The next challenge will be maintaining this momentum while continuing to expand its customer base and protect profitability.
Channel Partners: Strong Reseller Demand Supports Outlook
KeyBanc also highlighted positive feedback from channel partners.
During the third quarter, all surveyed resellers met or exceeded their sales targets, indicating strong demand across the company’s distribution network.
This is an encouraging signal because channel partners play an important role in introducing cybersecurity solutions to enterprise customers and supporting the expansion of existing relationships.
Strong reseller performance could provide an additional foundation for the company’s fiscal first-quarter results, particularly if demand for integrated cybersecurity platforms continues to accelerate.
However, channel performance alone does not guarantee that the company will exceed financial expectations. Investors will want to see evidence that strong demand is translating into new contracts, recurring revenue growth and improved cash generation.
Fiscal Q1 2027 Earnings: November 18 Is the Next Major Catalyst
Palo Alto Networks is scheduled to report its fiscal first-quarter 2027 results on November 18, making the announcement the next major event for shareholders.
The company’s guidance provides an important benchmark for the market.
| Fiscal Q1 2027 Guidance | Forecast |
|---|---|
| Revenue | $3.30–$3.31 billion |
| NGS ARR | $9.54–$9.56 billion |
Investors will be assessing more than whether the company beats its headline revenue expectations.
The quality of growth will be equally important, particularly the contribution from organic expansion, recurring subscription revenue and the conversion of earnings into cash flow.
Acquisitions can accelerate growth and expand product capabilities, but they also introduce integration challenges and make it more difficult to assess the underlying performance of the company’s core operations.
The November 18 results could therefore provide a clearer indication of whether Palo Alto Networks is delivering the operational performance required to justify KeyBanc’s more optimistic valuation.
Bullish Sentiment
- KeyBanc upgrades the stock: The move from Sector Weight to Overweight provides a positive institutional signal.
- $380 price target: The target implies approximately 18% upside from the November 12 closing price.
- Accelerating cybersecurity budgets: KeyBanc expects industry spending growth to exceed 20% in 2027.
- AI-driven security demand: Increasingly sophisticated cyber threats could encourage enterprises to expand security expenditure.
- Strong financial growth: Fiscal Q4 2026 revenue increased 34% to $3.41 billion.
- Rapid NGS ARR expansion: Next-Generation Security ARR increased 63% to $9.1 billion.
- Platformization opportunity: More than 65% of NGS ARR came from customers using integrated platforms.
- Positive channel feedback: All surveyed resellers met or exceeded their sales targets in the third quarter.
Bearish Sentiment
- Recent share-price weakness: Palo Alto Networks has declined approximately 20% over the previous month.
- Earnings expectations: The upcoming results will need to support the company’s optimistic growth outlook.
- Cybersecurity budget uncertainty: Forecast increases in 2027 spending remain expectations rather than confirmed industry-wide outcomes.
- Competitive pressure: Other cybersecurity providers and emerging AI-focused companies could challenge the company’s market position.
- Acquisition integration risks: Business acquisitions may increase complexity and make organic growth more difficult to assess.
- Profitability and cash flow: Revenue growth must translate into sustainable earnings and cash generation to support a higher valuation.
Palo Alto Networks Share Price Forecast: What Investors Are Watching
KeyBanc’s upgrade has shifted attention towards the potential for a recovery in Palo Alto Networks shares following their recent decline.
The $380 target suggests meaningful upside from the previous close, but the company’s ability to reach that valuation will depend on its upcoming financial performance and the broader cybersecurity spending environment.
The November 18 earnings announcement is likely to be the immediate catalyst.
Investors will be looking for evidence of continued revenue growth, stronger NGS ARR, increasing platform adoption and healthy demand from enterprise customers.
The longer-term opportunity is closely connected to the expansion of AI. As autonomous agents and AI-enabled systems become more widespread, organisations may require increasingly sophisticated security solutions.
Palo Alto Networks could benefit from this structural shift, particularly if its integrated platform strategy enables it to capture a larger share of enterprise cybersecurity budgets.
However, the investment case will depend on execution, competitive positioning and the company’s ability to translate industry growth into sustainable financial returns.
Market Outlook for the Coming Sessions
Palo Alto Networks enters the coming week with renewed investor interest following KeyBanc’s upgrade and its $380 price target.
The broader cybersecurity industry could be approaching a stronger spending cycle, with KeyBanc forecasting budget growth of more than 20% in 2027. The growing complexity of AI-related threats and enterprise demand for integrated security platforms provide a potentially favourable backdrop.
The company’s November 18 earnings announcement will be the immediate test of this outlook.
Strong revenue, NGS ARR growth and positive forward guidance could reinforce confidence in the platformization strategy and support further recovery in the share price.
Conversely, weaker guidance, slowing organic growth or concerns about profitability could undermine the recent optimism.
For now, Palo Alto Networks remains well positioned to benefit from the expanding cybersecurity market, but investors will need confirmation through its upcoming results that the expected industry growth is translating into stronger business performance.
Currency Hedger – Market Contributor
Currency Hedger provides international payments, foreign exchange and currency risk management solutions for businesses operating across global markets.
Disclaimer: This article is provided for informational and educational purposes only. It does not constitute investment advice, financial advice or a recommendation to buy or sell any financial instrument. Individual equities and technology stocks involve substantial risk, and prices can be volatile. Traders and investors should conduct their own research and consider their financial circumstances before making investment decisions.