S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Today’s U.S. Jobs Report: What Investors Expect and How Markets Could Respond

Friday’s US labour market report could determine whether the EUR/USD breaks above the 200-day EMA, or whether the dollar will regain the upper hand for the longer term.
The highlight of the week
July’s non-farm payrolls are undoubtedly the highlight of this week’s agenda. The market is pricing in an increase in employment of 80,000, compared with 57,000 in June, with the unemployment rate remaining unchanged at 4.2 per cent. However, the distribution of forecasts is clearly concentrated in the 70,000–80,000 range, which means that even a reading within the broad range of estimates (10,000–140,000) could come as a surprise if it falls at the lower end of the cluster of expectations. Revisions to the May and June figures will be equally significant – economists at Citigroup and BNP Paribas warn that the JOLTS data and the unusual divergence between manufacturing and total employment suggest a risk of downward revisions, which could overshadow the headline figure itself. MUFG’s macro team goes even further, forecasting as many as 125,000 new jobs, arguing that the leisure and hospitality sector may have been underestimated in June, which increases the likelihood of a positive surprise and an upward revision.
How might the dollar react?
The macroeconomic context is favourable for the dollar even ahead of the release. Rising oil prices due to tensions surrounding the Strait of Hormuz, coupled with a series of solid labour market figures (a fall in lay-off notices, weekly jobless claims below 200,000, and labour productivity in the second quarter at 1.4 per cent q/q against an expected 0.7 per cent) have already bolstered the greenback, and the DXY index has approached the 100 mark. If the NFP comes in at between 125,000 and 150,000 or there are upward revisions, the market may view this as a genuine ‘decent surprise’, which could trigger a sell-off in the interest rate market and strengthen the dollar, although the interest rate market is already close to historic extremes, so an exceptionally large positive shock would be needed for a sustained sell-off. On the other hand, another weak reading without an upward revision would calm the debt market, but the dollar’s rebound would be limited by upcoming Treasury auctions and next week’s CPI figures, which, according to comments from the Fed (Warsh, Kashkari, Logan, Hammack) remains the main benchmark for monetary policy, not the labour market.
What to expect and what might take you by surprise
The base-case scenario assumes a figure close to the consensus (70,000–90,000), with unemployment at 4.2 per cent and annual wage growth at 3.5 per cent. – such a result is likely to keep a September rate rise on the table, but will not trigger a sharp reaction, as the market has already priced this in, and the probability of a Fed move has fallen to 55 per cent from 63 per cent a week earlier, according to CME FedWatch. The biggest potential surprise could be a combination of a weaker headline NFP figure with a simultaneous fall in the unemployment rate to 4.1 per cent (which some economists are predicting). Such a ‘mixed’ reading would make a clear interpretation difficult and could trigger a chaotic, two-way reaction in the EUR/USD pair. Just as important as the job creation figure itself will be month-on-month wage growth (consensus 0.3 per cent), as it is labour cost pressures, rather than the pace of employment, that currently represent the priority for the hawkish members of the FOMC, including Kashkari, Logan and Hammack.
Technical analysis of EUR/USD
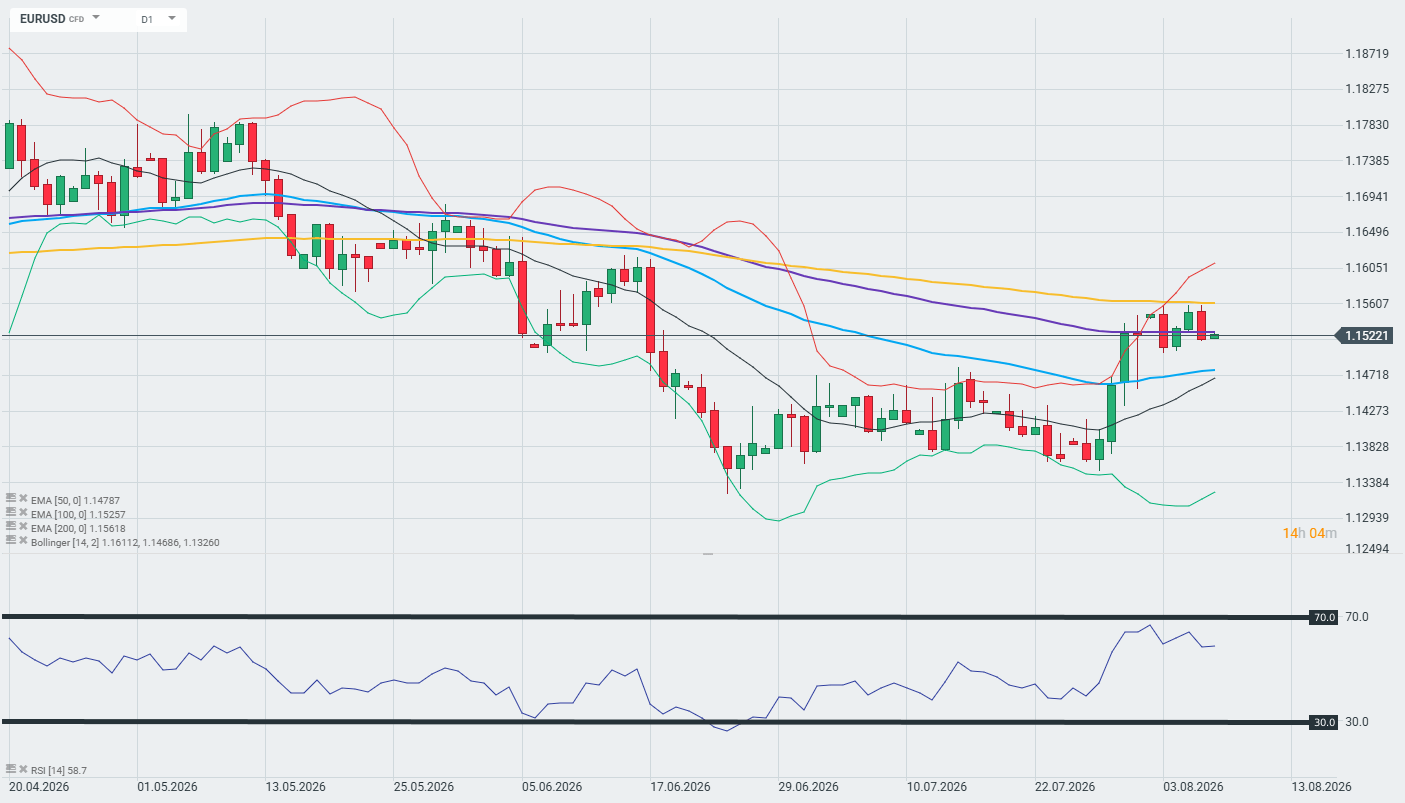
The EURUSD pair is trading just below the 1.1520 level, practically glued to the 100-day EMA (1.15257) and still below the key 200-day EMA at 1.15618, making today’s reading a potential catalyst for a breakout above this barrier following a series of lower highs that has been ongoing since May. The RSI at 58.5 indicates scope for further gains without entering overbought territory, whilst the recent rebound from the late-July lows (below 1.14) suggests that the market is already partially positioning itself for a weaker dollar. A break above the 200-day EMA, coupled with a weaker or downwardly revised NFP, would pave the way for a continuation of the uptrend towards the May highs around 1.17, whereas a strong reading with upward revisions could push the pair back below the 1.14–1.145 support level, invalidating the recent rebound and restoring the dominance of pro-dollar bears. Source: xStation