S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

UoM Consumer Sentiment Index set to ease as inflation, labour market worries loom

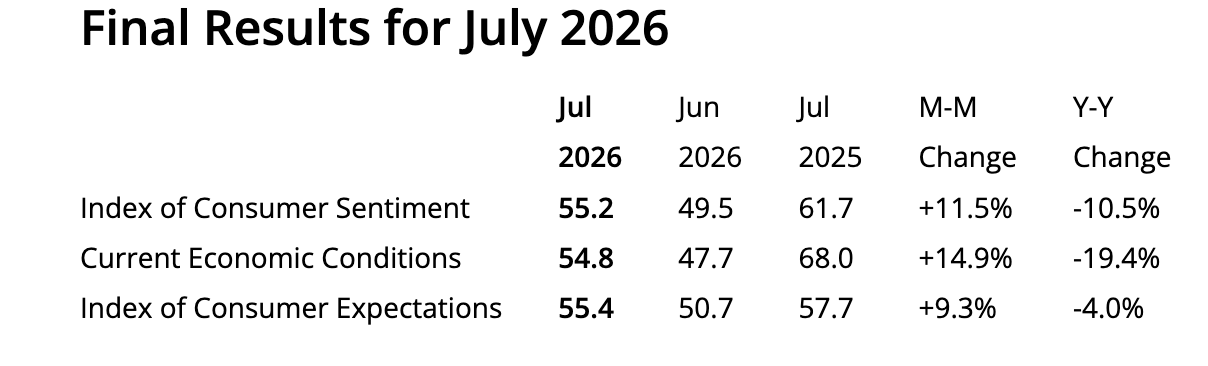
- The Preliminary Michigan Consumer Sentiment Index is expected to ease to 54.5 from 55.2 in July
- US consumers’ optimism has improved to levels close to those seen before the US-Iran war began.
- August’s UoM Consumer Sentiment is unlikely to change the view on the Fed’s monetary policy, which is the main USD driver.
The University of Michigan (UoM) will release the preliminary estimate of August’s Consumer Sentiment Index on Friday. The UoM report, which analyses US consumers’ feelings about their personal finances, business conditions, and purchasing plans, is expected to show a moderate decline, yet remain relatively close to levels in January and February, when concerns about Iran’s war and the economic impact of the energy shock were absent.
US consumers’ confidence is expected to have ticked down to 54.5 in August from 55.2 in July, as measured by the UoM Consumer Sentiment Index. These numbers would highlight fairly resilient sentiment in the face of uncertainty surrounding the Middle East conflict, a deteriorating labour market, and stubbornly high price pressures.
The risk on the US Dollar (USD), thus, is skewed to the downside. A positive surprise on August’s Michigan Consumer Sentiment Index is unlikely to change the prevailing view that the Federal Reserve (Fed) will stand pat on rates in September, while a weak sentiment report might heighten doubts about the momentum of the US economy, pushing Fed rate hikes further back and adding pressure on the Greenback
What to expect from August’s UoM Consumer Sentiment Index report?
Investors will be attentive to Friday’s data to see how US consumers are responding to the Middle East deadlock and the persistently high prices.
US macroeconomic data released earlier this week revealed some moderation in inflation, yet with the headline Consumer Price Index (CPI) growing at a 3.4% year-over-year rate in July, a whole percentage point above the levels seen in January and February, before the Middle East conflict sent Oil prices surging.
If this was not enough, the Nonfarm Payrolls (NFP) report showed that net employment contracted unexpectedly in July, highlighting a sharp deterioration of the labour market, which, sooner or later, is highly likely to dent consumers’ confidence.
July’s University of Michigan report highlighted a broad-based improvement, although, looking from a wider perspective, the overall sentiment remains well below its historical average. The Director of the Survey of Consumers, Johanne Hsu, noted that “sentiment is 11% below a year ago, reflecting a generally somber view of the economy amid five years of elevated inflation and persistently high prices.”
Bearing this in mind, the landscape has not given reasons to contemplate a positive surprise on Friday. Quite the contrary. West Texas Intermediate (WTI) Oil prices are more than 15% above the levels in early July, when the interviews for last month’s report took place, and the situation in the Middle East remains stalled, pushing energy prices and overall inflation higher.
Inflation expectations for the year ahead eased in July to 4.2% from 4.6% in June, but recent developments might have prompted some recovery in August, adding pressure on the overall sentiment.
When will the UoM Consumer Sentiment Index be released, and how could it affect the US Dollar?
The University of Michigan will release its Consumer Sentiment Index, together with the Consumer Inflation Expectations survey, on Friday at 14:00 GMT. The market consensus hints at a moderate pullback from July’s reading, although showing levels not far from the 2026 peak.
The US Dollar remains weighed by dwindling hopes of Fed rate hikes, although the cautious market mood, amid growing uncertainty about the fate of the US-Iran peace process, has kept the safe-haven Greenback buoyed this week.
The USD Index (DXY), which measures the value of the US Dollar against a basket of six major currency peers, has been showing a mild upside bias over the last few days, after finding some support at the 99.45 area. Bulls, however, have been unable to find acceptance above the 100.00 psychological level at the time of writing.
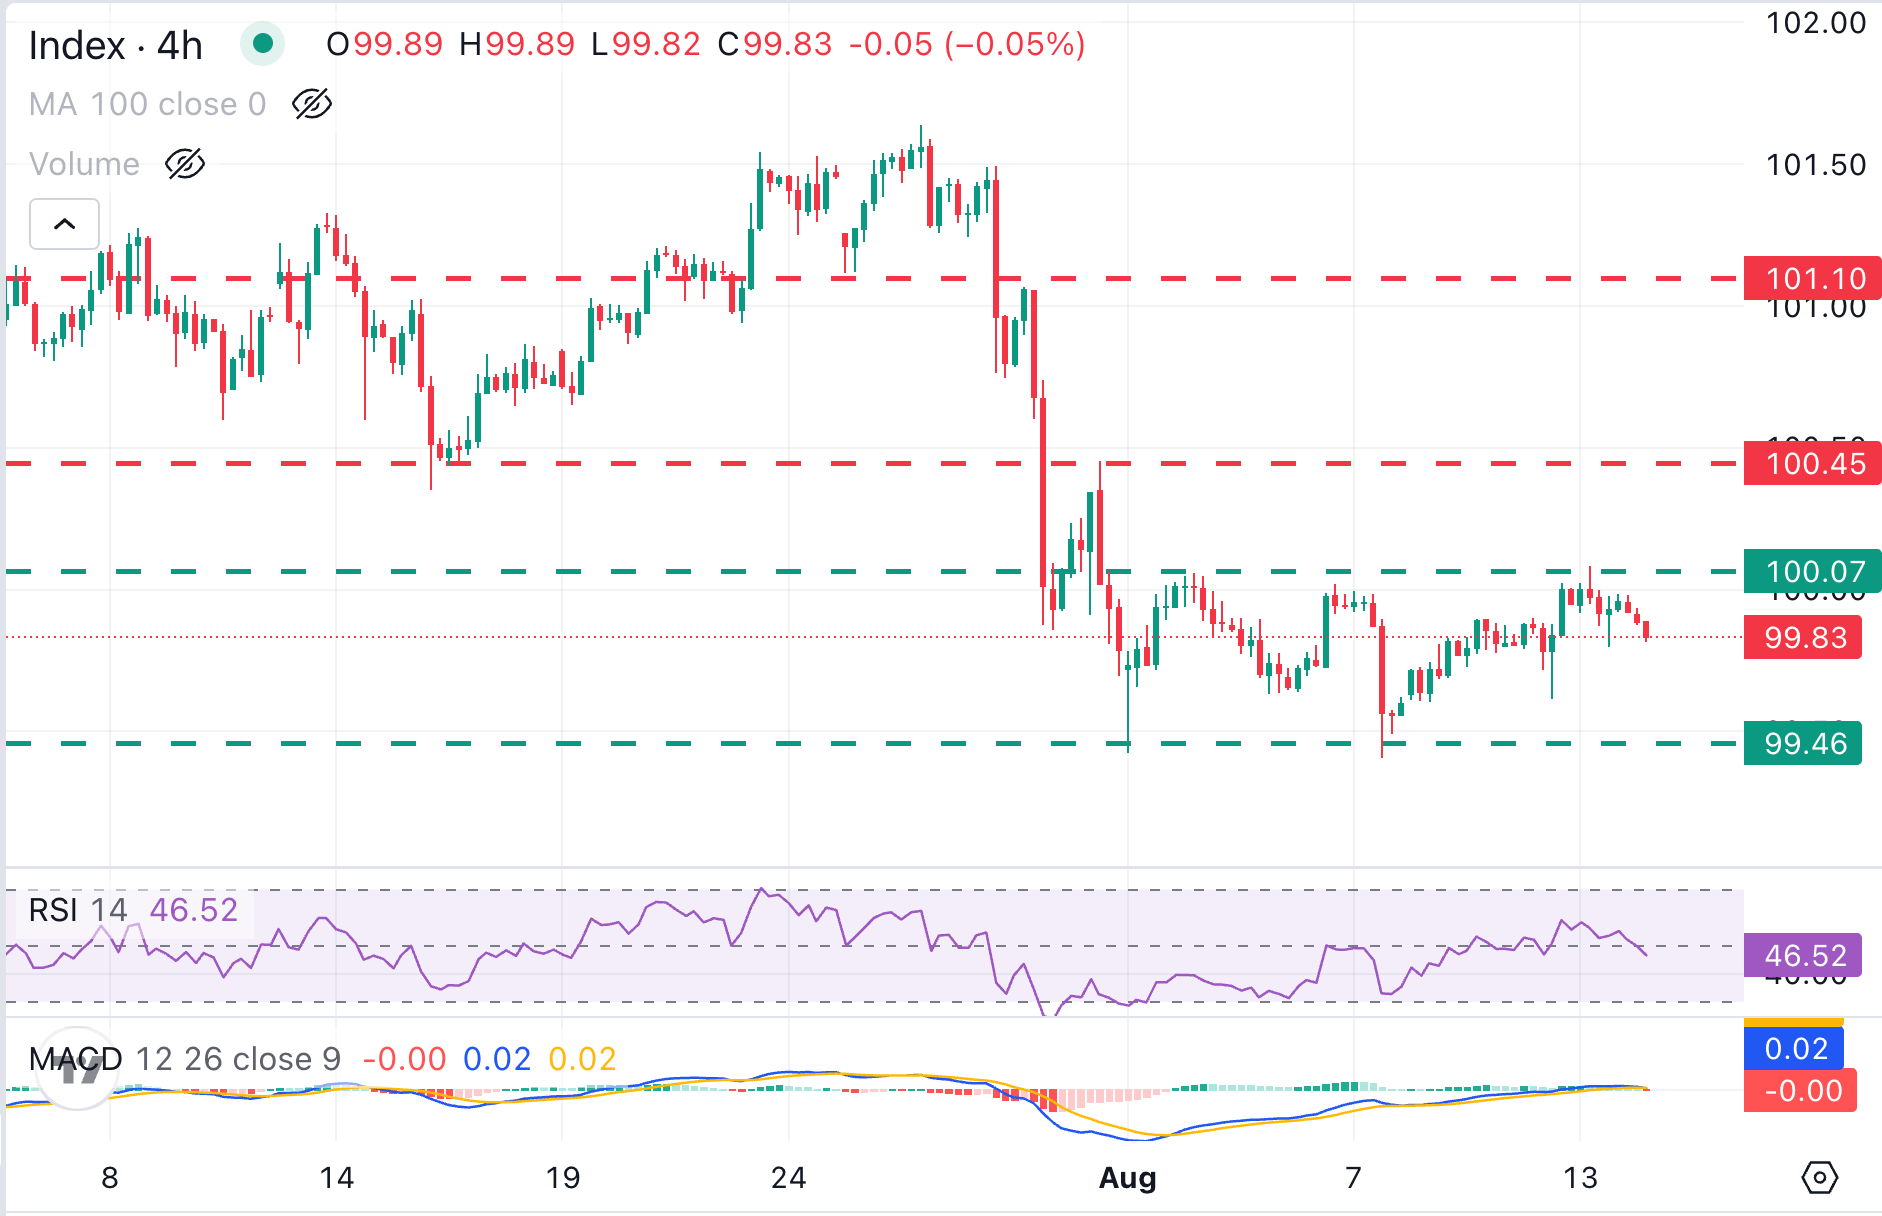
The 4-hour chart highlights a neutral-to-bearish near-term bias, with the Relative Strength Index (14) drifting below the 50 midline and the Moving Average Convergence Divergence (MACD) histogram marginally in negative territory. This hints at a fading bullish undertone rather than a bearish reversal.
Bulls would need a clear break of the 100.00 resistance zone to shift the focus towards a previous support area near 100.45, which capped bulls on July 31, ahead of the July 30 high, a few pips above 101.00. On the downside, Wednesday’s low in the 99.60 region is likely to test bears’ confidence, although the key support area is the mentioned 99.40, the bottom of the last two months’ trading range.