S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Arista Networks shares jump 6% after earnings. Revenue growth hits its highest level since IPO

Arista Networks (ANET.US), one of the leading providers of networking infrastructure for data centers and artificial intelligence, reported third-quarter 2026 results that significantly exceeded Wall Street expectations. Revenue surged 58.5% year-over-year to $3.66 billion, marking an exceptionally strong growth rate for the company since its 2014 IPO. Adjusted earnings per share reached $1.20, compared with expectations of approximately $1.10, confirming robust demand for networking solutions deployed by the world’s largest cloud operators. Importantly, Arista maintained exceptionally high profitability despite the growing contribution of major infrastructure customers to its revenue. The outlook for the fourth quarter appears even more encouraging, suggesting that the rapid expansion of AI infrastructure continues to translate into substantial orders and strong financial performance.
Arista Networks Q3 2026: Key Financial Results
- Revenue reached $3.66 billion, compared with expectations of $3.33 billion, representing 58.5% year-over-year growth and a result almost 10% above consensus.
- Adjusted earnings per share (non-GAAP EPS) reached $1.20, compared with expectations of $1.08, beating estimates by more than 11%.
- Adjusted operating income totaled $1.80 billion, exceeding expectations of $1.62 billion.
- Non-GAAP gross margin reached 64%, above the 62.9% consensus estimate, although it declined by 1.2 percentage points year-over-year.
- Non-GAAP operating margin reached 49.1%, improving by 0.5 percentage points year-over-year and demonstrating the company’s strong cost efficiency.
Arista Networks Q4 2026 Guidance
- Revenue is expected to reach between $3.9 billion and $4.0 billion, significantly above analysts’ consensus estimate of $3.6 billion.
- Adjusted EPS is projected to range from $1.26 to $1.30, compared with market expectations of approximately $1.15.
- Non-GAAP operating margin is expected to remain between 48% and 49%, suggesting that the company can maintain exceptionally high profitability despite continued expansion.
- The midpoint of revenue guidance, at $3.95 billion, implies potential sales growth of approximately 7.9% quarter-over-quarter and nearly 59% year-over-year.
Virtually the only weak spot in the report was the fact that total deferred revenue (payments received or due for products and services that have not yet been recognized as revenue) declined by $26 million quarter-over-quarter to $6.84 billion . This marked the first quarterly decline since June 2023, following 12 consecutive quarters of increases. Nevertheless, a decrease in deferred revenue does not necessarily signal weaker future sales. It may reflect, among other factors, the pace of contract execution and the recognition of previously deferred revenue.
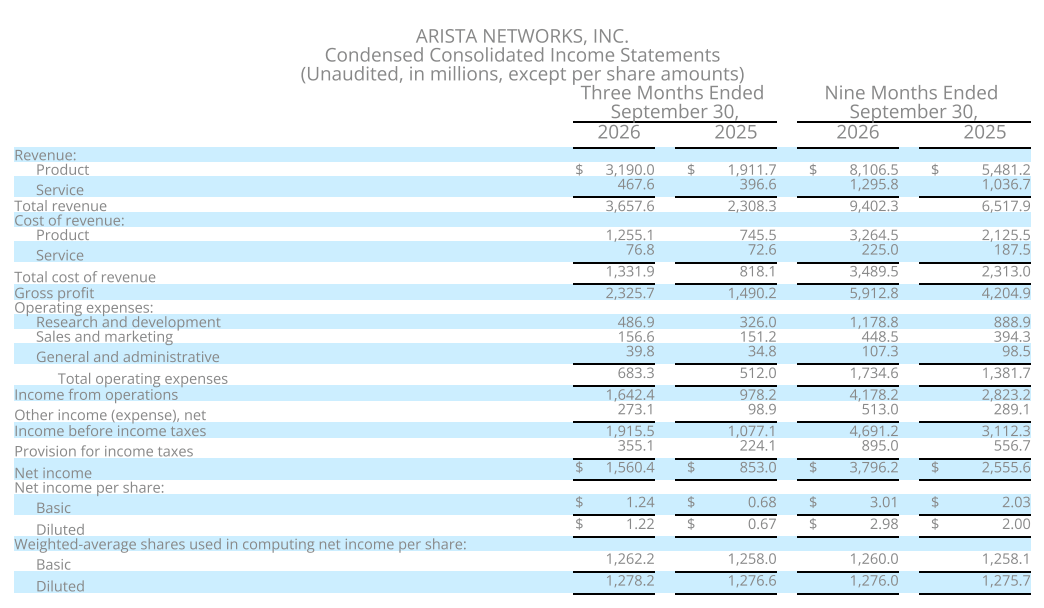
Source: Arista Networks Income Statement
Arista Networks Benefits From the AI Boom, but Its Competitive Advantage Extends Beyond Hardware
Arista Networks is one of the major beneficiaries of growing investment in artificial intelligence computing infrastructure, although unlike Nvidia or AMD, its business does not focus on manufacturing AI accelerators. Instead, the company supplies advanced network switches, software, and technologies that enable high-speed data transmission between servers and thousands of GPUs used to train and run AI models. As computing clusters grow larger, network bandwidth, latency, and reliability become increasingly critical. Consequently, the expansion of artificial intelligence is driving demand not only for computing power but also for Arista’s products. An important component of the company’s competitive advantage is its Extensible Operating System (EOS), which allows customers to manage complex networking environments through a unified software architecture. For the largest data center operators, this carries significant economic value, as automation, network stability, and reduced downtime directly affect the cost of operating computing infrastructure. Arista is therefore more than just a networking hardware supplier; it also provides technology that can improve the efficiency of capital investments made by cloud operators. Over the longer term, this combination of hardware and software could represent a significant source of competitive differentiation when competing for major AI infrastructure contracts.
New Ethernet Architecture Could Expand Arista’s Share of AI Data Center Spending
One of Arista’s most important strategic priorities is expanding the use of Ethernet technology within the most demanding artificial intelligence systems. In October, the company introduced its Etherlink SU-144 architecture, enabling up to 144 accelerators to be connected within a single communication domain and allowing scaling to 1,024 XPU units through inter-rack connections. The solution was developed for scale-up environments, where extremely fast communication between processors is essential for efficient AI workloads. Arista is developing this technology in collaboration with several major technology partners, including AMD, Arm, Broadcom, Meta, Microsoft, and Qualcomm. The strategic importance of this initiative lies in expanding Arista’s addressable market beyond traditional server-to-server networking into connectivity within large accelerator domains. Open Ethernet could provide an alternative to more proprietary networking architectures, giving customers greater flexibility in selecting processors, switches, and software. In practice, this increases Arista’s potential role in developing the next generation of data centers, although it does not yet guarantee that the company will capture a significant share of this emerging market segment. For investors, the key factors will be the pace of commercialization and the ability of these solutions to compete on latency, performance, and total infrastructure costs.
Margins Highlight the Strength of Arista’s Business Model. Can Rapid Growth Remain Profitable?
Third-quarter results demonstrate Arista’s ability to combine exceptionally strong revenue growth with profitability levels typically associated with the most efficient technology companies. A non-GAAP operating margin of 49.1% means that nearly half of the company’s revenue translates into adjusted operating profit before financial income, expenses, and taxes. At the same time, gross margin declined by 1.2 percentage points year-over-year, highlighting potential pressures from product mix, component pricing, and commercial terms negotiated with the largest customers. Nevertheless, the improvement in operating margin despite lower gross margin suggests that increasing scale is allowing Arista to spread operating expenses more efficiently across a larger revenue base. For Arista, the relationship between revenue growth and changes in gross margin is particularly important. Major cloud operators can generate enormous orders, but their substantial negotiating power means that an increasing contribution to revenue does not necessarily translate into higher profitability. Another relevant factor is the cost of advanced networking chips, memory, and optical components, whose availability affects both order fulfillment and product economics. Maintaining high margins in the coming quarters will therefore be just as important a test of Arista’s growth quality as its ability to continue exceeding revenue expectations.
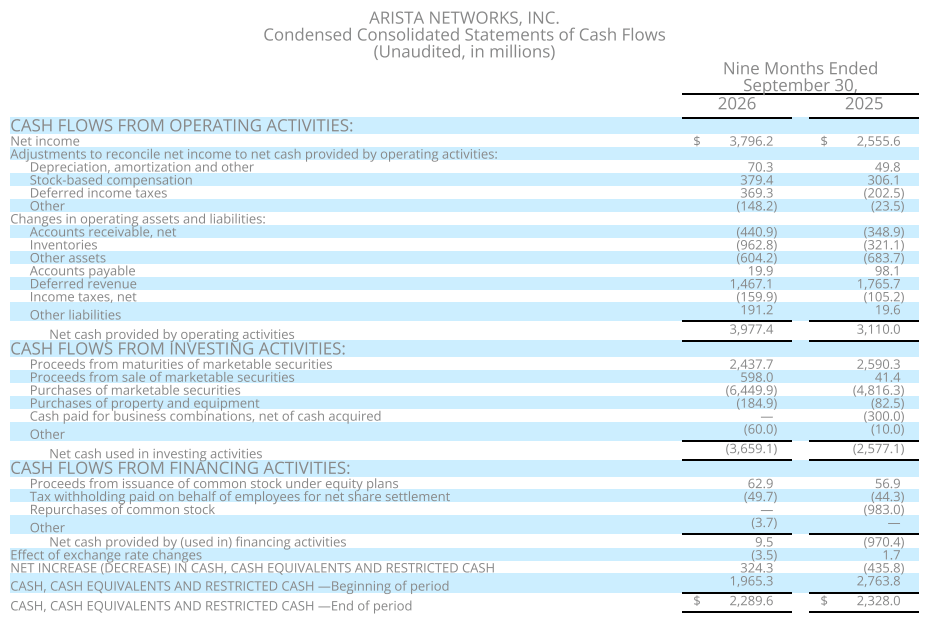
Source: Arista Network Condensed Consolidated Statements of Cash Flows
Guidance Points to Continued Business Acceleration. What Does It Mean for ANET’s Valuation?
Fourth-quarter revenue guidance of approximately $4 billion suggests that management expects the company to maintain exceptionally strong business momentum through the end of the year. Based on results from the first three quarters and the current guidance range for the final quarter, Arista’s full-year revenue could reach approximately $13.3 billion to $13.4 billion. Such an outcome would significantly exceed management’s earlier assumptions and confirm the scale of growing demand for advanced networking infrastructure. However, this figure represents a mechanical calculation based on reported quarterly results and Q4 guidance, rather than a separate official full-year forecast. From a valuation perspective, the central question is no longer simply whether Arista can continue expanding its revenue, but how long it can sustain such exceptional growth in both sales and earnings. The world’s largest technology companies are investing enormous amounts in AI data centers, but the pace of this spending remains dependent on financing availability, energy infrastructure, and expected returns on artificial intelligence investments. Additional risks for Arista include customer concentration among major cloud operators, competition from other networking suppliers, and the potential postponement of large infrastructure projects. The third-quarter results strengthen the fundamental investment case for the company, but future stock returns will also depend on valuation, market expectations, and Arista’s ability to maintain its technological advantage.
Arista Joins the S&P 100. From a Niche Networking Supplier to a Strategic Infrastructure Provider
Arista Networks’ inclusion in the S&P 100 index in 2026 marks another milestone in the company’s evolution from a specialized networking hardware supplier into one of America’s important technology companies. Its market position reflects not only its exposure to artificial intelligence investment but also its presence in traditional data centers, enterprise networking, and cloud infrastructure. The diversification of product applications may partially reduce dependence on any single market segment, although major hyperscaler projects remain an important source of order volatility. Membership in the S&P 100 increases the company’s visibility among institutional investors, but it does not, by itself, guarantee future share price appreciation. CEO Jayshree Ullal described the third quarter as exceptional in terms of revenue growth, while also emphasizing record profitability. CFO Chantelle Breithaupt highlighted record growth in sales, net income, and earnings per share. Overall, the report portrays a company that is not only benefiting from the global AI expansion but is also playing an increasingly important role in developing the technological foundations supporting that growth. The key test for 2027 will be whether Arista can translate its current technological advantages into further revenue growth while maintaining high profitability and effective cost control.
Arista Networks (ANET.US) Stock Chart, D1 Timeframe
Arista shares closed Tuesday’s session below the 200-day exponential moving average (EMA200, red line), having declined approximately 25% from their all-time highs. Following the earnings release, the stock is already trading near $180 per share, suggesting a potential opening above a key resistance level in tomorrow’s session. In recent years, Arista shares have repeatedly fallen below the EMA200, but each time they recovered relatively quickly and resumed their upward trend. The RSI indicator is set to rebound from near-oversold levels, while the MACD could experience a sharp bullish reversal.
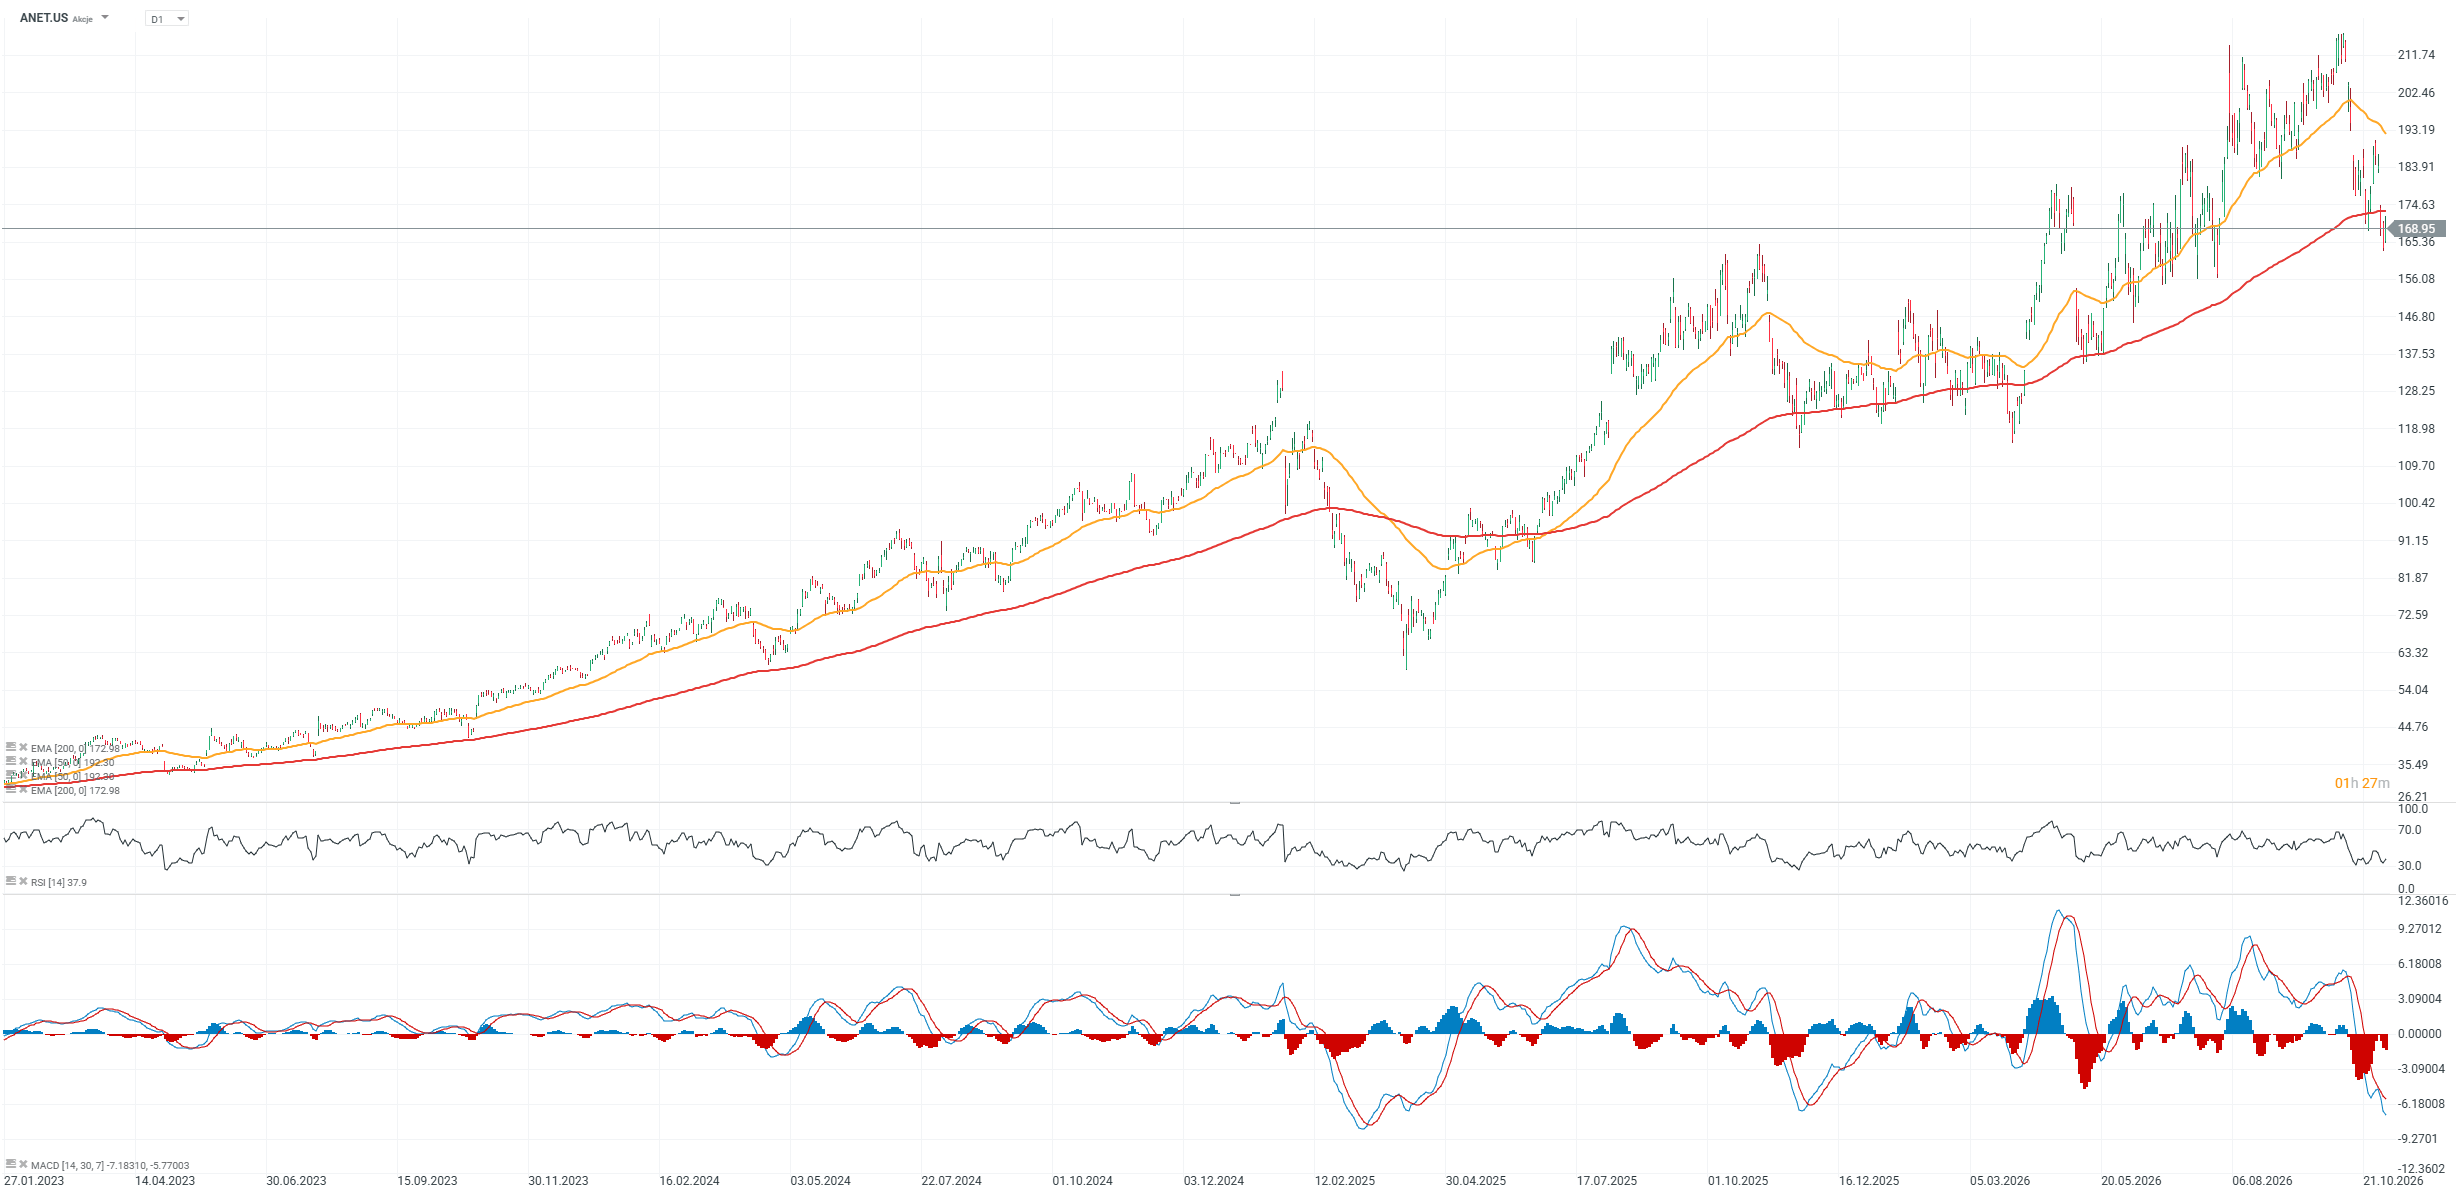
Source: xStation5