S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Cocoa Prices Plunge Over 3% as Weak North American Demand and Rising Inventories Hit Market Sentiment

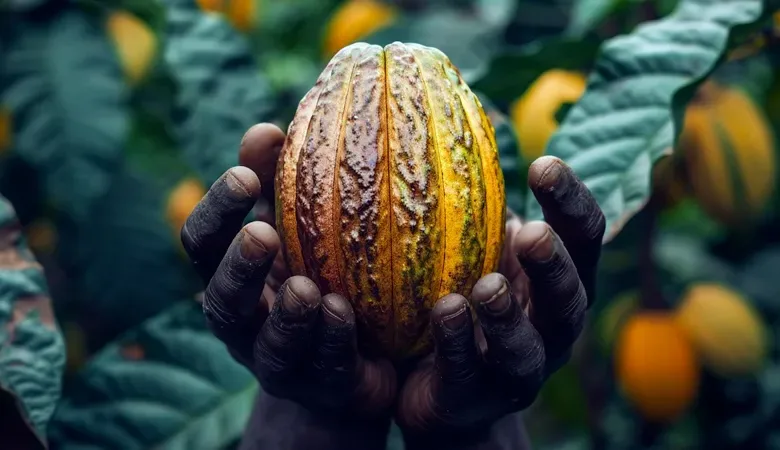
Cocoa futures face a cautious start to the new week after both New York and London contracts fell more than 3% on Friday. December New York cocoa declined 3.19%, while December London cocoa dropped 3.23%, following unexpectedly weak North American cocoa grindings and a continued build-up in ICE inventories.
The sell-off contrasts with stronger-than-expected demand figures from Asia and Europe, highlighting a market where regional consumption trends are diverging. Looking ahead, the balance between rising available stocks and the risk of smaller West African harvests will determine whether prices extend their correction or recover.
The immediate outlook is bearish, but weather-related supply risks remain a potential source of medium-term support.
Market Snapshot
| Indicator | Latest Reported Data | Market Implication |
|---|---|---|
| December New York cocoa | Down 3.19% Friday | Strong selling pressure |
| December London cocoa | Down 3.23% Friday | Broad-based weakness |
| North American Q3 grindings | 109,978 MT, down 2.5% year-on-year | Bearish demand signal |
| Asian Q3 grindings | 233,767 MT, up 29% year-on-year | Strong demand support |
| European Q3 grindings | 348,215 MT, up 3.2% year-on-year | Better-than-expected demand |
| ICE cocoa inventories | 3,593,964 bags | Highest in 2.25 years |
| Ivory Coast 2026/27 crop estimate | Around 1.8 MMT | Potential supply reduction |
| Ghana 2026/27 crop estimate | 450,000–650,000 MT across cited forecasts | Production uncertainty |
| Ivory Coast shipments | 2.18 MMT, up 19.8% year-on-year | Evidence of strong recent supply flows |
Figures reflect the supplied market report. Production estimates differ between sources and remain subject to revision.
Monday Cocoa Outlook: Demand Disappointment Sets the Tone
Cocoa enters the new week under pressure after North American Q3 grindings unexpectedly declined 2.5% year-on-year to 109,978 MT. The result fell short of expectations for no change and raised fresh questions about demand resilience at elevated cocoa prices.
The decline was accompanied by rising ICE inventories, which reached 3,593,964 bags on Friday. Increasing exchange stocks suggest greater availability within the deliverable market and provide another reason for traders to reassess the recent price rally.
However, the demand picture is not uniformly weak. Asian grindings rose a record 29%, while European grindings increased 3.2%, both exceeding expectations.
For Monday, the key question is whether traders continue to focus on weaker North American demand and rising inventories or begin to price in the risk of reduced West African production later in the season.
North American Cocoa Demand Weakens
The National Confectioners Association reported that North American cocoa grindings fell 2.5% year-on-year in the third quarter to 109,978 MT.
Grindings measure the volume of cocoa beans processed and are widely watched as an indicator of demand from chocolate manufacturers. The unexpected decline is significant because it suggests that higher cocoa costs may be affecting purchasing or processing activity.
Cargill, the world’s second-largest cocoa processor, also reported mark-to-market losses on cocoa for the quarter ended August 31. This suggests that the company faced difficulties managing the financial impact of high cocoa costs and passing those costs through to customers.
If elevated prices continue to pressure manufacturers and consumers, cocoa demand could remain vulnerable. Traders will be watching future grindings data for evidence that the weakness is spreading beyond North America.
Asia and Europe Provide a Counterweight
Demand data from Asia and Europe were substantially stronger than expected.
Asian Q3 cocoa grindings rose 29% year-on-year to 233,767 MT, a record increase according to the supplied report. European grindings climbed 3.2% to 348,215 MT, despite expectations for a 3.9% decline.
These figures challenge the argument that high cocoa prices are weakening consumption everywhere. Regional differences may reflect varying demand conditions, purchasing cycles and processing activity.
The next question is whether these gains can persist. Strong Asian and European processing would help offset North American weakness, but it may not be enough to absorb rising stocks if supply continues to exceed demand elsewhere.
ICE Inventories: Rising Stocks Remain a Bearish Signal
ICE cocoa inventories climbed to 3,593,964 bags on Friday, the highest level in 2.25 years.
The increase is an important near-term headwind because rising exchange stocks can indicate improved availability and reduce concerns about immediate shortages. It also gives the market a more tangible supply measure against which to assess weather-related risks and production forecasts.
However, exchange inventories do not capture the entire global cocoa balance. Their significance depends on the location, quality and availability of stocks, as well as the broader pace of production and consumption.
For Monday, further inventory increases could reinforce bearish sentiment. Evidence that stocks are stabilising or that physical supply is becoming harder to source could help prices recover.
Ivory Coast: Heavy Rain Disrupts Harvesting and Deliveries
The Ivory Coast remains central to the supply outlook as its main harvest gets underway.
Heavy rainfall has reportedly restricted access to cocoa farms, damaged bridges and cut off roads, slowing harvesting and deliveries to ports. These disruptions helped cocoa prices reach recent highs before Friday’s reversal.
The weather creates two opposing effects. In the short term, delayed harvesting and shipments can reduce the volume of beans reaching the market, supporting prices. Over a longer period, excessive moisture and poor growing conditions can increase disease risks and damage crop quality.
Early assessments of the 2026/27 Ivory Coast crop point to weaker pod development and below-average cherelle formation. The supplied estimates put production at approximately 1.8 MMT, down 18% from around 2.2 MMT in 2025/26.
If confirmed, a reduction of this scale could tighten the market later in the season. However, early crop estimates are uncertain, and actual production will depend on weather, disease pressure and harvesting conditions over the coming months.
Ghana: Lower Production Forecasts Add Medium-Term Risk
Ghana, the world’s second-largest cocoa producer, also faces concerns about the next crop.
COCOBOD has projected that 2026/27 production could fall to 450,000–550,000 MT, citing swollen shoot disease, ageing farms and the risk of adverse weather. A separate field survey estimated production at 650,000 MT, down 13% from 750,000 MT in 2025/26.
The wide range underlines the uncertainty surrounding Ghana’s supply outlook. Nevertheless, even the higher estimate points to a smaller crop than the previous season.
Current-season production has been stronger: Ghana’s cocoa board reported 750,000 MT harvested for 2025/26 by August 26, up 25.6% from 597,000 MT in 2024/25.
This contrast is important. Recent production strength can support near-term availability, while the outlook for the next crop raises the risk of tighter supply later in the marketing year.
El Niño: A Potential Threat to West African Cocoa Yields
The US Climate Prediction Center has warned that the developing El Niño pattern could become one of the strongest in more than 75 years, according to the supplied report.
El Niño can bring warmer and drier conditions to parts of West Africa, potentially reducing soil moisture, stressing cocoa trees and limiting yields. Combined with excessive rainfall, disease and poor pod development, changing weather patterns could make production less predictable.
The impact is not guaranteed. Regional rainfall outcomes vary, and the eventual effect on cocoa production will depend on the timing and severity of conditions during key stages of crop development.
For traders, the important indicators will be updated crop assessments, rainfall patterns, disease reports and the pace of deliveries from Ivory Coast and Ghana.
Bullish Sentiment: Factors That Could Support Cocoa Prices
- Smaller West African crops: Early estimates point to lower 2026/27 production in Ivory Coast and Ghana.
- El Niño-related weather risks: Adverse rainfall and temperature patterns could reduce yields and damage crop quality.
- Harvesting disruptions: Heavy rainfall and damaged transport infrastructure could delay deliveries from Ivory Coast.
- Strong Asian demand: Record Q3 grindings suggest consumption and processing remain resilient in a major market.
- Stronger European grindings: Better-than-expected processing could offset part of the North American decline.
- Disease pressure: Black pod disease and swollen shoot disease could further constrain production if conditions deteriorate.
Bearish Sentiment: Risks of Further Price Weakness
- Weak North American demand: The 2.5% annual decline in Q3 grindings raises concerns about high-price demand destruction.
- Rising ICE inventories: Stocks at a 2.25-year high indicate greater exchange inventory availability.
- Strong recent Ivory Coast shipments: Reported shipments of 2.18 MMT were up 19.8% year-on-year.
- Higher recent Ivory Coast output: The regulator reported 2.06 MMT harvested in the June 2025–June 2026 period, up 30% year-on-year.
- Speculative profit-taking: The recent rally created scope for selling when demand data disappointed.
- Lower processing margins: If manufacturers struggle to pass high cocoa costs to consumers, demand and purchasing activity could weaken further.
Cocoa Price Forecast: What Traders Should Watch on Monday
The near-term bias is bearish following Friday’s sharp decline, but the market remains exposed to supply risks that could limit further losses.
Three scenarios are worth watching:
- Bearish scenario: Prices remain under pressure if traders focus on weak North American grindings, rising inventories and evidence of strong available supply.
- Bullish scenario: Cocoa recovers if West African weather disrupts deliveries further or new crop assessments reinforce expectations of smaller harvests.
- Neutral scenario: Prices consolidate as stronger Asian and European demand offsets weaker North American processing and rising stocks.
The most important signals will be whether ICE inventories continue increasing, whether Ivory Coast deliveries recover as weather improves and whether the market receives stronger evidence of lower 2026/27 production.
No precise support or resistance levels can be established from the supplied data alone.
Cocoa Market Outlook for the Coming Sessions
Cocoa faces a difficult near-term balance. Friday’s sell-off reflects a clear demand disappointment in North America and rising exchange inventories, both of which challenge the recent rally.
However, strong Asian and European grindings show that demand remains uneven rather than universally weak. Meanwhile, the outlook for the next West African crop is vulnerable to weather disruption, disease and lower pod development.
The coming sessions will test whether bearish inventory and demand signals dominate or whether concerns about future production regain control. Until crop forecasts and physical supply trends become clearer, sharp price swings remain possible.
Currency Hedger View
Cocoa processors, chocolate manufacturers, exporters and importers face both commodity-price risk and foreign-exchange exposure. Changes in cocoa prices can alter purchasing costs, while exchange-rate movements affect the final value of international payments and receipts.
Businesses purchasing cocoa in US dollars should assess how currency volatility could compound price changes. Exporters receiving foreign-currency revenue may also need to consider how conversion rates affect margins and cash flow.
Forward contracts can help eligible businesses manage exchange-rate uncertainty for known future payments or receipts. The appropriate approach depends on transaction size, payment timing and risk tolerance.
Open a Currency Hedger account: https://currencyhedger.numito.com/onboarding
Visit https://currencyhedger.com/ to learn more about international payments, multi-currency accounts and currency risk management.
Today Markets Analysis
Cocoa enters the new week under pressure as weaker North American demand and rising ICE inventories outweigh stronger Asian and European processing figures. The immediate outlook remains cautious, with Friday’s decline leaving prices vulnerable to further selling if inventories continue to build.
The medium-term supply outlook is more supportive, with early estimates pointing to smaller crops in Ivory Coast and Ghana and additional weather risks from El Niño. These concerns may limit the downside if production forecasts deteriorate further.
For the coming sessions, traders should focus on inventory trends, West African harvesting and delivery conditions, and whether demand weakness spreads beyond North America.
Contributor: Currency Hedger
Disclaimer: This analysis is provided for informational and educational purposes only and does not constitute investment, financial or trading advice. Cocoa futures are volatile and can respond rapidly to grindings data, inventories, weather, crop forecasts, disease and speculative positioning. Forecasts and scenarios are not guarantees of future performance. Businesses and traders should conduct independent research and seek professional advice where appropriate.