S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- EUR/USD recovers to 1.0850 on Monday after briefly breaking below 1.08 last week.
- Preliminary PMI data for March from Germany, France and the overall Eurozone comes in mixed.
- Markets are seeing a sigh of relief at the possible softening stance for reciprocal tariffs.
The EUR/USD pair edges higher and recovers to 1.0850 at the time of writing on Monday after facing some selling pressure at the end of the previous week, when it briefly broke below the 1.08 big figure level. Overall, the pair is expected to stay above 1.08 for now after United States (US) officials commented on Monday that the upcoming reciprocal tariffs will rather be targeted by sector and country, not at all simply broad-based as US President Donald Trump had originally announced.
Meanwhile, on the economic data front, the preliminary Purchasing Managers Index (PMI) for March is being released on Monday. In the old continent, S&P Global and Hamburg Commercial Bank (HCOB) PMIs have been upbeat in France, beating estimates and February’s readings in both the manufacturing and services sectors, but they still signal contraction. Meanwhile, results for Germany and the overall Eurozone have been mixed. The focus now shifts to the US S&P Global PMI data at 13:45 GMT.
Daily digest market movers: Focus on PMIs
- European PMI data has already been released:
- For France, upbeat numbers with the Services component coming in at 46.6, beating the 46.3 expected and the previous reading of 45.3. The Manufacturing sector component jumped to 48.9, coming from 45.8 in February and beating the 46.2 expected.
- In Germany, the Services sector reading fell to 50.2, missing the 51.4 estimate and below the previous 51.1. The Manufacturing component popped to 48.3, beating the previous 46.5 and above the consensus of 47.7.
- In the overall Eurozone, Services PMI decreased to 50.4 from 50.6 previously, falling below the 51.0 expected. However, the Manufacturing reading accelerated to 48.7 from 47.6 in February, beating the 48.0 expected.
- At 12:30 GMT, the Chicago Fed National Activity Index for February is due. No forecast is available, with the previous reading at -0.03.
- At 13:45, the US preliminary PMI data for March is due by S&P Global. The Services PMI is expected to marginally tick up to 51.2, coming from 51.0. Manufacturing reading is expected to decline to 51.9 from 52.7.
- At 19:10 GMT, Vice Chair for Supervision of the Board of Governors of the Federal Reserve System Michael Barr will speak in a moderated discussion on small business lending at an event hosted at Advancing Innovation and Fairness in Small Business Finance, Washington, D.C.
- Equities are rallying on Monday after the news that the upcoming reciprocal tariffs might be less severe than initially announced. In Europe, all indices are up near 0.5%, while US futures see the Nasdaq lead over 1% ahead of the opening bell.
- The CME Fedwatch Tool projects a 85.1% chance for the Federal Reserve (Fed) to keep interest rates unchanged in the May meeting while there is a slim 14.9% chance for a rate cut.
- The US 10-year yield trades around 4.289% and is looking for direction after the steep correction from last week.
Technical Analysis: A sign on the wall?
The EUR/USD pair is stuck in a very tight range on the weekly chart. The fact that EUR/USD closed below the 200-week Simple Moving Average (SMA) at 1.0854 last week means that a return to 1.10 is not in the cards immediately. On the other hand, the support from the 100-week SMA at 1.0782 and the 55-week SMA at 1.0740 reveal that a turnaround to 1.05 is not set to materialize quickly either.
On the upside, 1.1000 is the key level to look out for. Once that level is breached, the pair enters the famous 1.1000-1.1500 range, where it often tends to stay for quite some time. First, of course, the 200-week SMA at 1.0854 needs to be reclaimed.
On the downside, the support from the 100-week SMA at 1.0782 and the 55-week SMA at 1.0740 should be enough to support any selling pressure EUR/USD might face. In case it does not hold, 1.0667 and 1.06 are the next targets to the downside.
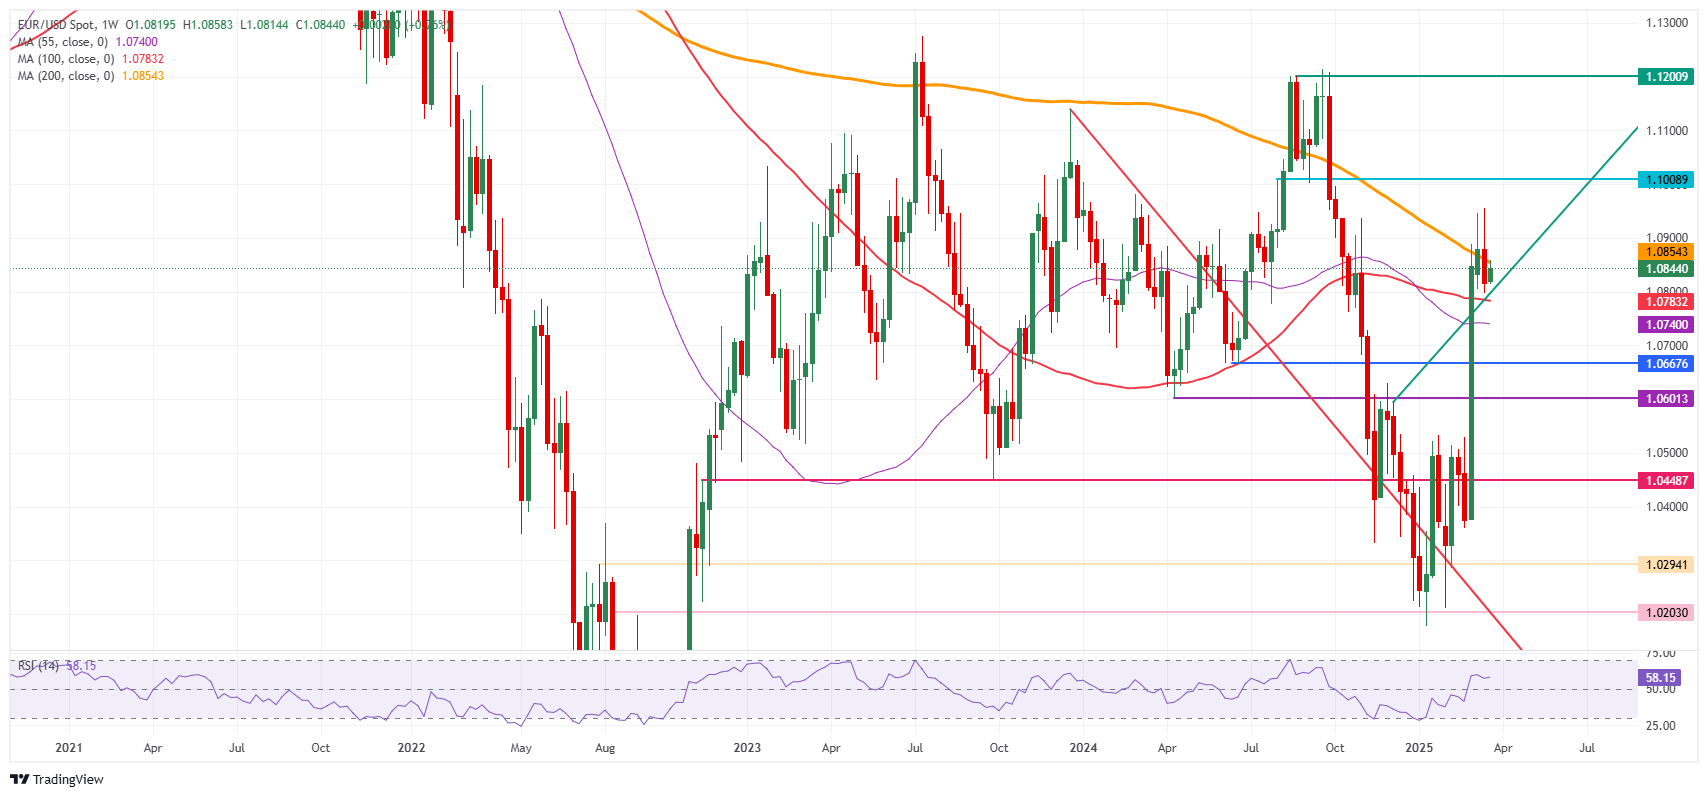
EUR/USD: Weekly Chart