S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- The Indian Rupee trades lower against the US Dollar ahead of the Fed’s policy announcement.
- The Fed is seen leaving interest rates steady.
- Higher oil prices have weakened the Indian Rupee.
The Indian Rupee (INR) gives back its opening gains and turns slightly negative against the US Dollar (USD) on Wednesday. The USD/INR pair ticks up to near 95.16 as the Indian currency underperforms due to multiple headwinds, such as the oil price recovery and caution ahead of the Federal Reserve’s (Fed) monetary policy announcement.
In the opening trade, the MCX Crude Oil contract expiring on November 19 is up 1.82% to near Rs. 9,671, closer to its recent highs of Rs. 9,828.
Higher oil prices bode poorly for currencies from economies, such as India, which rely heavily on oil imports to meet their energy needs.
Oil prices gain as Houthis attack Saudi’s biggest refinery
On Tuesday, a military spokesperson from Yemen’s Iran-aligned Houthis said that they launched a ballistic missile toward the Ras Tanura oil refinery in eastern Saudi Arabia, the kingdom’s largest refinery, Reuters reported.
The incident has reinforced fears of further acceleration in energy supply risks, prompting oil prices to rise.
Higher oil prices have also lent support to United States (US) Treasury Yields. Such a case diminishes the appeal of riskier currencies, like the Indian Rupee. As of writing, 10-year US bond yields are up 0.46% to near 5.02%.
Fed’s policy decision awaited
Later in the day, the Fed’s monetary policy announcement will be the key trigger for global markets. According to the CME FedWatch tool, the Fed is expected to leave interest rates unchanged in the 3.75%-4.00%.
In the September policy meeting, the Fed hiked interest rates by quarter-to-a-percent and signaled at least one more this year through the dot plot.
Financial markets were confident after the September policy announcement that the Fed will hike again in October; however, they pared hawkish bets as several policymakers signaled no urgency for another interest rate hike.
Waller flags more hikes but slower pace, keeping Dollar bulls on alert
Fed’s Waller delivered a distinctly hawkish message, with an 8/10 FXS Speechtracker score that is firmer relative to the historical average of 7.2/10, underscoring a bias toward further tightening. The insistence that “more hikes [are] needed” while allowing that they “do not need to come at consecutive meetings” signals a higher terminal rate but a more flexible path, a mix that supports the Dollar via expectations of prolonged restrictive policy rather than an aggressive near-term hiking cadence. Emphasis on persistent inflation drivers such as AI-related investment, ongoing energy shocks, and a still “solid and stable” labor market reinforces the risk that inflation expectations could de-anchor after nearly 5½ years above-target inflation, keeping the policy skew clearly on the hawkish side.
The FXS Fed Sentiment Index rose by 0.42 points to 138.34, confirming that the speech pushed the policy tone deeper into hawkish territory well above the neutral 100 mark. This elevated index level, aligned with the above-baseline FXS Speechtracker score, should underpin Dollar support as markets price in a longer period of restrictive rates even if individual meetings do not always deliver consecutive hikes.
USD/INR Technical Analysis
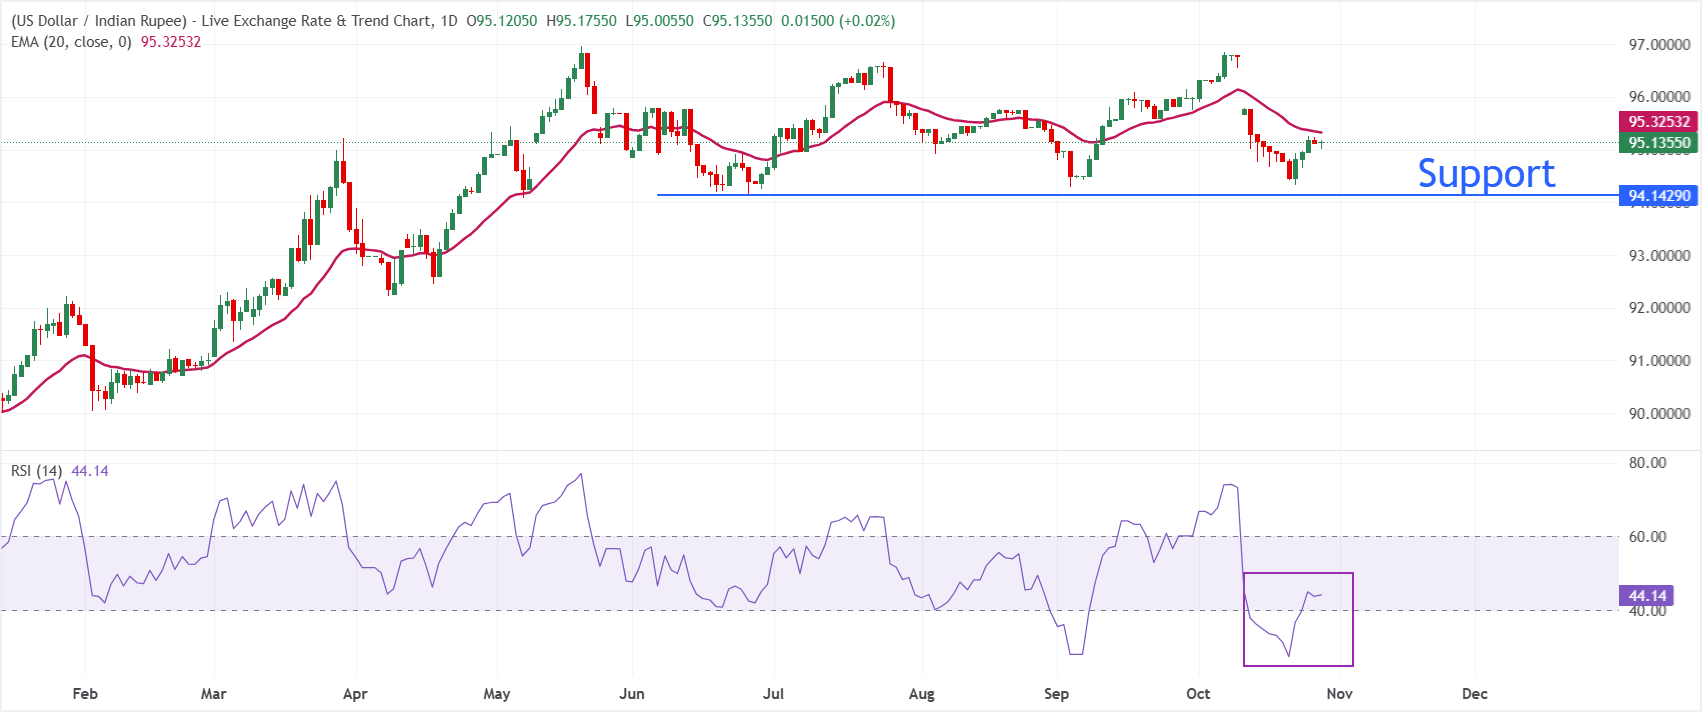
In the daily chart, USD/INR trades at 95.1355, keeping a bearish near-term tone as spot remains below the 20-period exponential moving average (EMA) at 95.3253. The pair’s inability to reclaim this short-term EMA suggests rallies are being sold into, while the Relative Strength Index (RSI) at around 44 stays in neutral-to-soft territory, hinting at a lack of upside momentum rather than outright oversold conditions.
On the topside, initial resistance is aligned with the 20-day EMA at 95.3253, and a sustained break above this barrier would be needed to ease immediate downside pressure and open the way for a more meaningful recovery. In the absence of clearly defined nearby support levels from the available indicators, the focus stays on price action relative to this EMA pivot, with continued trading beneath it likely to preserve the bearish bias in the short term.