Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
Earnings CalendarMarketsOpinionStocksTechnical Analysis

Intel: AI drives results, and CPUs may be the next stage of the revolution

Intel’s results for the first quarter of 2026 clearly reinforce the view that the company is beginning to emerge from a multi-year period of operational weakness. The report itself delivered a solid beat versus expectations, but even more important are the forecasts for the coming months, which give the release a distinctly more growth-oriented tone and acted as a catalyst for a strong market reaction.

Key financial highlights for Q1

  • Revenue $13.58 billion, 7.2% YoY, above consensus
  • Adjusted EPS $0.29 vs expectations around $0.01
  • Gross margin 41% vs 34.5% forecast
  • Data Center & AI $5.05 billion, 22% YoY
  • Foundry $5.42 billion, 16% YoY
  • Operating income $1.67 billion vs $0.69 billion a year earlier
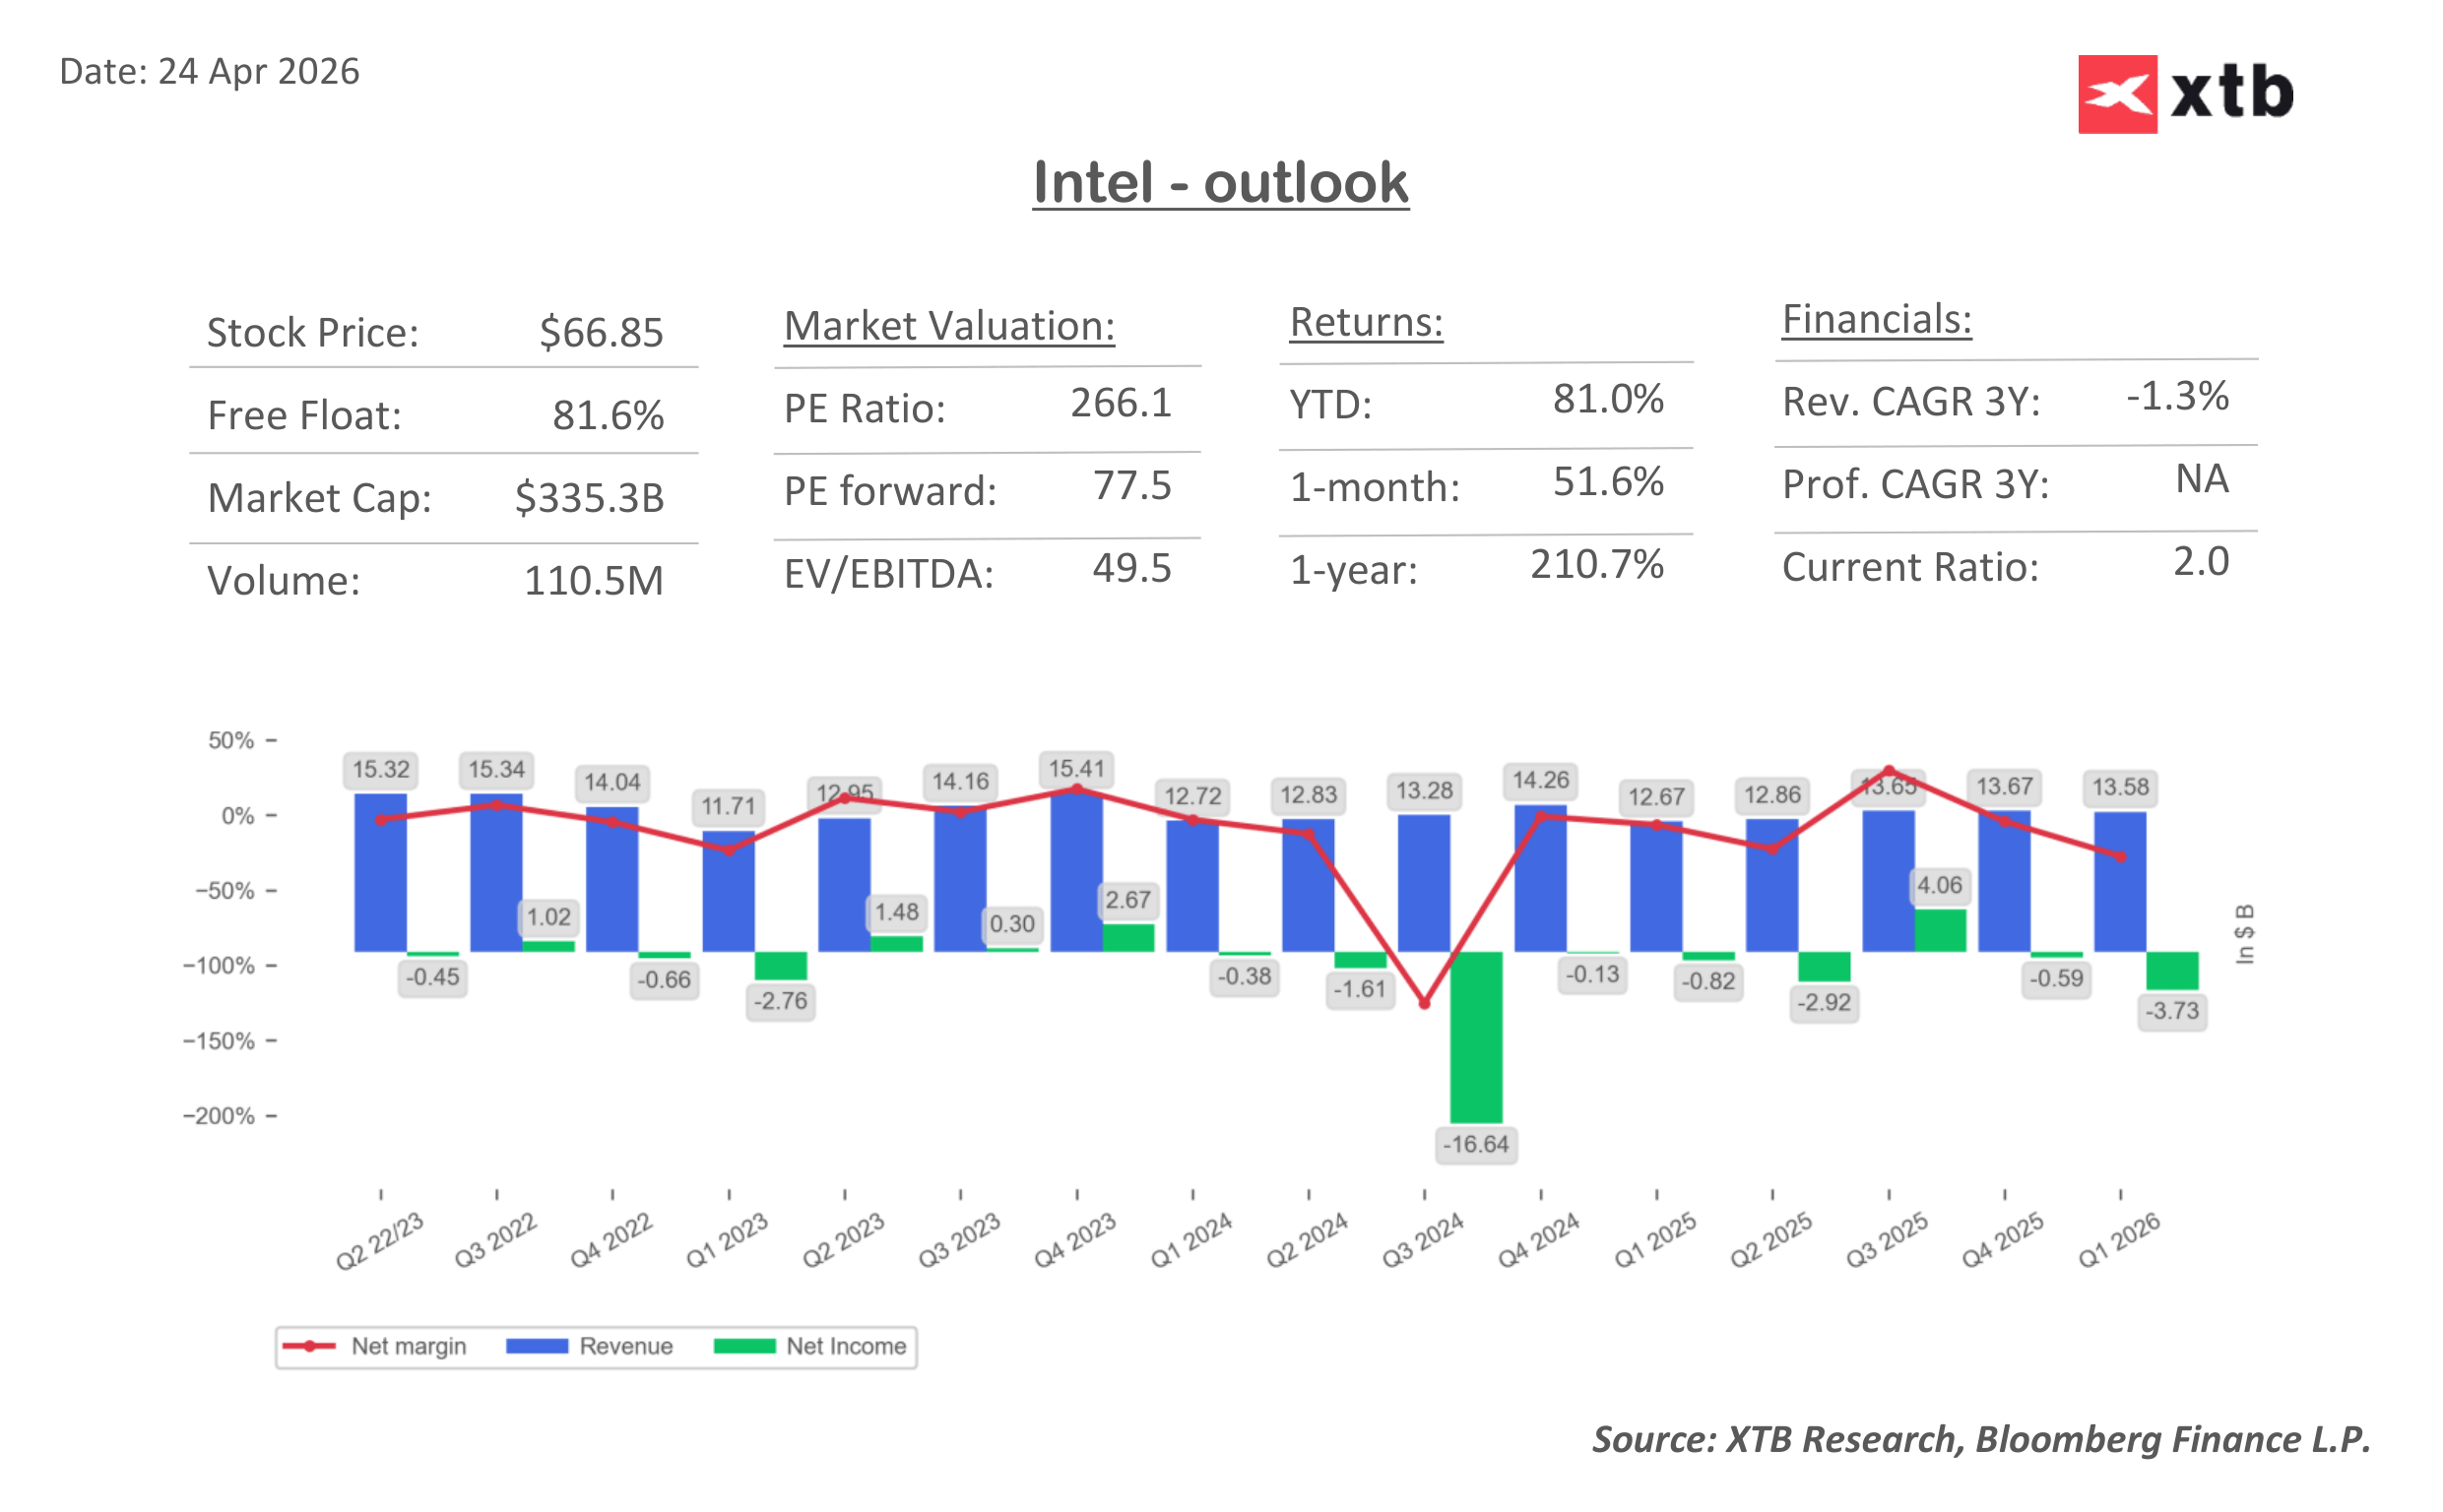
The scale of the positive surprise is visible not only in revenue, but above all in profitability. The increase in gross margin to 41% suggests improvements in both the sales mix and cost efficiency. This indicates that actions taken in recent quarters are starting to translate into tangible financial results. The Data Center & AI segment remains the primary growth driver, posting 22% YoY. This confirms that artificial intelligence is already generating real and growing demand, particularly in server infrastructure. Increasing importance of inference and edge-related applications is reinforcing the role of CPUs within the broader ecosystem.

The first phase of the AI boom was largely driven by GPUs, where NVIDIA established a dominant position. However, there are growing indications that the next phase could shift the center of gravity toward CPUs, especially in the context of scaling and broader adoption of AI applications. The foundry segment is expanding at 16% YoY and is gradually becoming a more meaningful part of the business mix. Improved capacity availability suggests that previous supply constraints are easing, supporting both shipment volumes and pricing.

Guidance remains the key focus for the market. For the second quarter, the company expects revenue in the range of $13.8 billion to $14.8 billion and EPS of $0.20, clearly above prior expectations. In addition, projected gross margin of around 39% points to continued improvement in profitability. On a broader view, the company signals sustained strong demand and the potential for above-seasonal growth in the coming quarters of 2026, supported by AI expansion and improved supply conditions. This suggests that the momentum seen at the start of the year could continue into the second half.

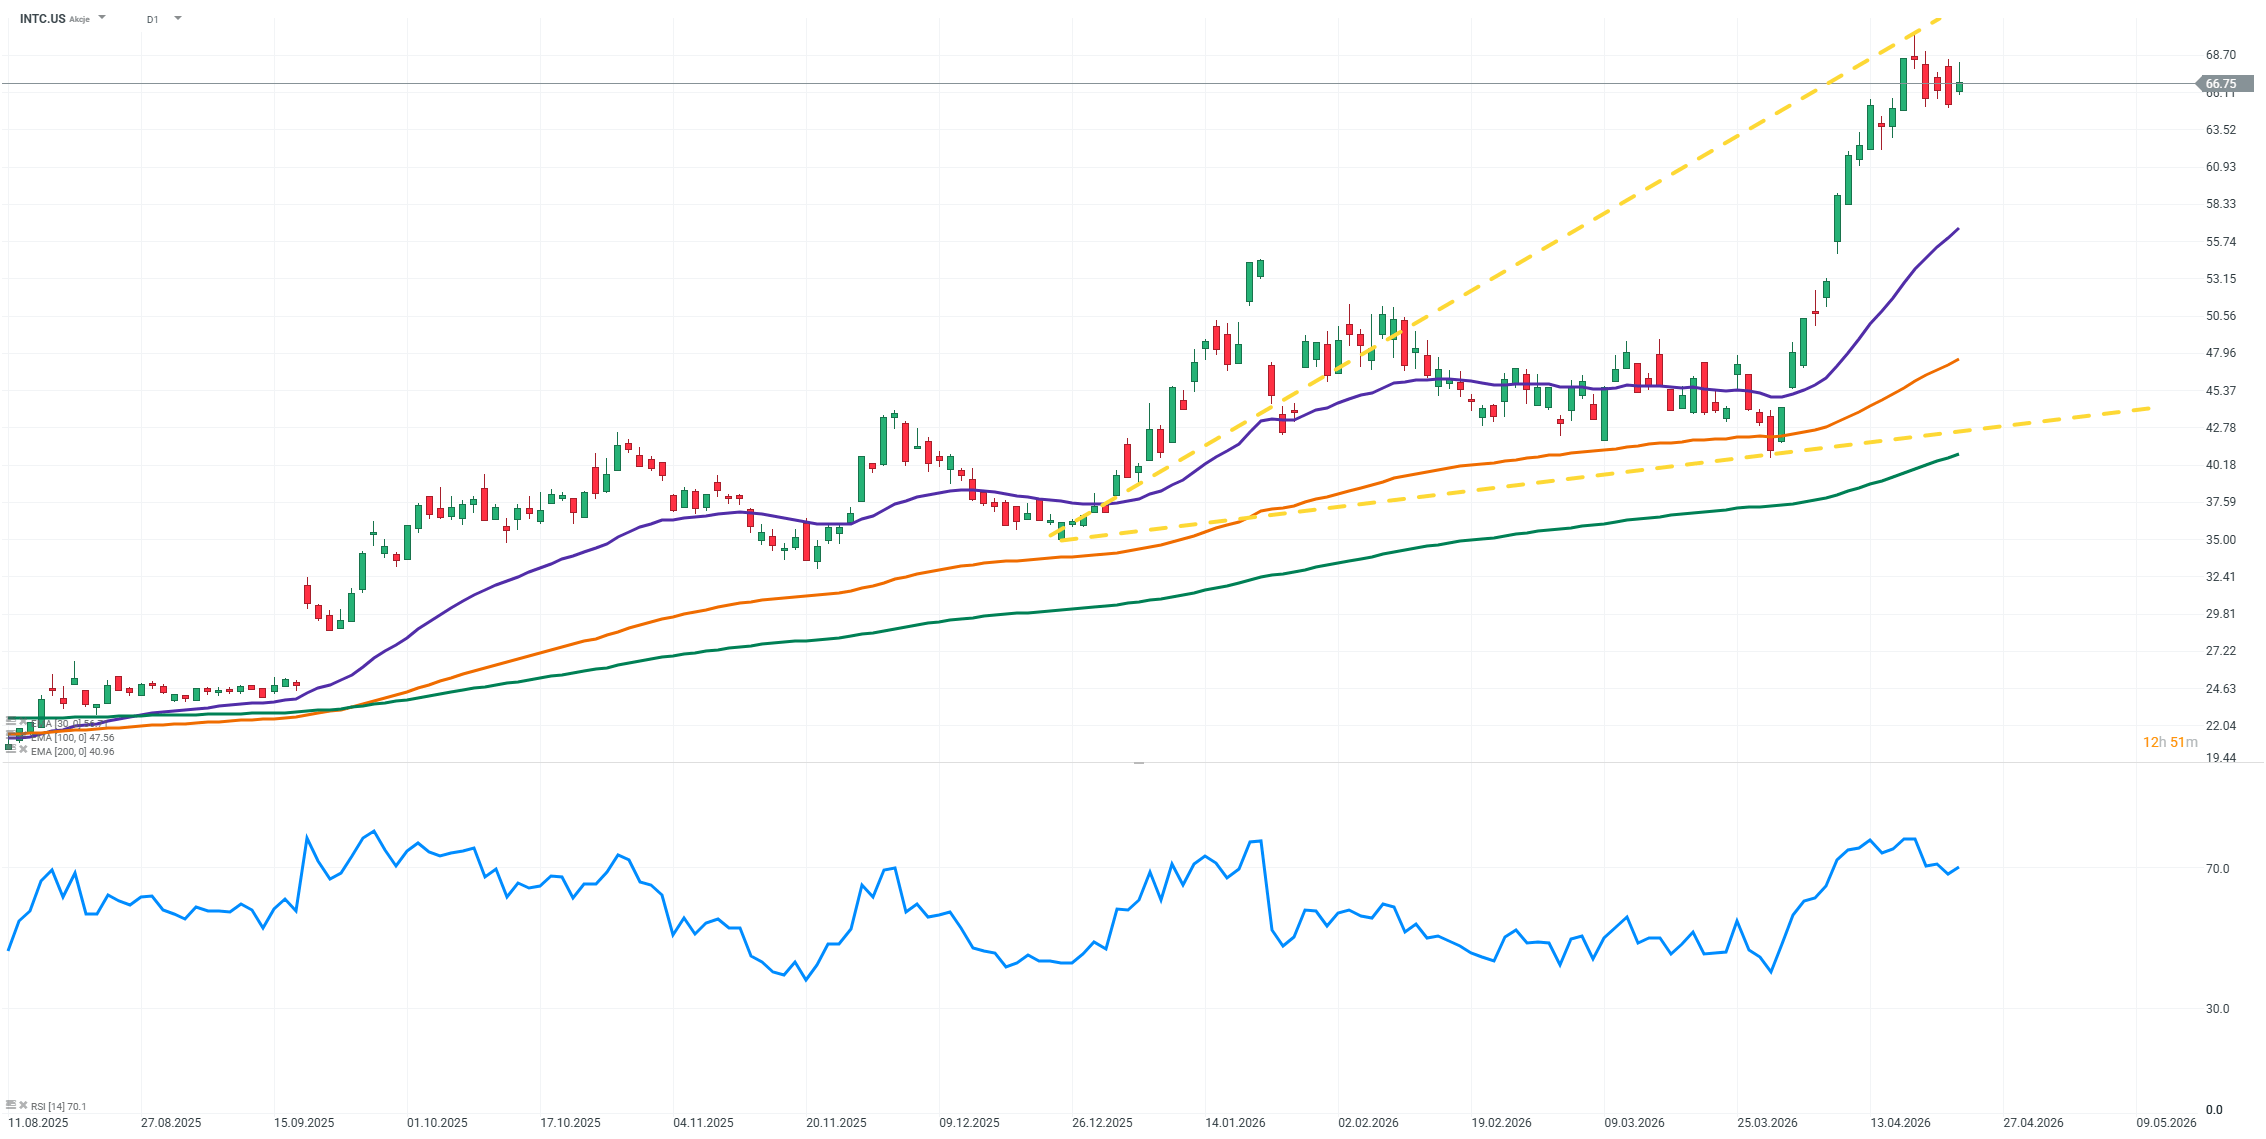
The market reaction was very strong, with the stock rising more than 20% in premarket trading, also lifting other companies in the semiconductor sector. It is worth noting that Intel shares have already gained more than 70% year-to-date. Despite the clear improvement, challenges remain. Pressure from high capital expenditures is still evident in cash flow levels, highlighting that the transformation process continues to require time and consistent execution.

Overall, the reported results and outlook point to an increasingly credible improvement in the company’s fundamentals. Support from rising AI-driven demand, better capacity availability, and improving operational efficiency creates a solid foundation for further performance gains in the coming quarters. At the same time, higher market expectations mean that sustaining this trend will be critical for future stock performance.
Source: xStation5

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button