S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Markets Dampen Early Optimism; Political Shock in the UK


European share indices have opened the week on a mixed note — the Spanish IBEX 35 is up 0.65 per cent, the Dutch AEX is up 0.56 per cent, and the London FTSE 100 is barely in positive territory (+0.19 per cent), whilst the DAX (-0.25 per cent), the CAC40 (-0.78 per cent) and the Italian FTSE MIB (-0.32 per cent) remain under pressure.
Market sentiment is being driven primarily by developments surrounding the US–Iran peace talks, following the announcement by mediators from Qatar and Pakistan of a preliminary agreement on a roadmap for a final deal within 60 days, which has significantly reduced the geopolitical risk premium. However, the talks remain fragile — Iran has once again announced the closure of the Strait of Hormuz, a move that previously drove oil prices up to nearly $126/bbl in May, and the markets remain cautious about the sustainability of the de-escalation. Brent crude is down by around 0.7% to $80 per barrel, whilst WTI is trading around $75–77, giving back earlier gains. The dollar is strengthening — the DXY index is up 0.13%, whilst the USD/JPY pair is rising to 161.74, supported by the Fed’s hawkish stance, which is signalling a possible rate rise as early as September.
An additional factor affecting sentiment in the UK was the resignation of British Prime Minister Keir Starmer, who this morning officially announced his departure from his posts as leader of the Labour Party and head of government — meaning the UK is now facing its seventh prime minister in a decade. The market reaction was, however, muted: the pound lost just 0.19% against the dollar, trading at around USD 1.3207, whilst yields on 10-year gilts remained virtually unchanged at 4.85%, as the resignation had been widely priced in following Andy Burnham’s victory in last week’s by-election. The Polymarket prediction market puts Burnham’s chances of becoming Prime Minister at as high as 96 per cent, and nominations in the Labour leadership race are set to open on 9 July — yet the key question for nervous bond markets remains who will take the post of Chancellor of the Exchequer and how the new government will tackle Starmer’s most difficult legacy: strained public finances.
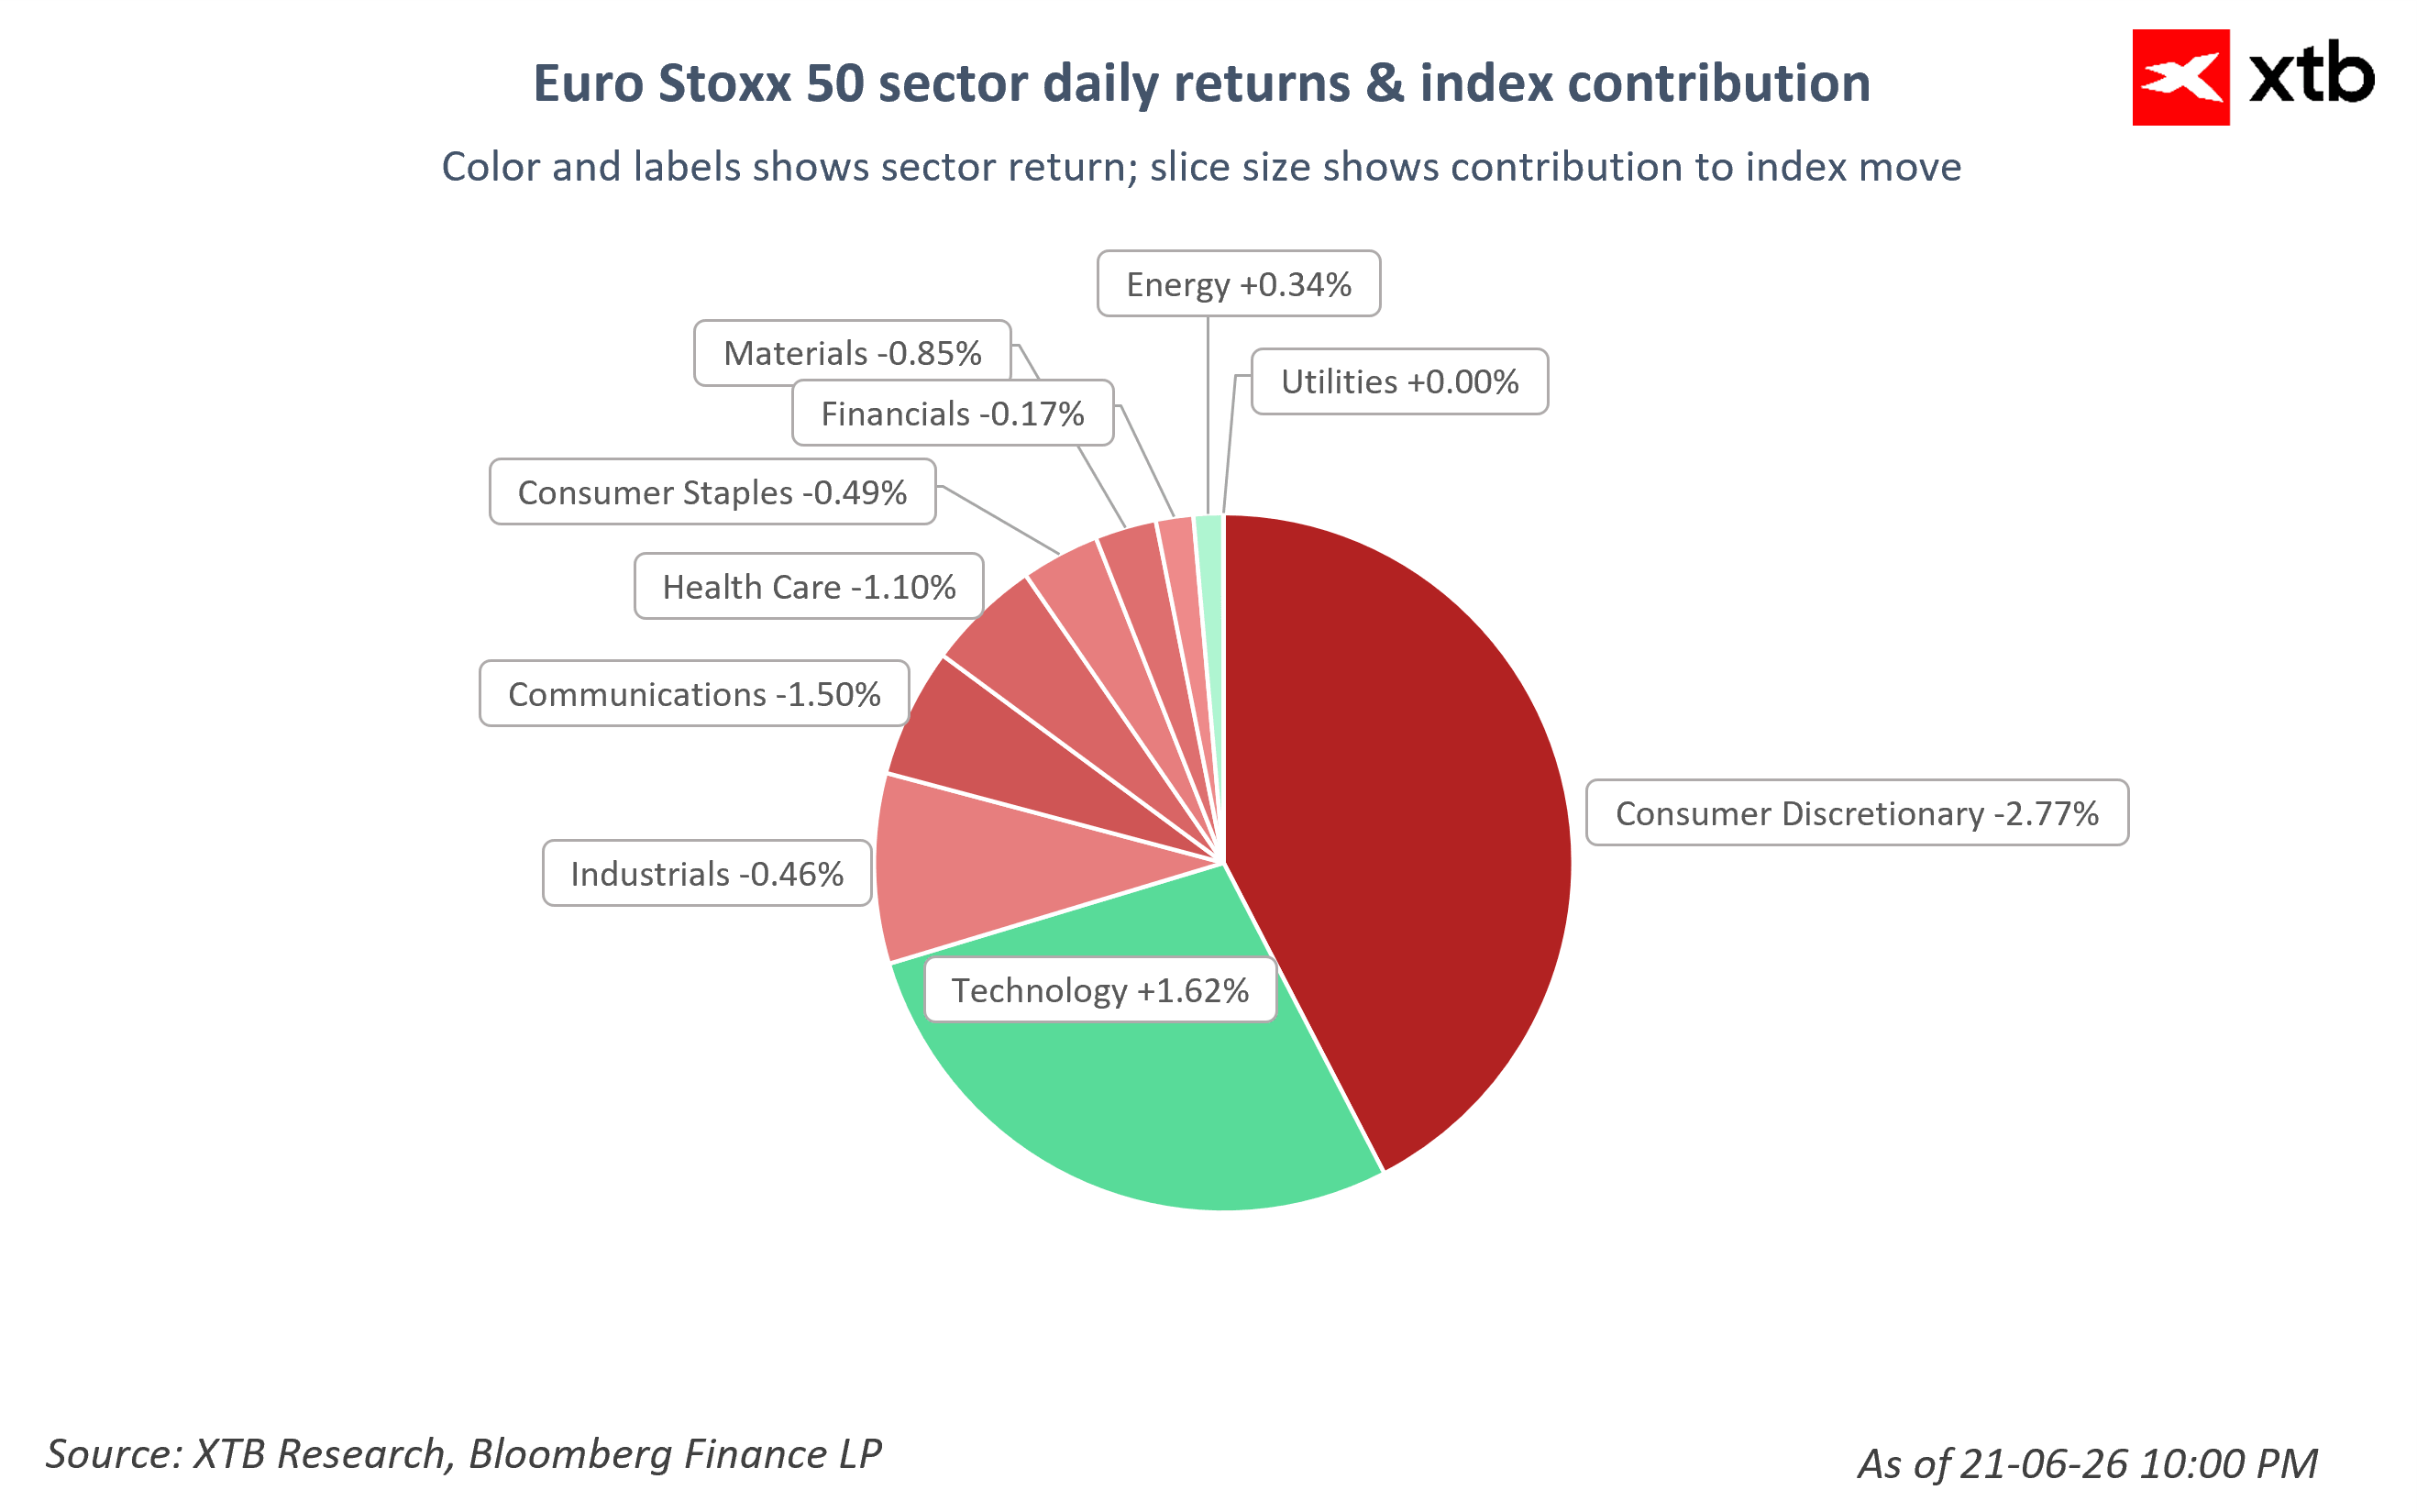
At sector level within the Euro Stoxx 50, technology is clearly in the green (+1.62%), driven by semiconductors, whilst the luxury goods and discretionary consumption sectors (-2.77%) are predominantly in the red, along with communications (-1.50%) and healthcare (-1.10%). However, the rise in volatility as measured by the VSTOXX index (-1.61% compared with the previous close) suggests that the market has calmed down somewhat following last week’s turbulence.
Company information
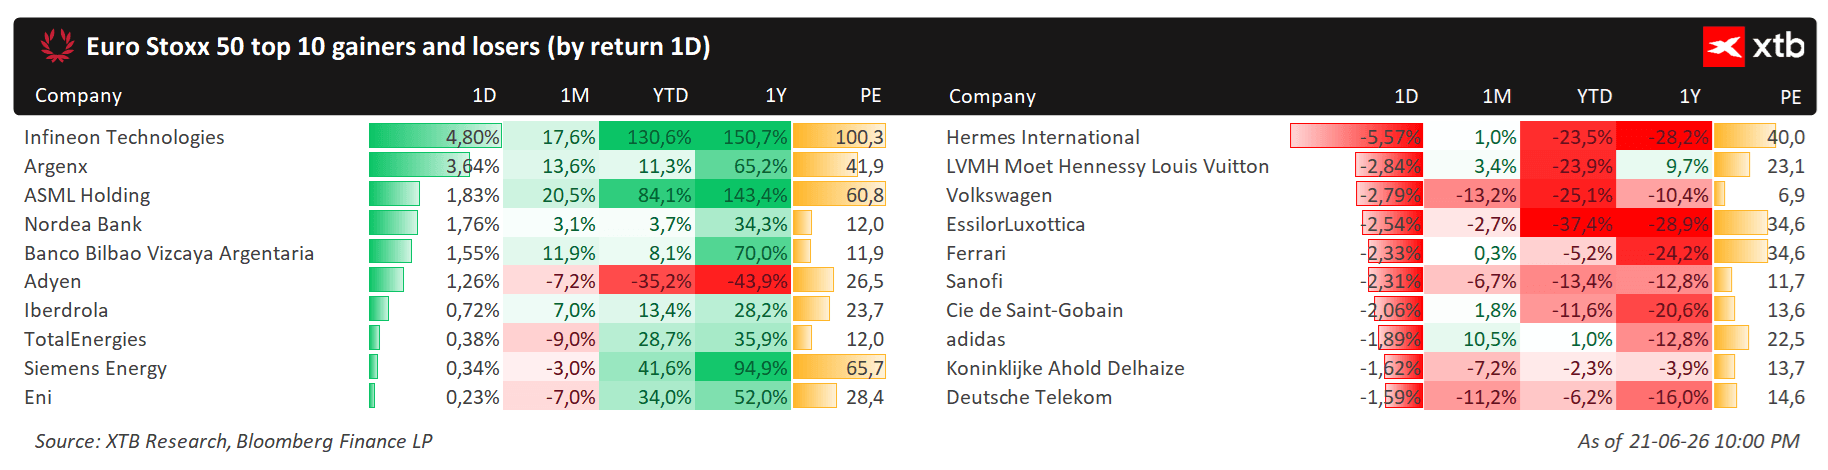
- Infineon Technologies is posting the biggest gain on the Euro Stoxx 50 — its shares are up +4.80% during the session, continuing an impressive run: +130.6% year-to-date and +150.7% year-on-year, with a P/E ratio of 100x, reflecting investor enthusiasm for industrial and automotive semiconductors amid the AI boom.
- Hermès International is down -5.57% and is the index’s biggest loser, with its shares down -23.5% since the start of the year — the weakness in the luxury goods sector stems from concerns over demand in China and a slowdown in consumer spending in the premium segment.
- LVMH is down 2.84%, adding to the luxury sector’s slump (-23.9% YTD).
- EasyJet is up by around 3% after the Castlelake fund made a third bid to take over the airline, reigniting speculation about consolidation in the European low-cost airline sector. Babcock International is down nearly 4% following disappointing results — the defence company missed its gross profit forecast, whilst BioArctic is up 8% after announcing a collaboration agreement with Eli Lilly in the field of neurological therapies.