S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

POET Technologies is emerging as a speculative name in the artificial intelligence infrastructure trade, with its optical interposer technology targeting the growing need for faster, more efficient data transmission inside AI data centres. However, the Canadian company faces a substantial challenge: converting its technology and industry interest into meaningful commercial revenue while controlling losses and proving that it can manufacture advanced optical components at scale.
With a market capitalisation of approximately $1.3 billion, reported revenue of around $1.7 million and a net loss of as much as $75 million, the gap between POET’s valuation and its current financial performance remains considerable. The investment case therefore depends less on what the company earns today and more on whether it can establish a commercially viable position in a rapidly expanding photonics market.
Market Snapshot
- Market capitalisation: Approximately $1.3 billion
- Revenue: Around $1.7 million
- Net loss: As much as $75 million
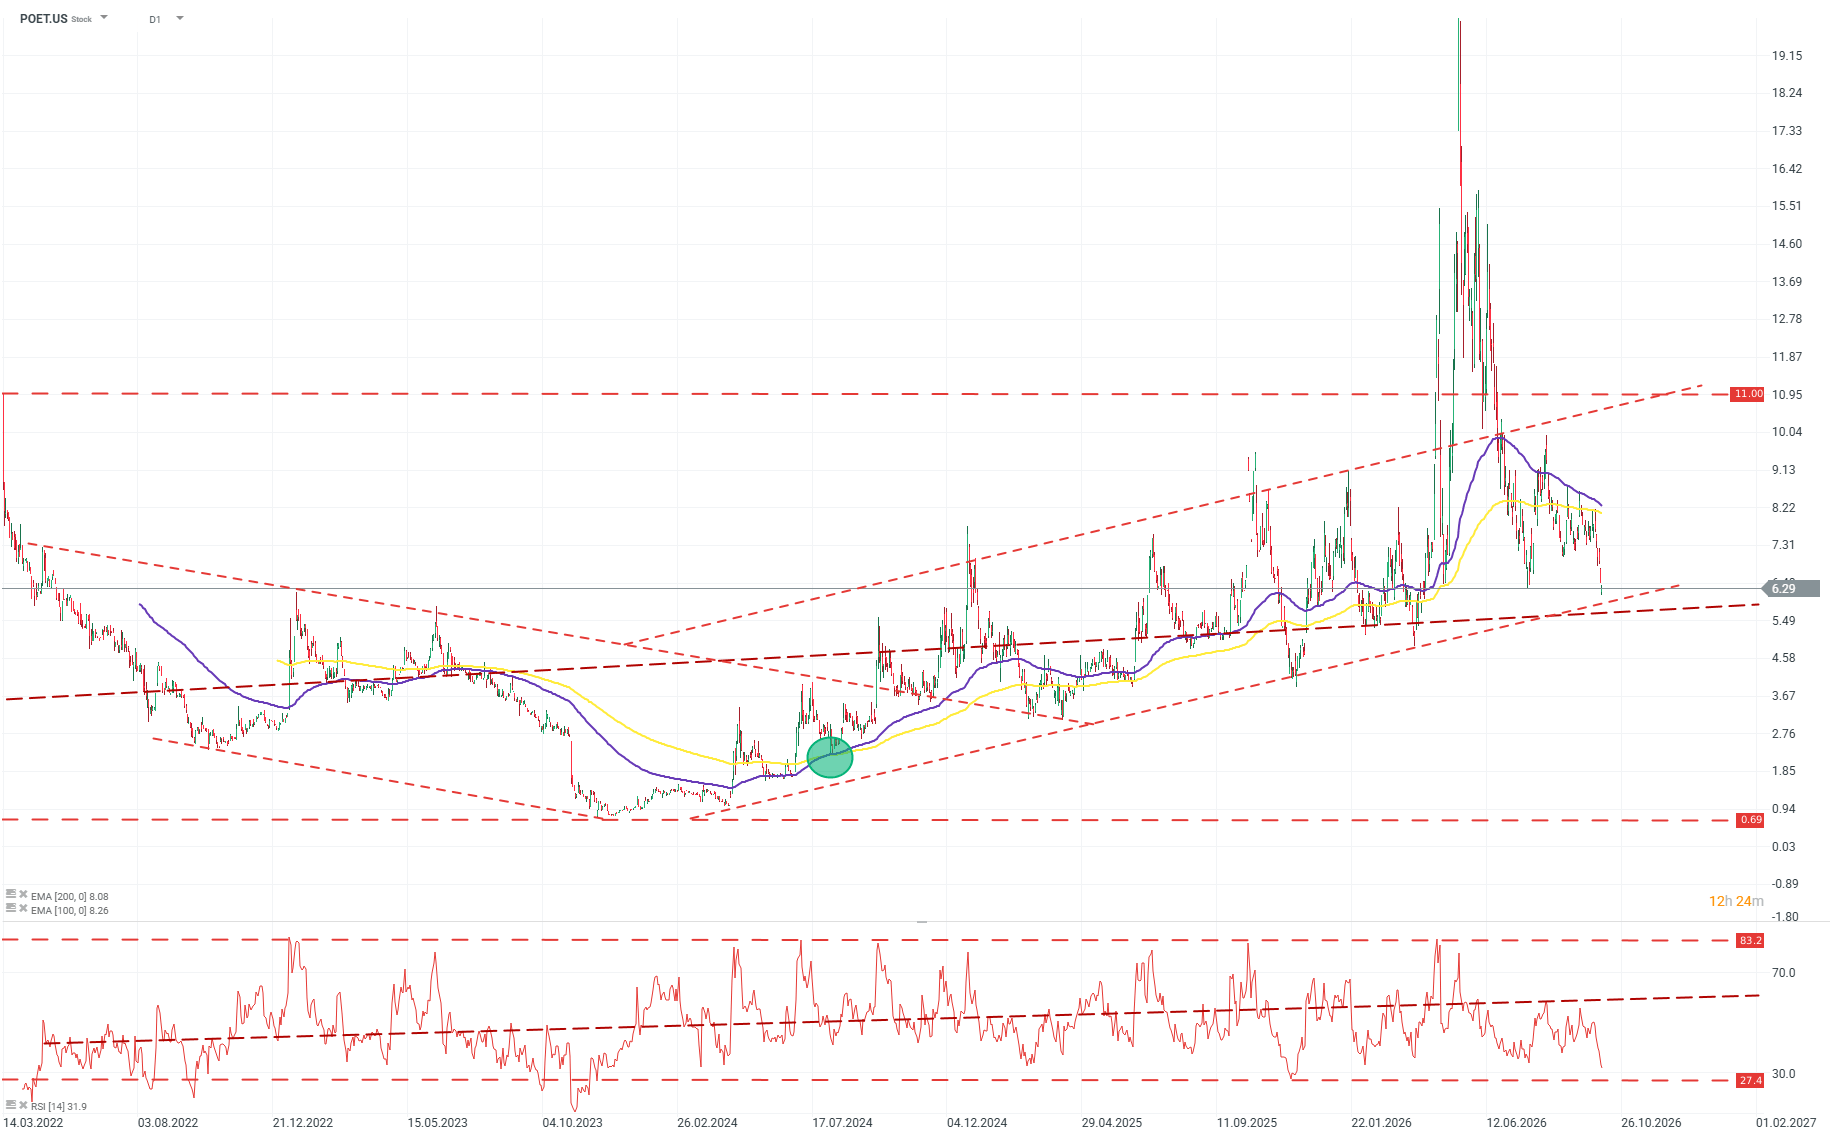
- Recent share-price context: A retreat from approximately $17 towards the $6–$9 range
- Key growth driver: Optical connectivity for AI data centres
- Principal risks: Customer acquisition, manufacturing yields, financing and execution
POET’s valuation reflects expectations of future commercial growth rather than established earnings power. That creates the potential for substantial upside if the company delivers, but also leaves the share price vulnerable if orders, production milestones or financial results fall short of expectations.
POET price chart (D1)
POET’s Position in the AI Photonics Market
The expansion of artificial intelligence is placing increasing demands on data-centre infrastructure. AI workloads require large volumes of data to move rapidly between processors, memory and networking equipment. As conventional electrical interconnects encounter constraints involving bandwidth, power consumption and signal integrity, optical technologies are becoming increasingly important.
POET’s Optical Interposer platform is designed to integrate optical and electronic components into compact, configurable assemblies. The intended applications include optical engines, transmitters, receivers and connectivity solutions for high-speed data-centre networks.
The opportunity is significant, but operating in a growing market does not automatically translate into commercial success. POET must demonstrate that its products can meet customer specifications, deliver reliable performance, achieve competitive production economics and secure repeat orders.
The company’s technology proposition is therefore only one part of the investment thesis. Manufacturing capability, customer qualification and the transition from development programmes to volume production will determine whether the opportunity can support its valuation.
Competition and Industry Demand
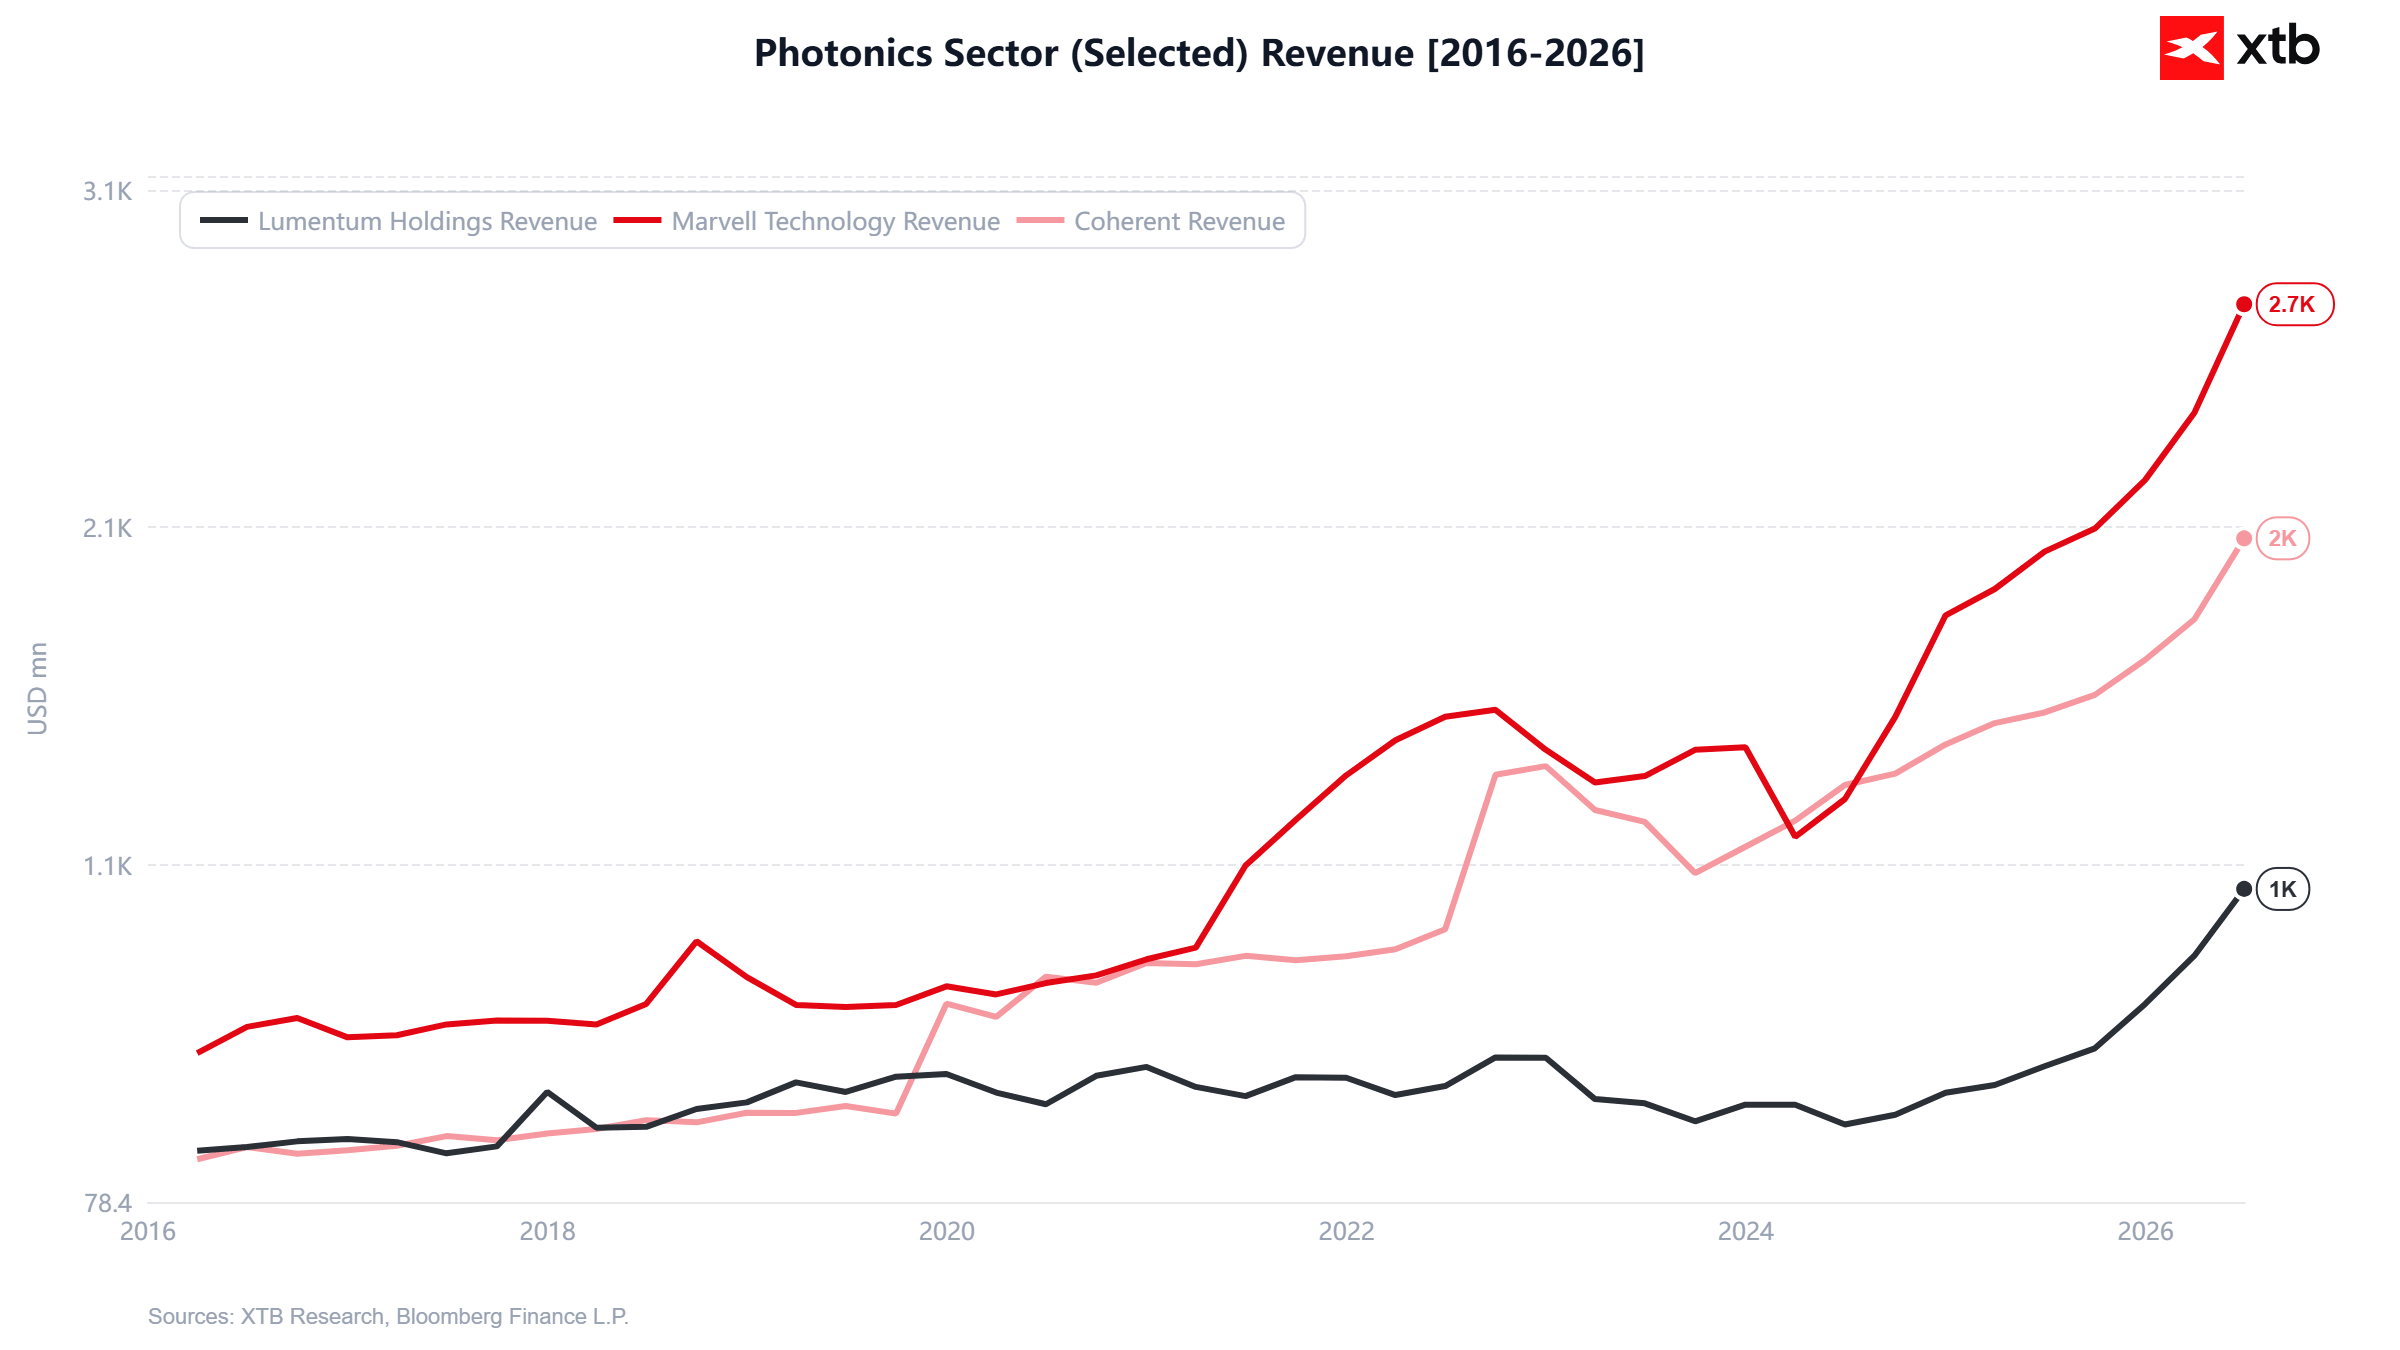
POET operates in a competitive industry that includes established photonics and semiconductor businesses such as Broadcom, Lumentum, Marvell and Coherent. These companies have existing customer relationships, substantial engineering resources and established manufacturing or supply-chain capabilities.
At the same time, the growth of AI infrastructure is creating demand for higher-bandwidth optical connectivity. Industry commentary has highlighted supply constraints across parts of the photonics sector, potentially creating opportunities for smaller suppliers with differentiated technology.
However, broad industry demand must be distinguished from demand specifically available to POET. Even when customers need more optical components, they will select suppliers based on performance, reliability, cost, production capacity and qualification requirements.
For POET, the most important evidence will be customer commitments, conversion of its development pipeline into revenue and the ability to fulfil orders consistently. Strong sector demand can provide favourable conditions, but it cannot substitute for company-specific execution.
Financial Performance and Valuation
The disparity between POET’s market capitalisation and its current revenue makes conventional valuation comparisons difficult. Investors are effectively assigning considerable value to future commercial potential, despite the company remaining loss-making.
The next financial results will be important for assessing whether that potential is beginning to translate into measurable progress. Market expectations include year-on-year revenue growth from approximately $0.5 million to $0.7 million and a reduction in losses towards an earnings-per-share figure of around -$0.05.
These expectations should be treated as estimates rather than guaranteed outcomes. Even if POET meets them, the absolute revenue base would remain small relative to its valuation. Investors will need evidence that revenue can continue to scale beyond individual development projects and initial customer programmes.
Management’s longer-term ambition of approximately $300 million in revenue by 2028 would represent a substantial transformation of the business. Reaching that target would require significant commercial expansion, successful customer qualification, improved manufacturing yields and the capacity to deliver products at scale.
A scenario in which POET achieves that level of revenue could materially alter how the market values the company. However, any discounted cash-flow or valuation model based on that outcome remains highly sensitive to the probability of achieving the target, future margins, capital expenditure, dilution and the time required to reach profitability.
The Marvell Agreement and Investor Confidence
POET’s share-price history has been heavily influenced by expectations surrounding its commercial relationships. Reports of a potential agreement involving Marvell helped drive a substantial rally during April and May 2026. The subsequent termination of the agreement by a Marvell subsidiary, reportedly following a confidentiality breach, became a major setback for investor confidence.
The episode illustrates the sensitivity of speculative technology stocks to announcements, rumours and management decisions. A perceived commercial breakthrough can rapidly increase expectations, while a terminated agreement can reverse those gains.
Investors should distinguish between a signed commercial arrangement, a development collaboration, a customer qualification programme and a revenue-generating production contract. These milestones have different economic implications and should not be treated as interchangeable evidence of commercial success.
POET’s ability to rebuild confidence will depend on verifiable progress rather than renewed speculation alone.
Bullish Scenario
A more constructive outlook would emerge if POET demonstrates that its optical interposer platform can move from development into repeatable commercial production.
The main factors supporting a bullish scenario include:
- Customer diversification: Securing additional customers would reduce dependence on individual relationships and broaden the addressable revenue base.
- Manufacturing improvements: Higher production yields could lower unit costs, improve margins and make larger orders economically viable.
- AI infrastructure demand: Continued investment in data centres and high-speed optical connectivity could expand the opportunity for qualified suppliers.
- Commercial validation: Repeat orders, meaningful backlog conversion and sustained revenue growth would provide stronger evidence of product-market fit.
- Financial discipline: Preserving sufficient capital to fund development and production would give the company more time to execute its strategy.
If these conditions are met, the market could begin valuing POET on its prospective commercial earnings rather than its current limited revenue. That could support a significant recovery, although the scale and timing of any share-price appreciation would remain uncertain.
Bearish Scenario
The downside case centres on the risk that technological promise fails to translate into profitable commercial operations.
Potential negative developments include:
- Slow customer adoption: Qualification processes may take longer than expected, delaying meaningful revenue.
- Poor manufacturing yields: Production inefficiencies could raise costs, constrain deliveries and undermine the economics of the platform.
- Intense competition: Established suppliers may respond with competing solutions, pricing pressure or stronger customer propositions.
- Financing requirements: Persistent losses could eventually require additional capital, potentially diluting existing shareholders.
- Valuation compression: If commercial milestones are delayed, investors may reassess the premium embedded in the company’s market capitalisation.
The stock’s speculative appeal can amplify these risks. Strong retail interest and momentum-driven buying may support the share price for periods, but sentiment can reverse quickly when expectations are not met.
Forecast: What Could Determine the Next Move?
POET’s outlook is best understood through a series of operational milestones rather than a single share-price target.
In the near term, quarterly results and management commentary may influence sentiment, particularly if revenue growth, customer activity or production progress differs from expectations. However, one quarter of improved figures would not by itself establish a sustainable growth trajectory.
Over the medium term, the most important question is whether POET can convert its technical capabilities into repeatable, economically attractive production. Evidence of customer diversification, increasing shipments and improving yields would strengthen the investment case.
The longer-term opportunity depends on the company’s ability to capture a meaningful share of the AI photonics market. Its revenue ambitions could provide a framework for assessing progress, but investors should evaluate them against demonstrated orders, manufacturing capacity and available financing.
Overall outlook: POET offers exposure to a potentially attractive growth market, but the investment remains high-risk and execution-dependent. A favourable industry backdrop provides an opportunity, not a guarantee of commercial success.
Market Outlook: What to Watch Next
The next several quarters should help establish whether POET is progressing towards a commercially sustainable business.
- Revenue and customer acquisition: Look for sustained growth, additional customers and evidence that existing relationships are generating repeat business.
- Backlog and order conversion: Assess whether announced opportunities are translating into actual shipments and recognised revenue.
- Production yields: Monitor improvements in manufacturing consistency, reliability and cost efficiency.
- Cash reserves and financing: Review cash consumption, available capital and whether the company can fund its plans without excessive dilution.
- Commercial agreements: Distinguish binding contracts and production orders from preliminary discussions or development arrangements.
- Valuation versus execution: Consider whether the market capitalisation remains justified by the pace of measurable commercial progress.
Today Markets View
POET Technologies represents a high-risk opportunity within the AI infrastructure theme. Its optical interposer technology targets a market in which higher data-transfer speeds and more efficient connectivity are increasingly important. If the company can establish customer trust, diversify its commercial relationships and achieve reliable production at scale, its current financial performance may understate its longer-term potential.
Nevertheless, the valuation already reflects substantial expectations for future growth. The combination of limited revenue, continuing losses, manufacturing challenges and competition means investors must be cautious about treating industry demand as proof that POET will succeed.
The most constructive signal would be a sustained sequence of commercial milestones: growing revenue, repeat orders, improved yields and disciplined cash management. Without that evidence, the shares remain exposed to sharp sentiment-driven moves and valuation risk.
For now, POET is better viewed as a speculative technology investment than an established AI infrastructure business. Its future will depend on execution, not simply on the popularity of the AI theme.
Currency Hedger View
Currency Hedger monitors foreign exchange markets alongside broader commodity and macroeconomic conditions, helping businesses assess and manage their international currency exposure.
Analysis: Louis Roche, Today Markets
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice, a recommendation to buy or sell securities, or a forecast of guaranteed returns. Shares in early-stage technology companies can be highly volatile and may result in substantial losses. Figures and expectations cited are based on the supplied market commentary and should be independently verified against current company disclosures. Forecasts and scenarios are conditional and may not materialise.