Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
Earnings CalendarMarketsOpinionStocksTechnical Analysis

ServiceNow Earnings: What Went Wrong?

ServiceNow suffered a crushing sell-off of nearly 25% after releasing its Q3 2026 results. Were the figures and guidance really so terrible as to justify such a large and sudden loss in value?

Earnings

On the surface, the reported data was good, if not very good.

  • Revenue grew a solid 20% year over year, reaching USD 4.1bn, slightly above consensus, which hovered around USD 4.095bn.
  • Short-term receivables increased by 20% to USD 13.65bn. Meanwhile, long-term receivables rose to USD 29.7bn, up 22% year over year.
  • At the same time, the company highlighted an increase in contracts worth more than USD 5m to 19, representing 135% growth.
  • Potentially the best piece of news for investors is yet another increase in the AVC forecast, this time to USD 1.7bn versus USD 1bn at the beginning of the year. At the same time, the company revealed that customer usage of AI agents increased 13-fold over the year.
  • All of this also allowed the company to raise its FCF margin forecast to 36%.

In light of these results, which number drove the share price down by more than a dozen percent?

The cause was the company’s EPS, which came in at USD 1.00 instead of the expected USD 1.02. Those two cents are far more important to shareholders than it might initially seem. The CFO attributed the shortfall to lower interest income and higher debt costs following the acquisition of Armis. This means that acquisition financing costs weigh on shareholders even when the acquired businesses meet operational targets.
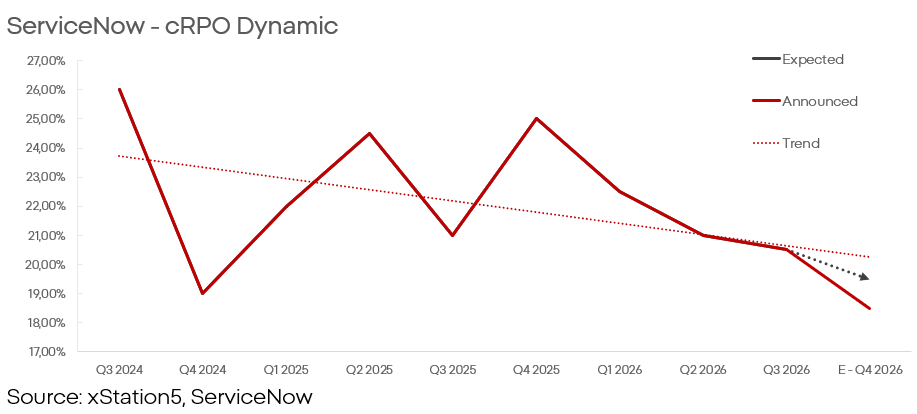
Not all guidance is positive either. Arguably even worse than EPS is forecast for cRPO growth (current remaining performance obligations) was cut for year-end to 18.5%. This is below the market’s minimum expectations of around 19% and signals a potential weakening, if not a breakdown, of operating leverage. On its own, this signal is not a reason for as much concern as the market reaction suggests. However, a sustained decline in receivables growth relative to revenue would dramatically change the company’s outlook. Beating the company’s own margin guidance does not mean margins improved year over year. The decline in profitability, even on an adjusted basis, suggests the issue cannot be explained solely by amortization of acquired assets.
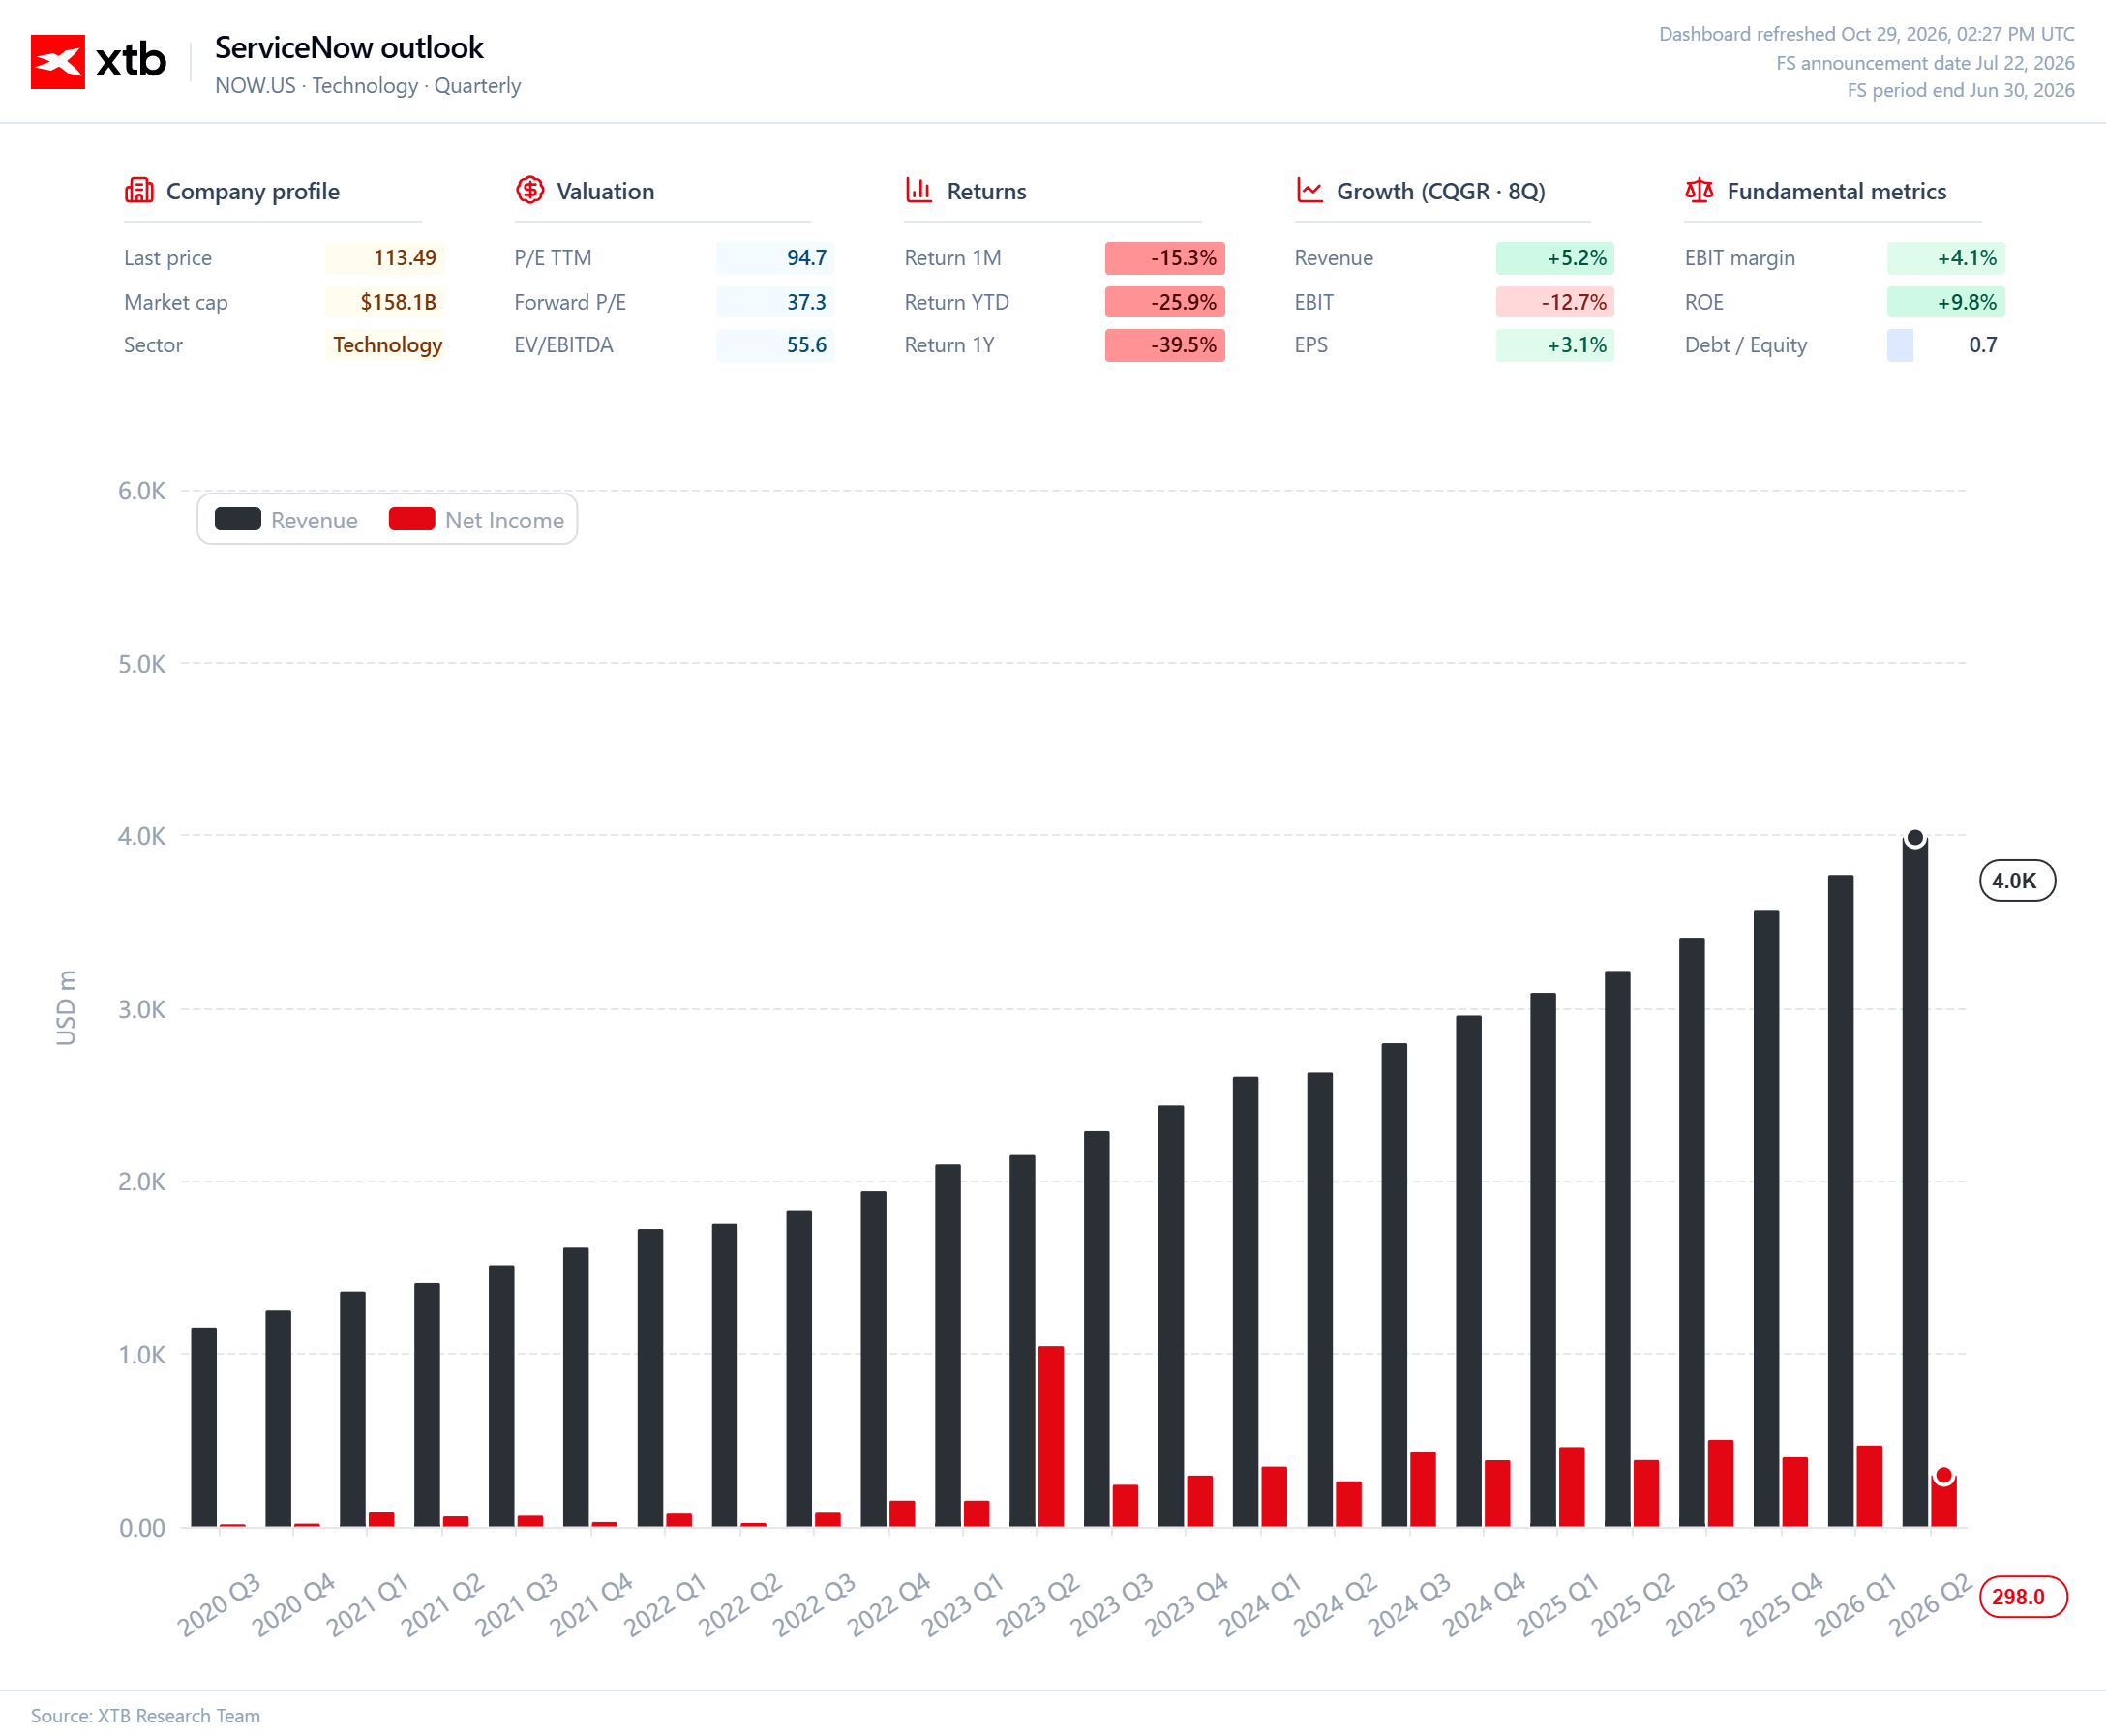
All of this indicates that, in the short- to medium-term, AI monetization will not be as fast or as inexpensive as the market had previously priced in. At the same time, monetization itself may not have as immediate an impact on profitability as earlier guidance implied.

Is the Panic Justified?

While margin compression, both adjusted and reported, is a genuine cause for significant shareholder concern, it is difficult to justify the scale of the stock’s reaction, even after accounting for operating leverage effects. Management points to earlier renewals pulled into Q3, a larger share of on-premise implementations, and contracts with T4C clauses being excluded from backlog. Implementation support added to agreements shifts part of the value from subscriptions to services. Growth remains solid by almost every measurable metric, and the customer base is expanding at a very high pace. Monetizing that base is an opportunity for enormous cash flows for the company and shareholders, even if it is moderately delayed.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button