S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Markets enter the week under pressure from rising oil prices. Brent crude is now trading above $107 per barrel, following the shutdown of Saudi Arabia’s East-West Pipeline, among other factors. Simultaneously, equities across the broader AI ecosystem are suffering a sell-off after leaders from Anthropic, ChatGPT, and Grok issued a joint appeal to slow down artificial intelligence development (which, incidentally, drew a sharp reaction from President Trump). Meanwhile, US 10-year Treasury yields have breached the 5% mark, reaching their highest level since 2007, as investors eagerly await Wednesday’s Federal Reserve meeting. With a rate hike more than 90% priced in, market attention is likely to focus on the accompanying rhetoric. On the macroeconomic front, mixed economic data from China and actions by the PBOC have drawn attention. The People’s Bank of China strengthened the yuan fixing ahead of the Xi-Trump summit scheduled for the end of the month.
📈 Equities
Asian markets are starting the day under slight pressure.
- Nikkei 225: -0,4%
- Shanghai SE Composite: -0,3%
- Hang Seng: -0,5%
- Kospi: -0,5%
Regional indices declined following Monday’s sell-off in semiconductor stocks across global exchanges, triggered by leading AI companies calling for a deceleration in artificial intelligence development to mitigate the risk of losing control over the technology. Nevertheless, the scale of the losses remains relatively modest. The typically volatile Kospi is down 0.5%, while industry giants SK Hynix and Samsung fell 1% and 1.5% respectively. As noted above, the appeal faced sharp criticism from President Trump, further fueling anxiety within the technology sector. Figure 1: Treemap for Nasdaq 100 (14.09.2026)
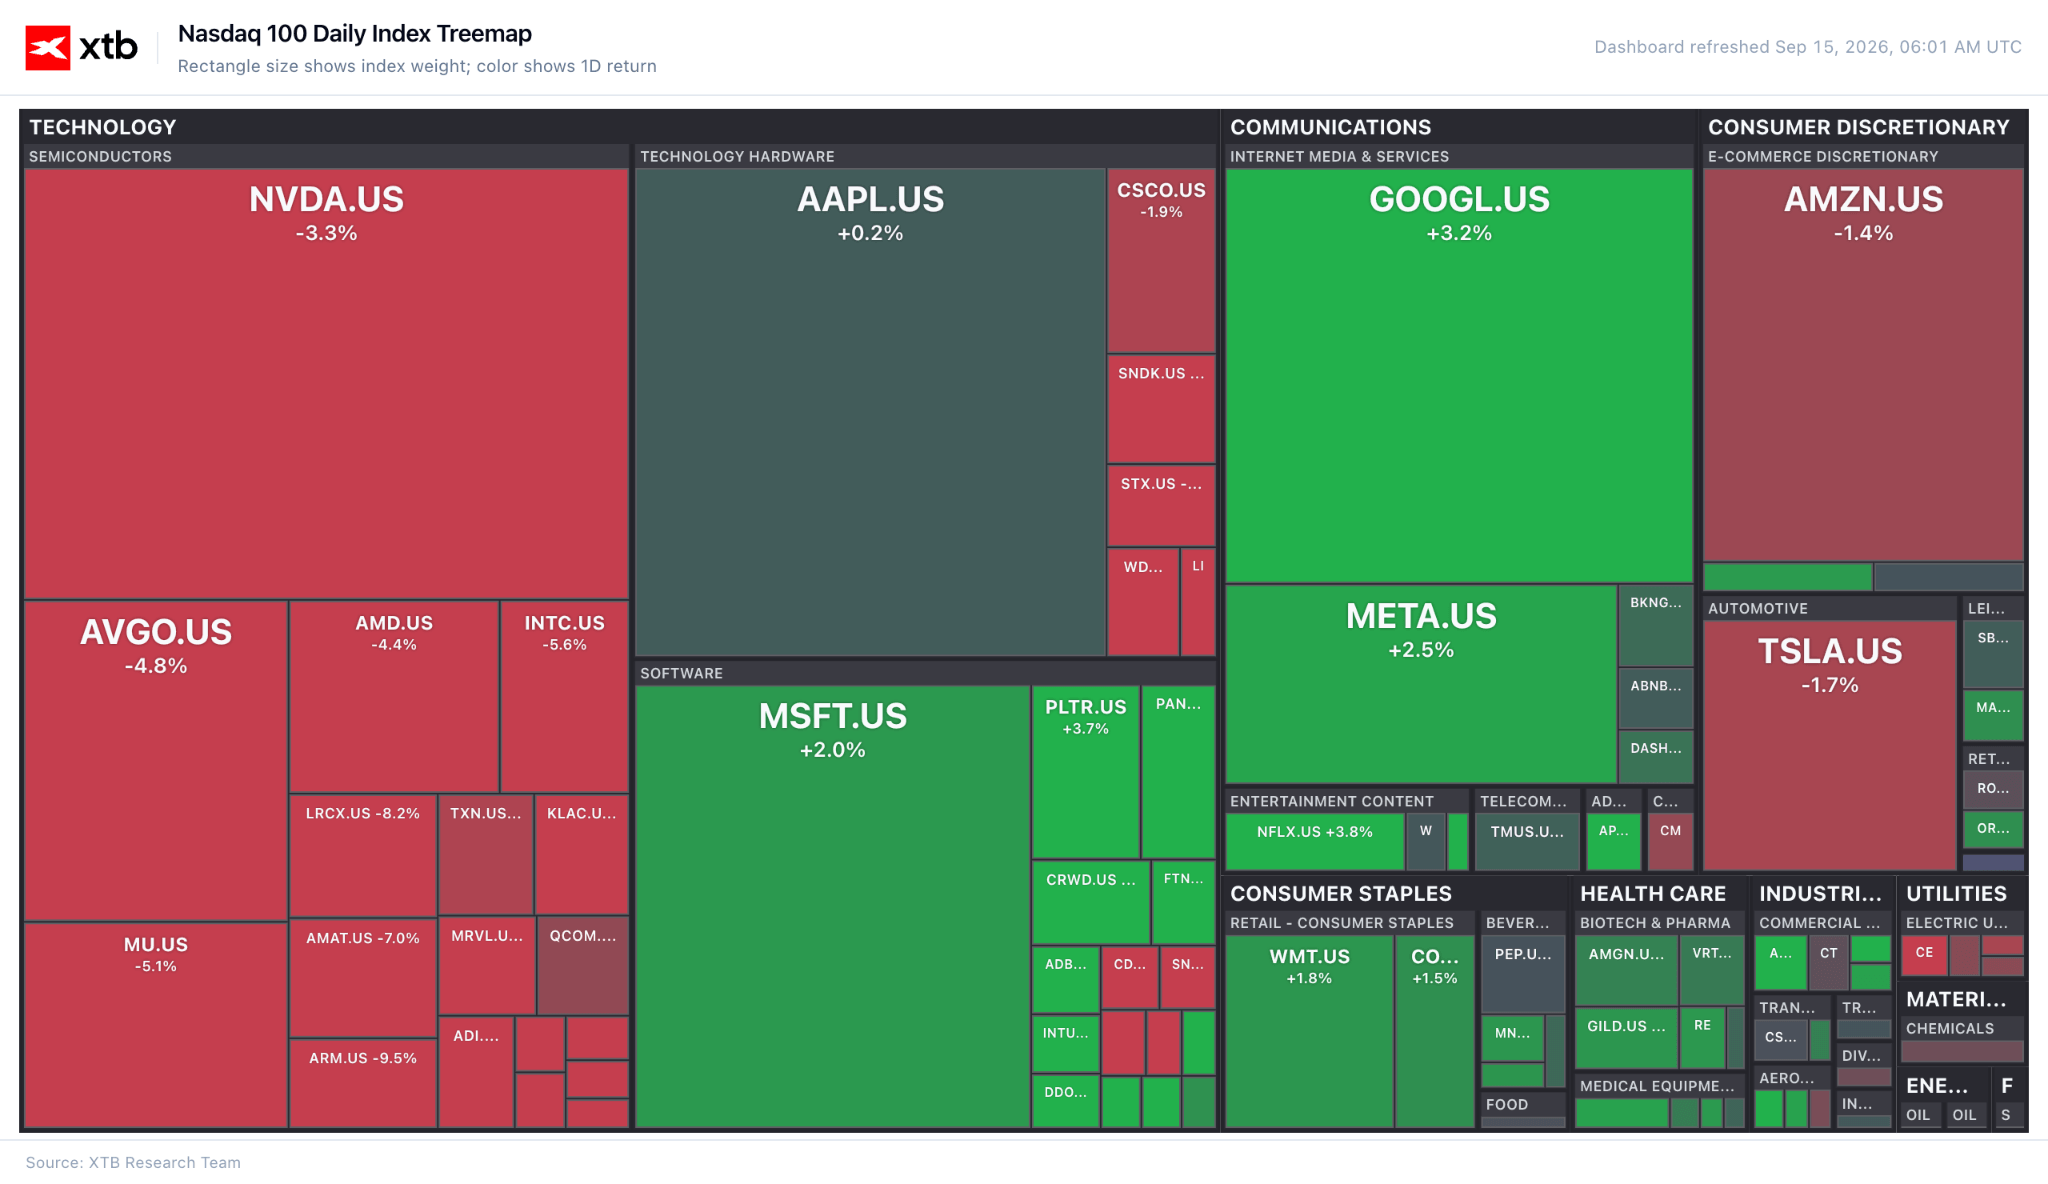
Source: XTB Research, 15.09.2026 In corporate news, SpaceX’s weighting in the Nasdaq 100 index is expected to be increased later this month, which could prompt a wave of buying from passive funds. Meanwhile, Bank of America announced that its third-quarter trading revenue will be flat year-on-year, a statement ill-received by investors. The bank’s shares dropped over 5% yesterday, dragging down the broader banking sector, including in Asia.
🌍 Geopolitics
Tehran, speaking through the secretary of the Supreme National Security Council, Mohsen Rezaee, stated on platform X that talks with Washington are out of the question until Iran’s conditions are met. This contrasts with earlier remarks from President Trump, who suggested a potential breakthrough, asserting that Iran was keen to reach a swift agreement. Meanwhile, US forces maintain their blockade of Iranian ports, increasing pressure on Tehran. The Islamic Revolutionary Guard Corps Navy reported an explosion aboard an oil tanker that allegedly struck a mine while attempting to navigate a restricted zone in the southern Strait of Hormuz. US Central Command denied these reports. Tensions in the Middle East are also being stoked by Iranian-backed Houthi forces, who launched missile and drone attacks on civilian targets in the Saudi cities of Khamis Mushait, Abha, and Taif on Monday. Regarding the Russia-Ukraine war, Trump claims that Moscow and Kyiv have agreed to halt attacks on energy infrastructure. President Zelenskyy has denied that any such agreement has been finalised.
🛢️ Commodities
Oil prices are advancing for a second consecutive session. Brent crude is trading above $107 per barrel, while WTI is hovering near $103. The move is driven partly by the shutdown of Saudi Arabia’s East-West Pipeline, which served as an alternative route to transporting oil through the Strait of Hormuz. Figure 2: Brent & WTI Crude Oil (2026)
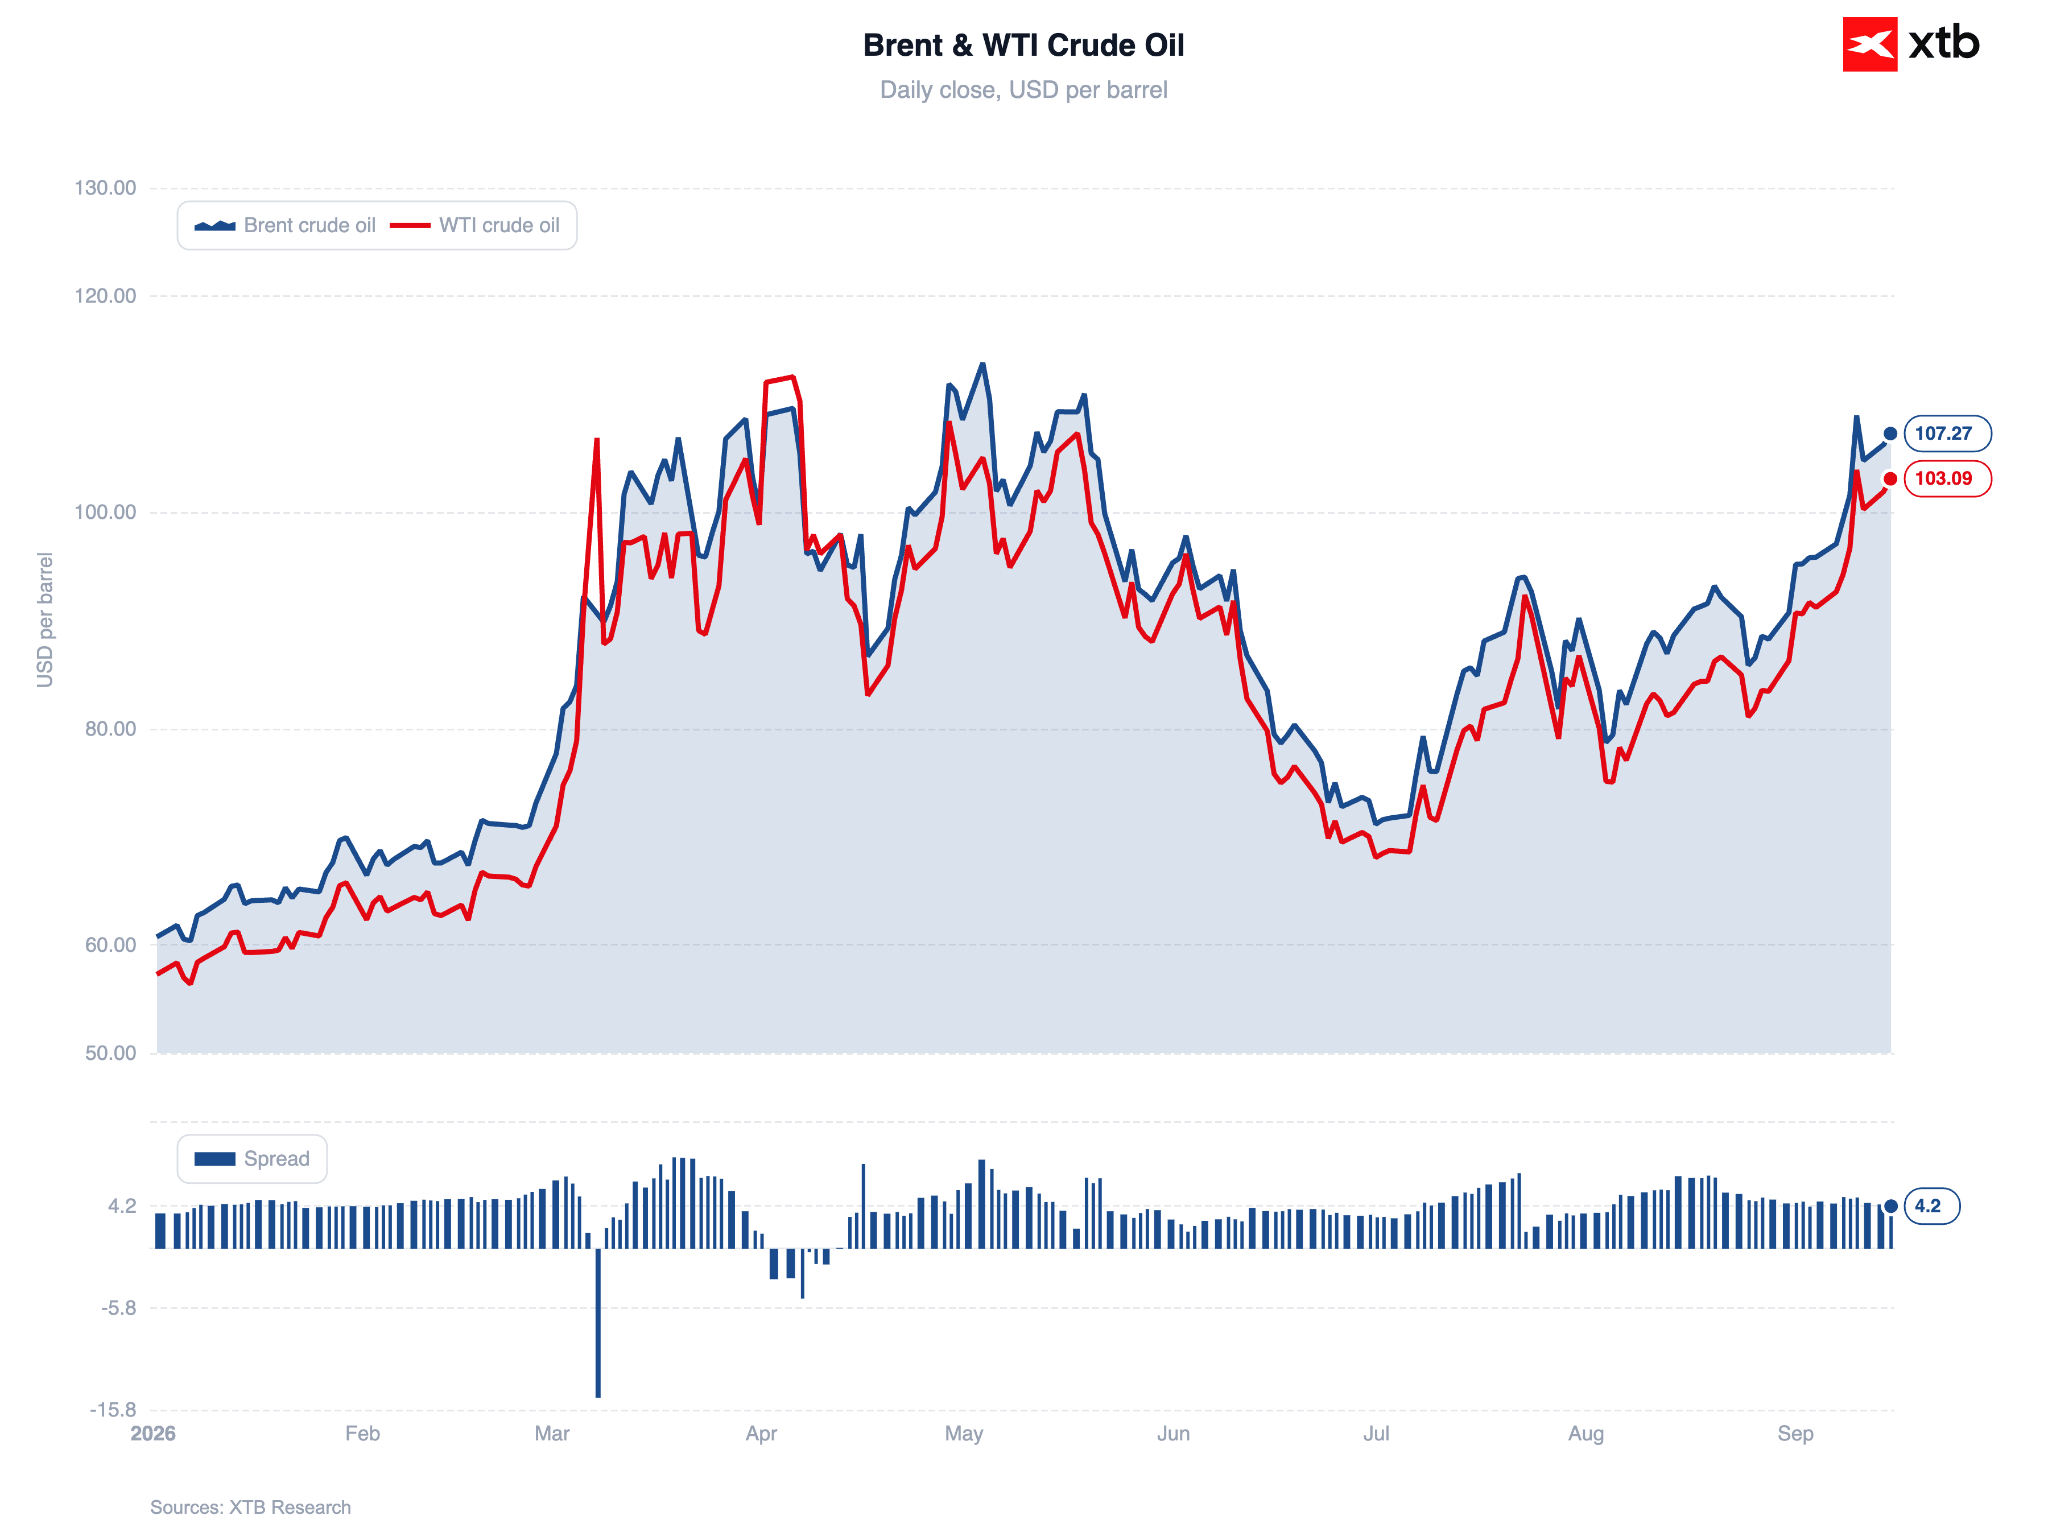
Source: XTB Research, 15.09.2026 Saudi Aramco has not yet provided a timeline for resuming throughput. According to an Associated Press report citing regional officials, the facility could remain out of service for several weeks.
🪙 Precious metals
Gold is holding near $4,300 per ounce after falling more than 1% in the previous session to a five-week low. The precious metal remains under pressure from the rising likelihood of a Fed interest rate hike, which the market now prices at over 90%. Figure 3: Gold Price and US 10Y Yield [Inverted Axis] (2026)
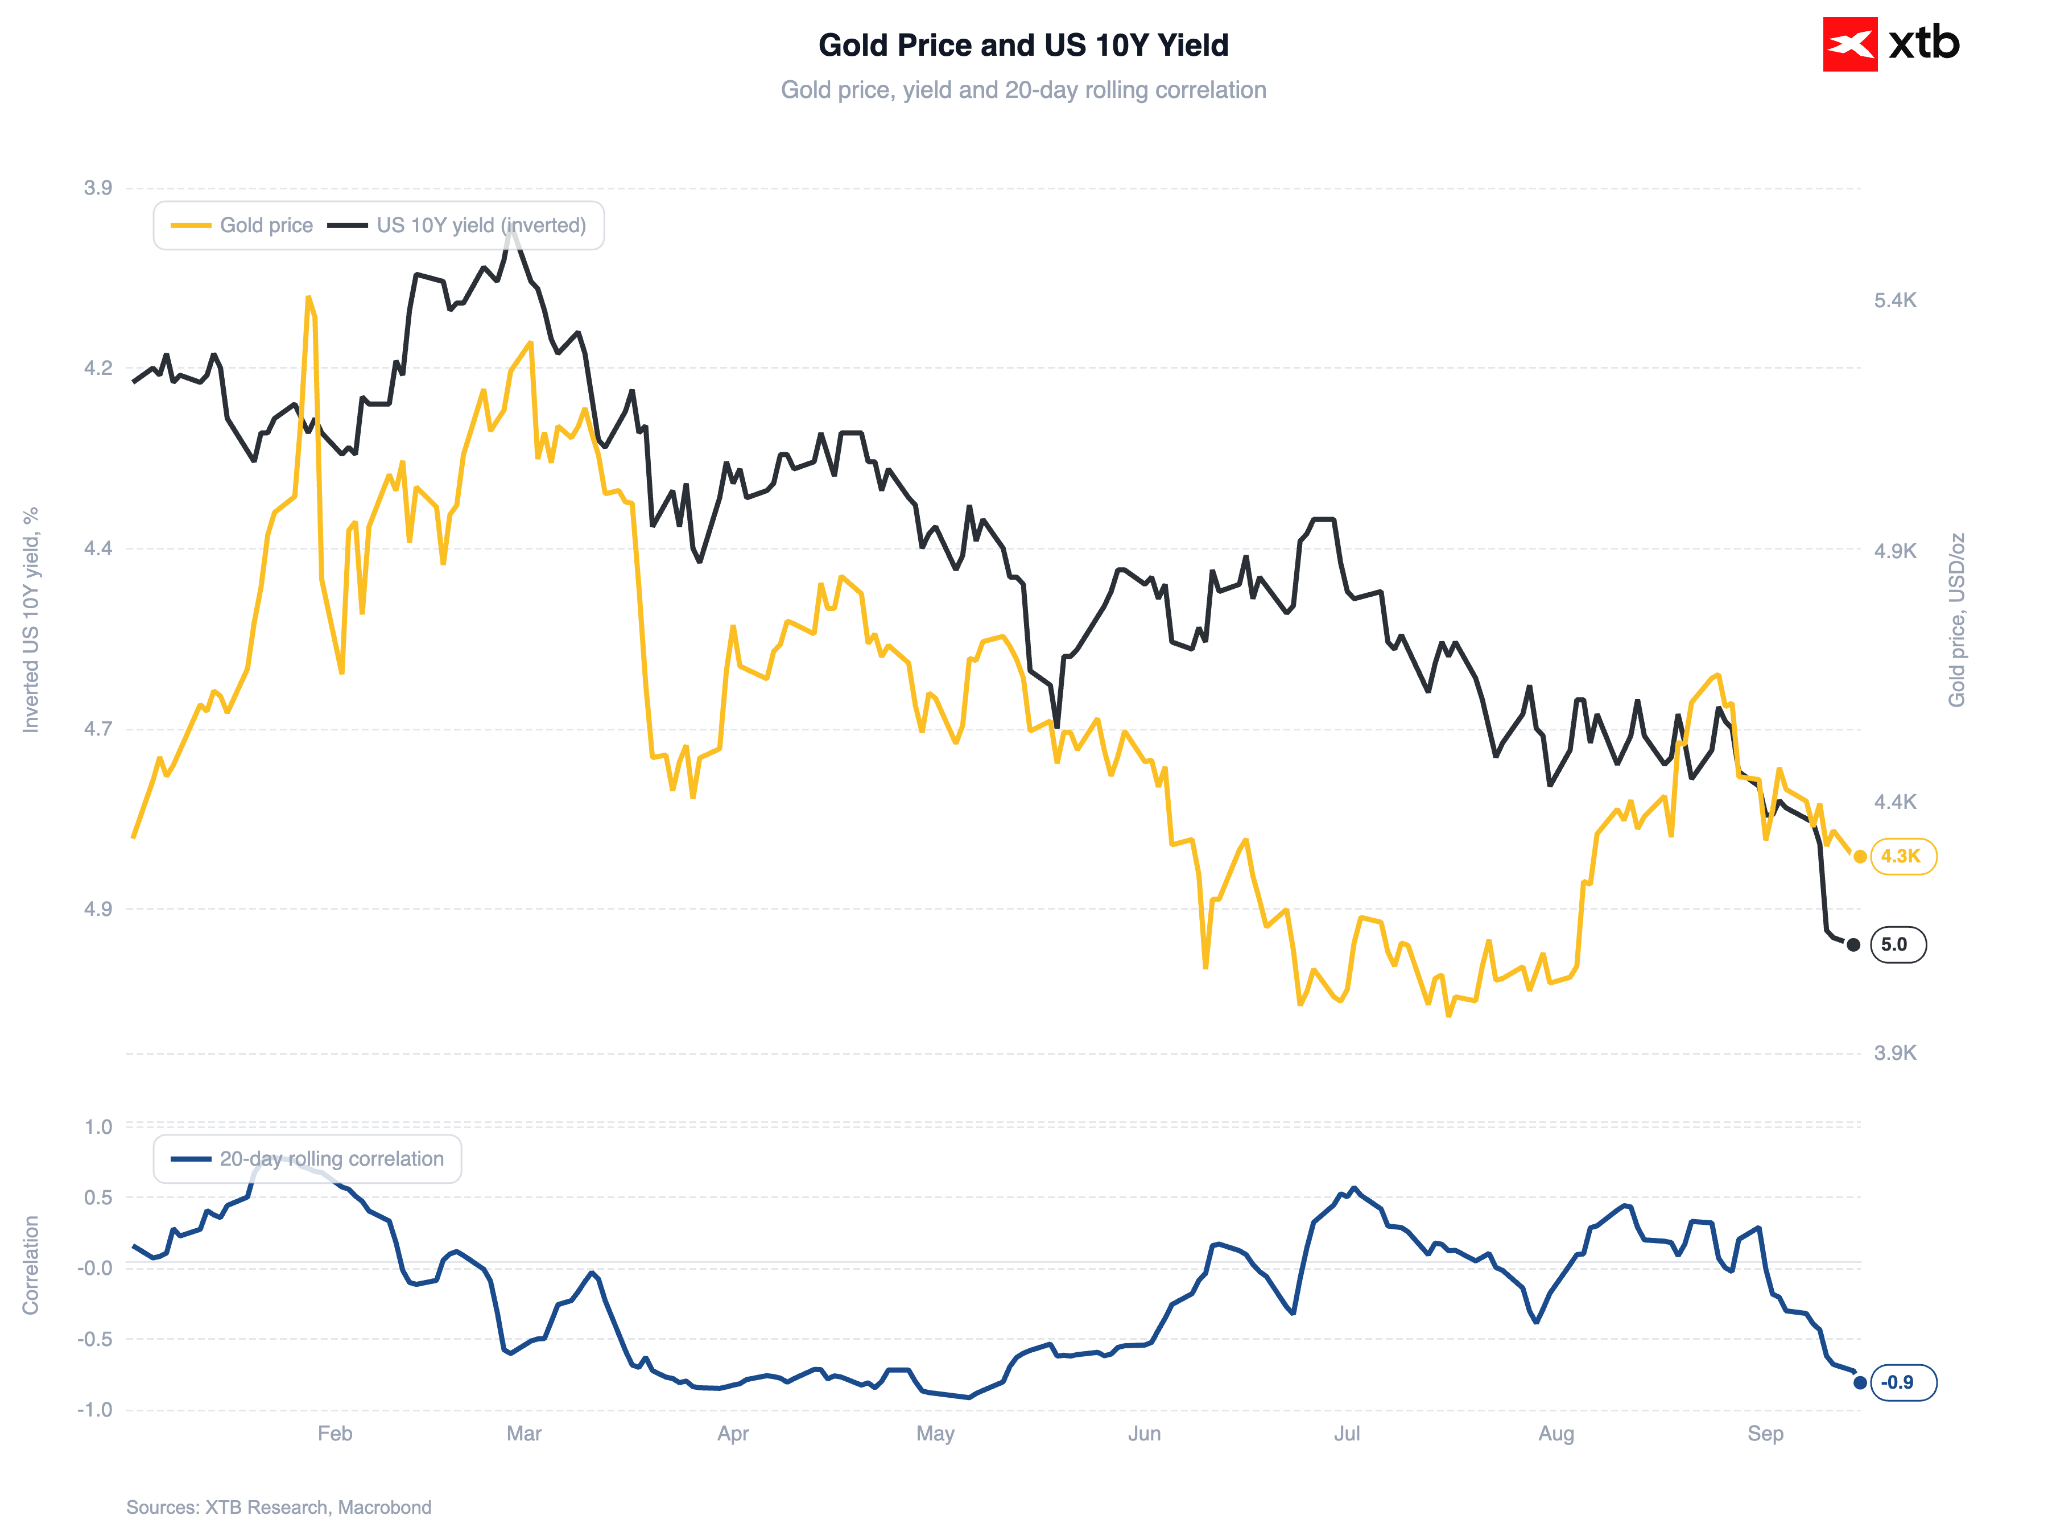
Source: XTB Research, 15.09.2026 The precious metal is currently trading more than 3% below its late-August peaks, when prices exceeded $4,700. Wednesday’s Fed decision and accompanying tone could prove crucial for its trajectory. Any concerns regarding central bank independence might trigger a return of the “debasement trade”, driving a shift from fiat currencies into hard assets.
📈 Macroeconomic Data and Monetary Policy
US 10-year Treasury yields broke through the psychological 5% barrier on Monday, reaching 5.03%, their highest level since 2007. This was driven by a combination of surging oil prices, inflation concerns, and expanding sovereign and corporate debt, including funding for massive AI investments. Some analysts warn that yields in the 5.00–5.25% range could start placing a heavy drag on equity valuations. Markets have almost fully priced in a rate hike at Wednesday’s FOMC meeting. A failure to act this week could undermine central bank credibility and spur a further rise in long-term yields. Current market pricing implies another rate hike in December, followed by two more by October 2027. Figure 4: Fed Implied Policy Path (Hikes/Cuts) (2026 – 2027)
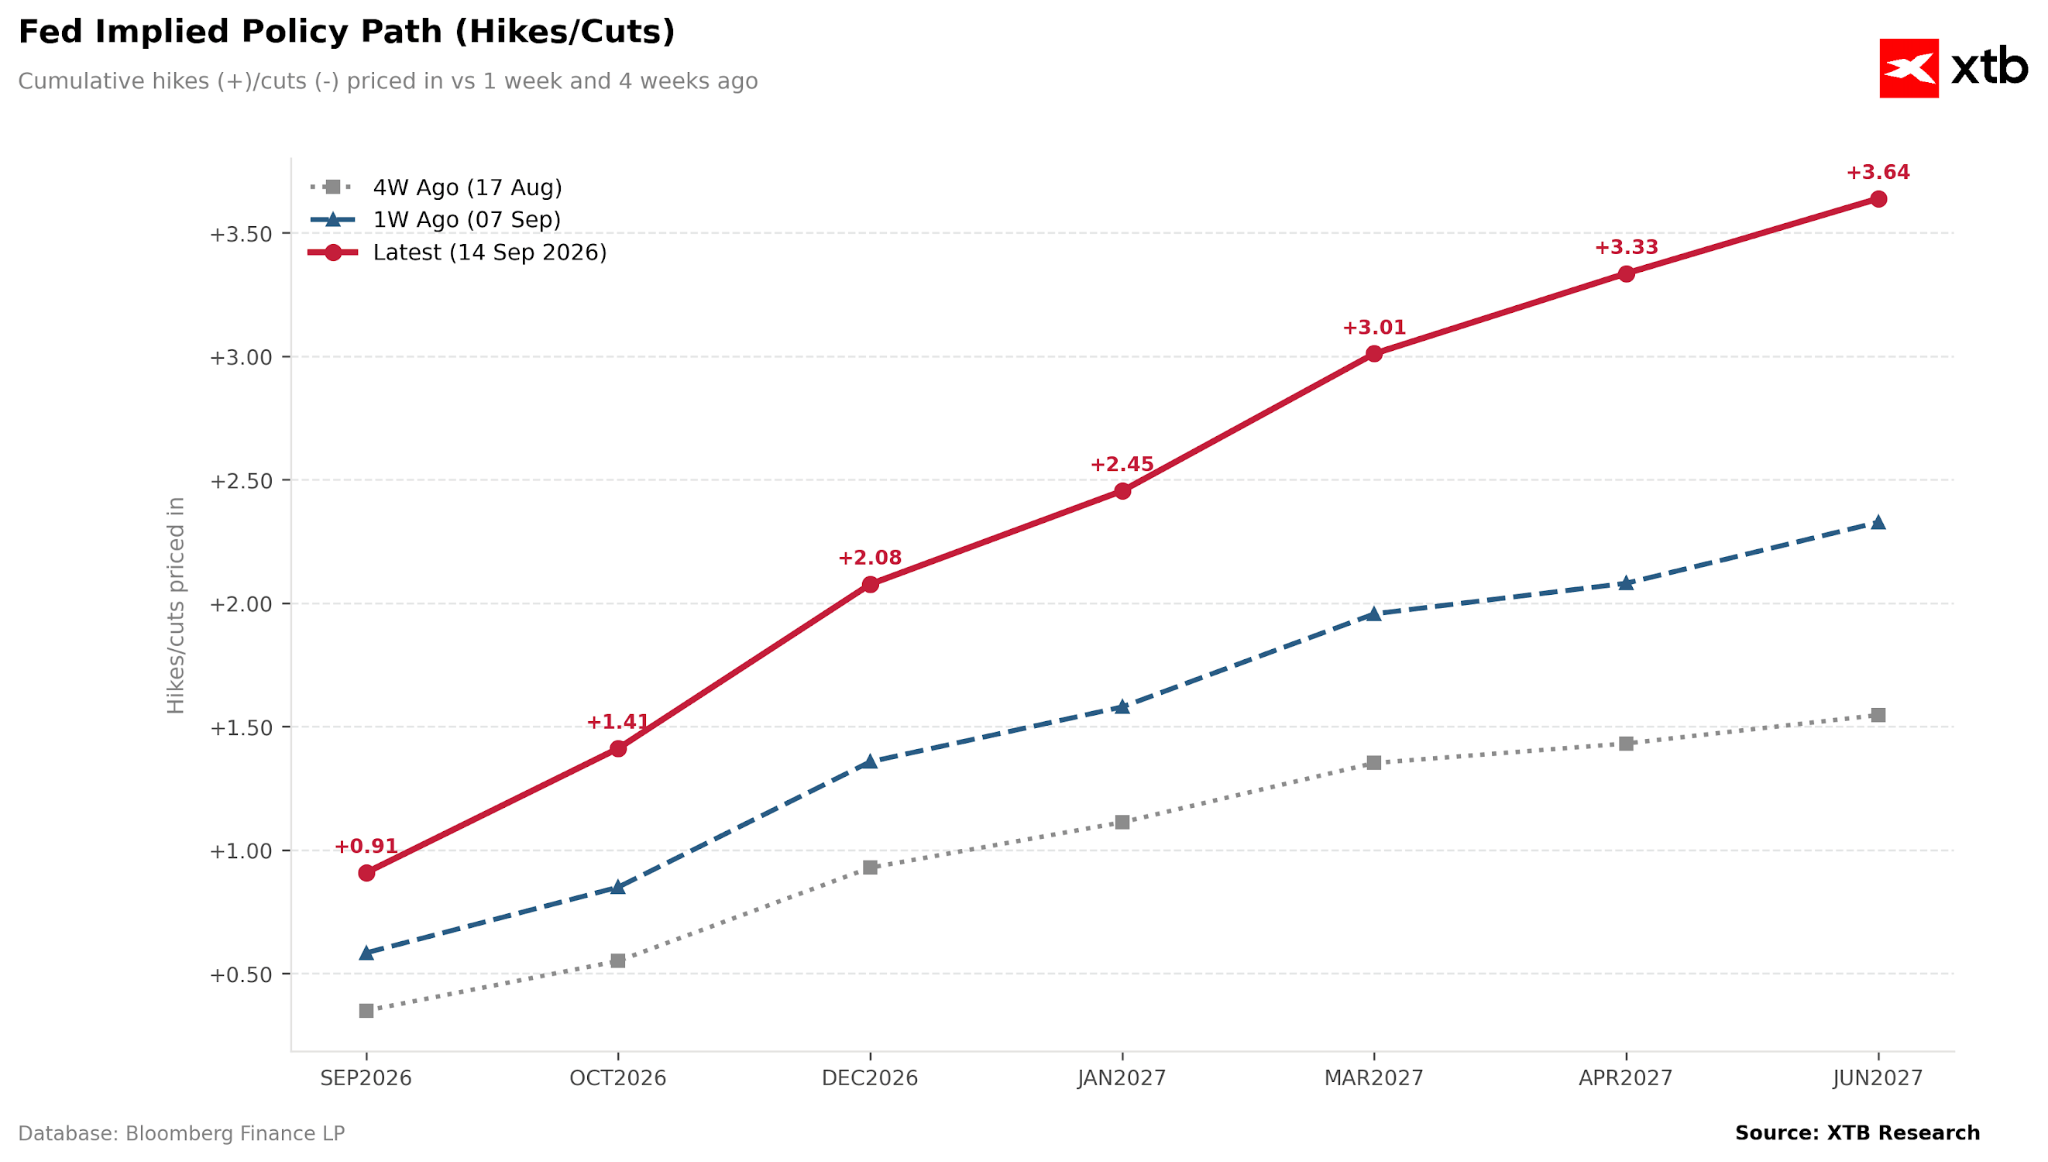
Source: XTB Research, 15.09.2026
August economic data from China painted a mixed picture. Industrial production surprised to the upside, growing 5.2% YoY (versus 4.8% expected) compared to 4.5% in July, driven primarily by double-digit export growth fueled by demand for AI-related components. Conversely, retail sales rose by just 0.4% YoY, missing the 0.8% forecast and slowing from July, while fixed-asset investment contracted further to -7.2% year-to-date. Urban unemployment unexpectedly rose to 5.3% from 5.2%. The main drag on Chinese consumption remains the automotive market, where car sales plunged 18.5% YoY in August following the expiration of government subsidies. Excluding vehicles, retail sales grew by 2.5%, matching July’s pace. Meanwhile, real estate investment has contracted 19.9% year-to-date. The People’s Bank of China set Wednesday’s yuan fixing at 6.7670 per dollar, strengthening the currency for a fifth consecutive day, its longest rally since December 2025. The move aligns with a strategy to curb exchange-rate volatility ahead of the summit between Presidents Xi Jinping and Donald Trump on 24 September.
💱 Currencies The dollar continues to strengthen following Monday’s performance, when it posted its largest daily gain in over two months. The yen recovered some losses during morning trading, with USD/JPY approaching the psychological 155 level. ₿ Cryptocurrencies Cryptocurrencies remain under pressure from rising yields and a firmer US dollar. Bitcoin is down around 2%, slipping below $77,500, while Ethereum fell 3% to just under $2,490.