S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

The era of high interest rates will be back for good—and what does that mean for stocks

The interest rate market has undergone a quiet but dramatic transformation in recent weeks. Just a month ago, investors were pricing in a moderate normalisation of monetary policy; today, the implied yield curves for most major economies paint a very different picture: a series of significant rate rises spread over the coming quarters.
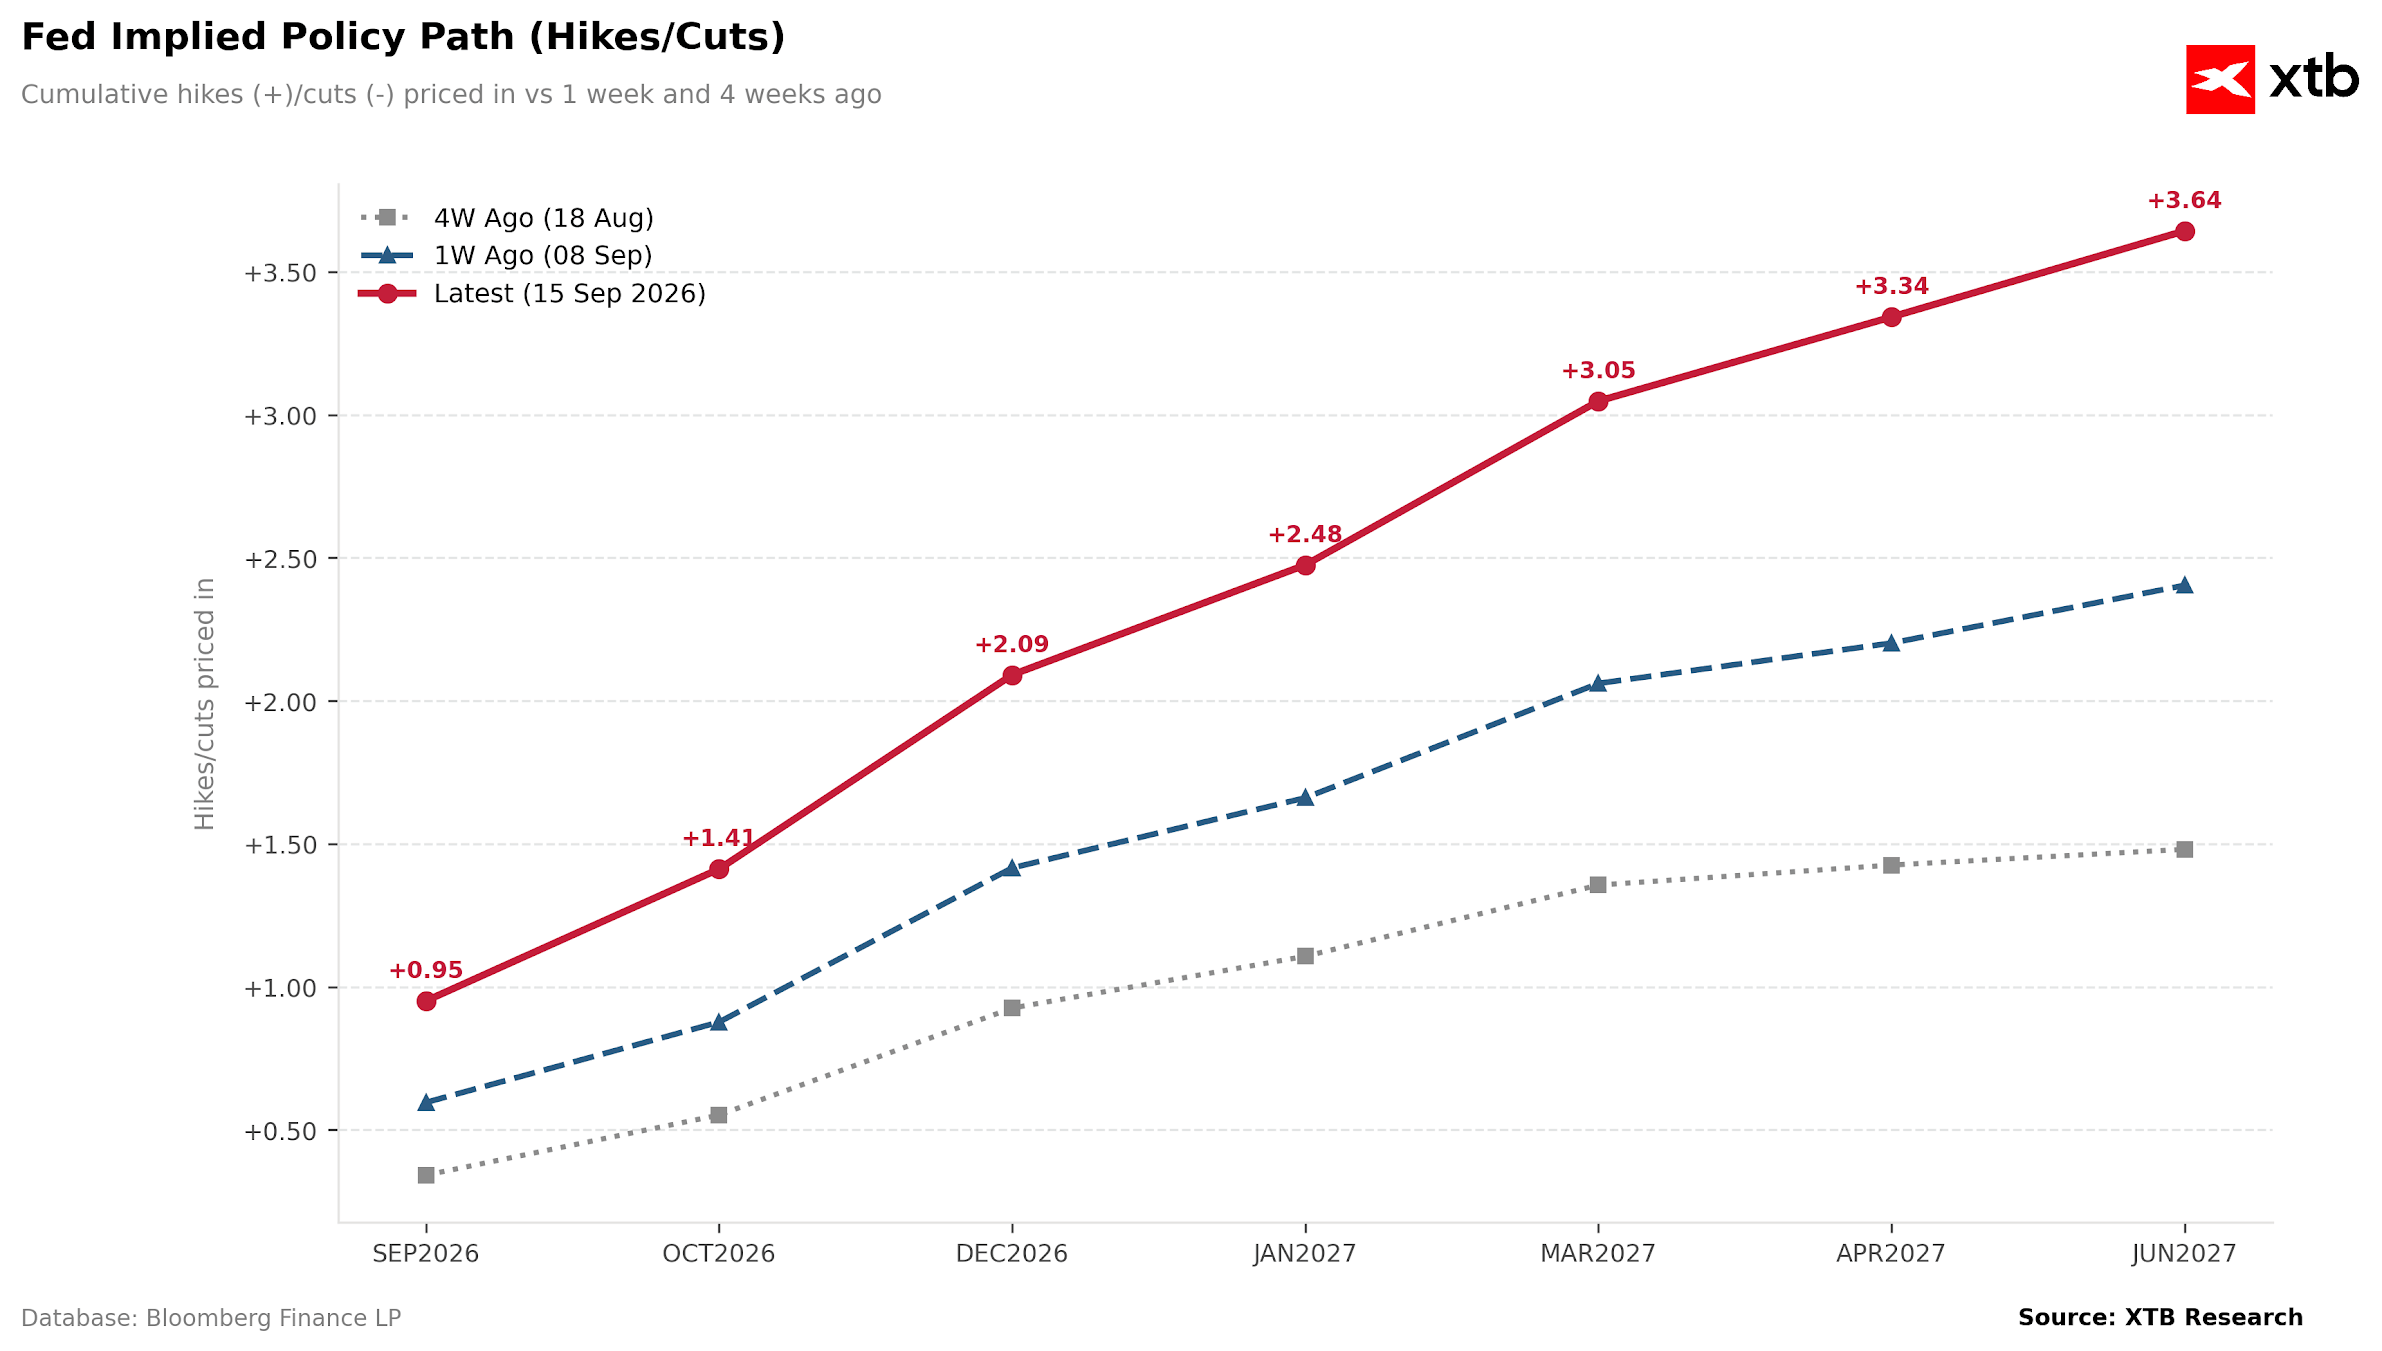
This is most clearly evident in the Fed’s rate path. Futures are currently pricing in a cumulative total of +3.64 rate rises through to June 2027, whereas a week ago the figure was just +2.40, and four weeks ago a mere +1.49. The red line has literally broken away from the rest of the chart, which means that the market is rapidly bringing forward the tightening schedule to earlier months. A similar picture is emerging in the eurozone, where the ECB is priced in at +3.73 by mid-2027… Source: XTB Research
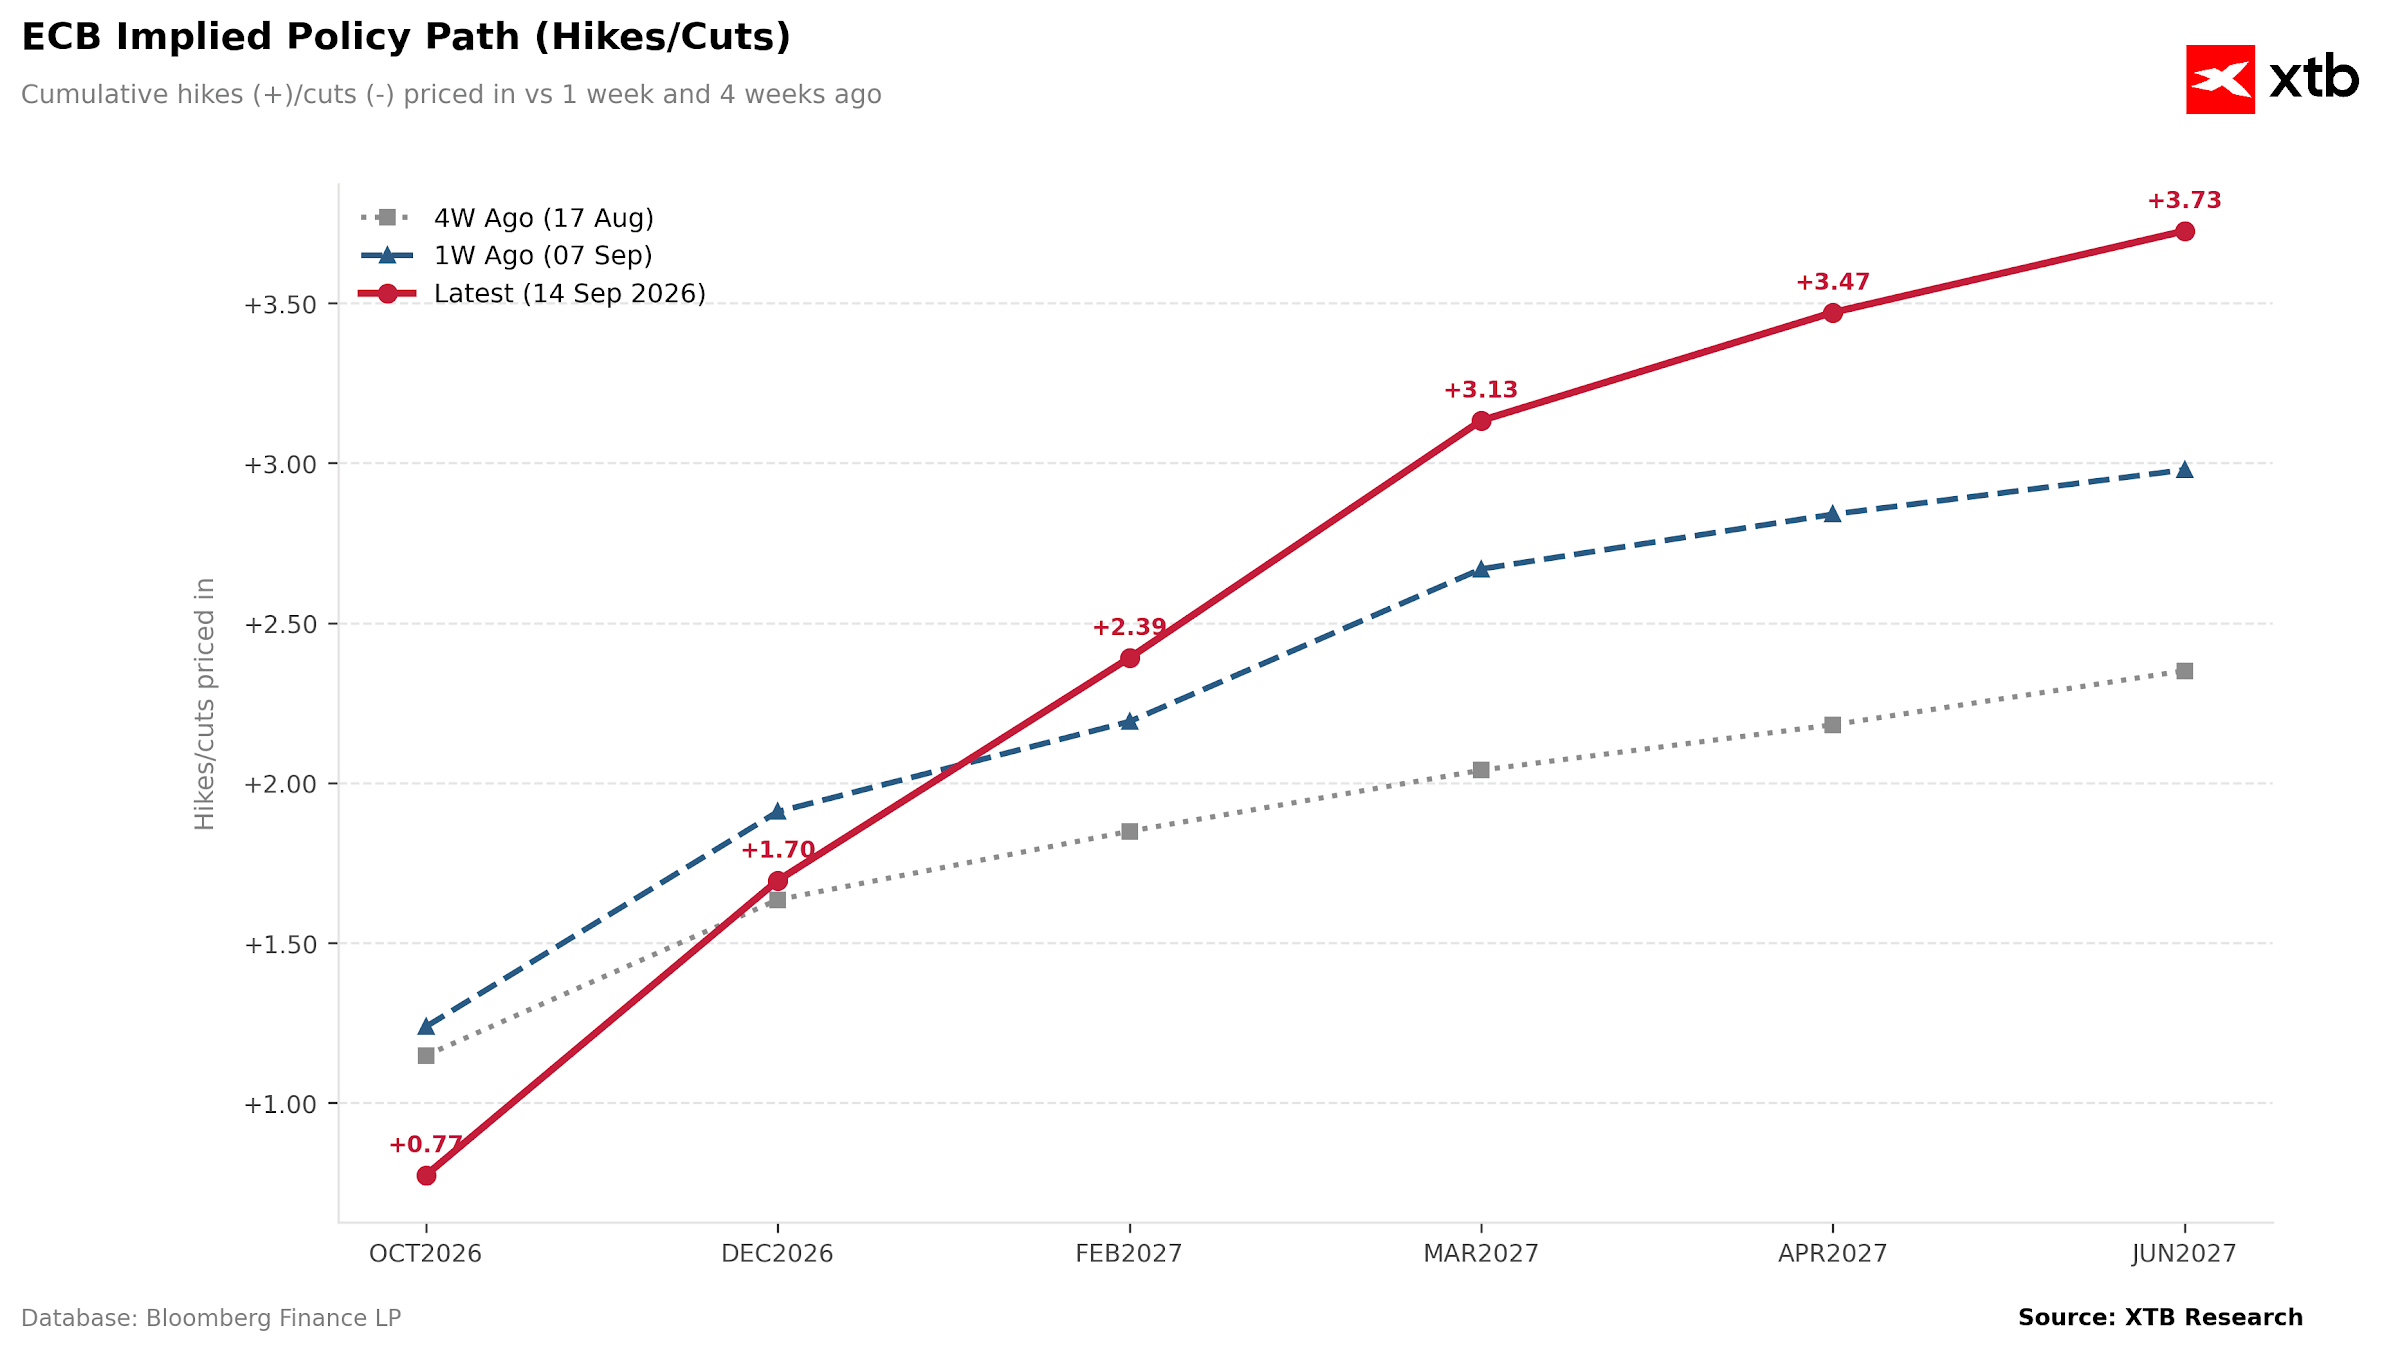
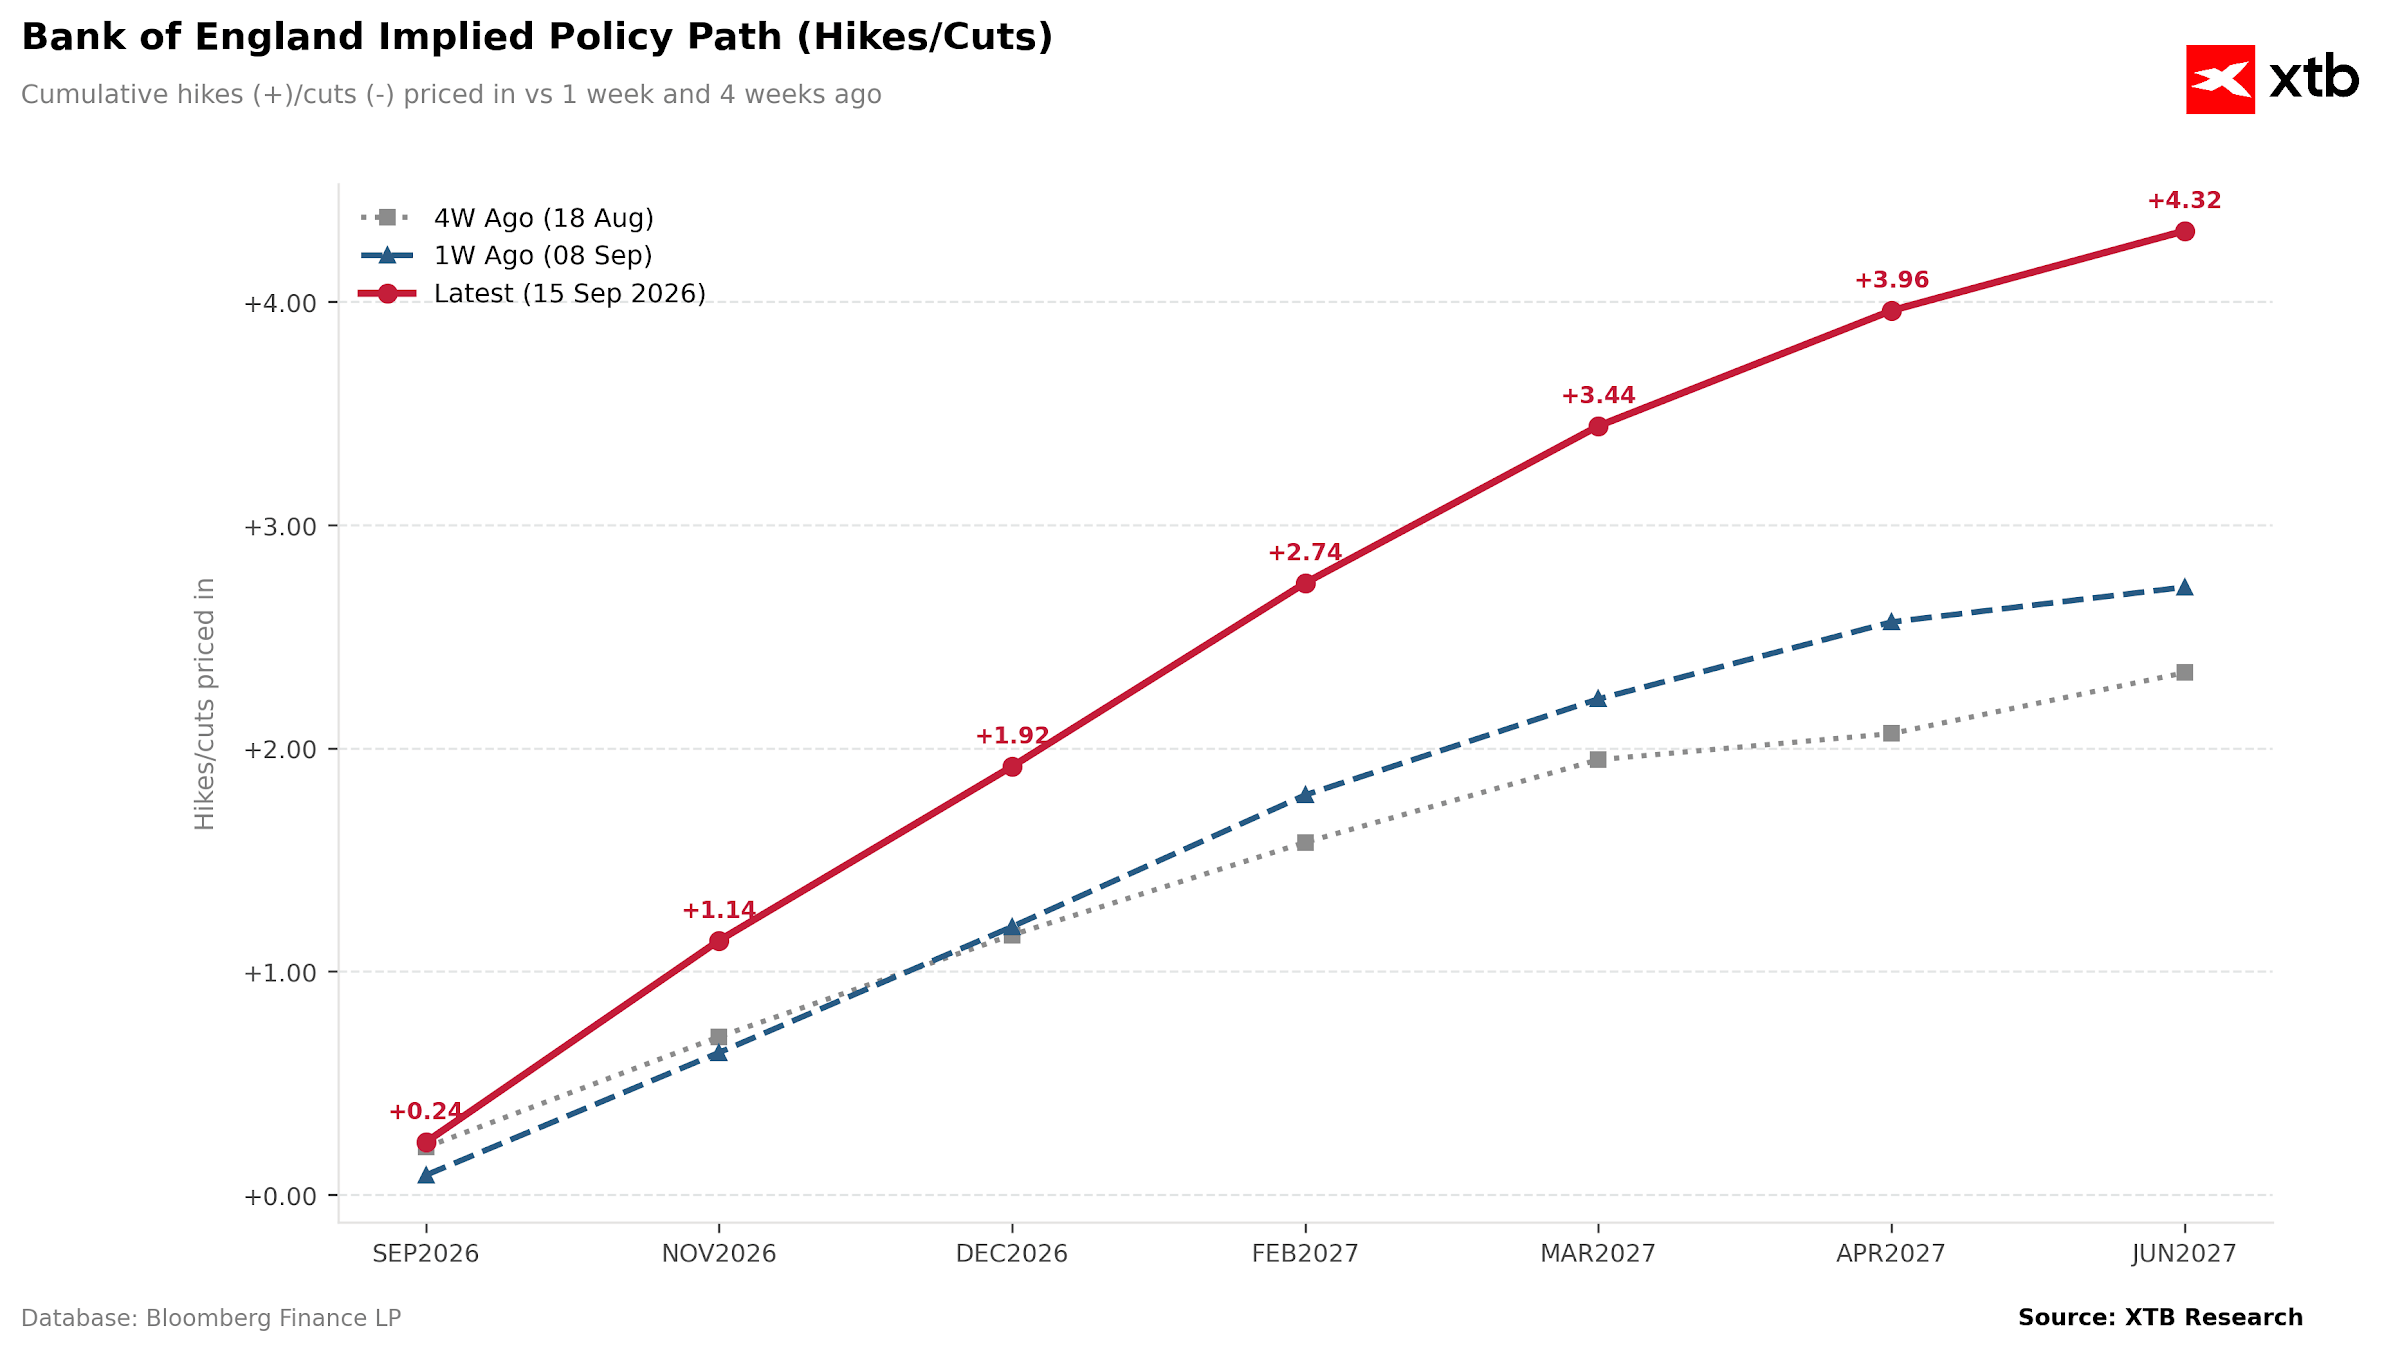
and in the UK, where the Bank of England is outperforming everyone else with a reading of +4.32. In other words, this is not just the story of one central bank, but a global turnaround. Source: XTB Research
Source: XTB Research This is, in fact, confirmed by a regional review. Implied annual rates are rising virtually everywhere, from the US and Canada, through most EMEA markets, to Australia, New Zealand and Korea, with annual changes of 100 basis points or more. Exceptions, such as Brazil and China, merely prove the rule. The market is sending a clear message: money will be expensive again, and for the long term.
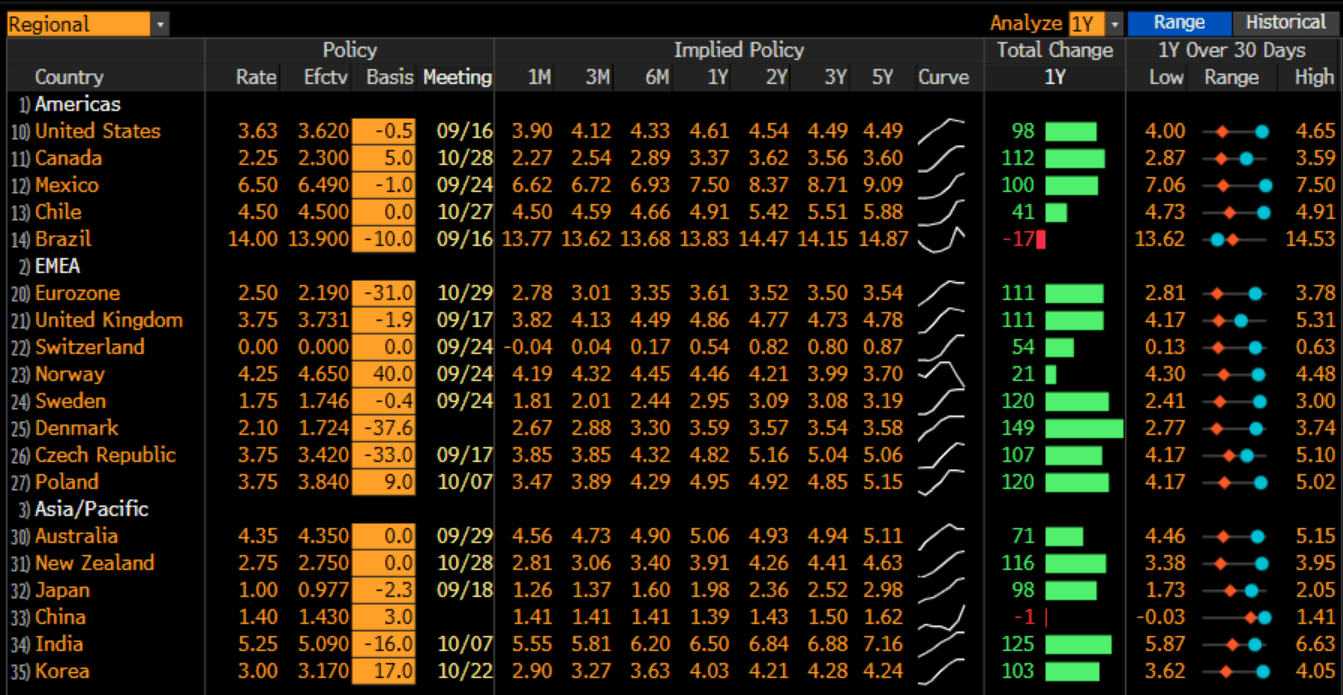
Source: Bloomberg Financial Lp What’s behind this turnaround? It is most likely due to persistent inflation in services and fuel prices, as well as stronger-than-expected labour market data. Central banks today would rather err on the side of caution than lose control once again over price expectations fuelled by the conflict between Russia and Ukraine; the US-Iran conflict (and other countries in the region) just before the winter season. The question every manager asks themselves is: what does this mean for the stock markets? History suggests that higher interest rates over a prolonged period create an environment that is rather unfavourable for shares, particularly growth shares, as they raise the discount rate and set the bar higher for valuations. But the reaction need not be dramatic. Markets can cope with expensive money, provided it is accompanied by decent earnings growth, and it is precisely this scenario – a strong economy forcing higher rates – that is much easier to swallow than the stagflationary alternative.
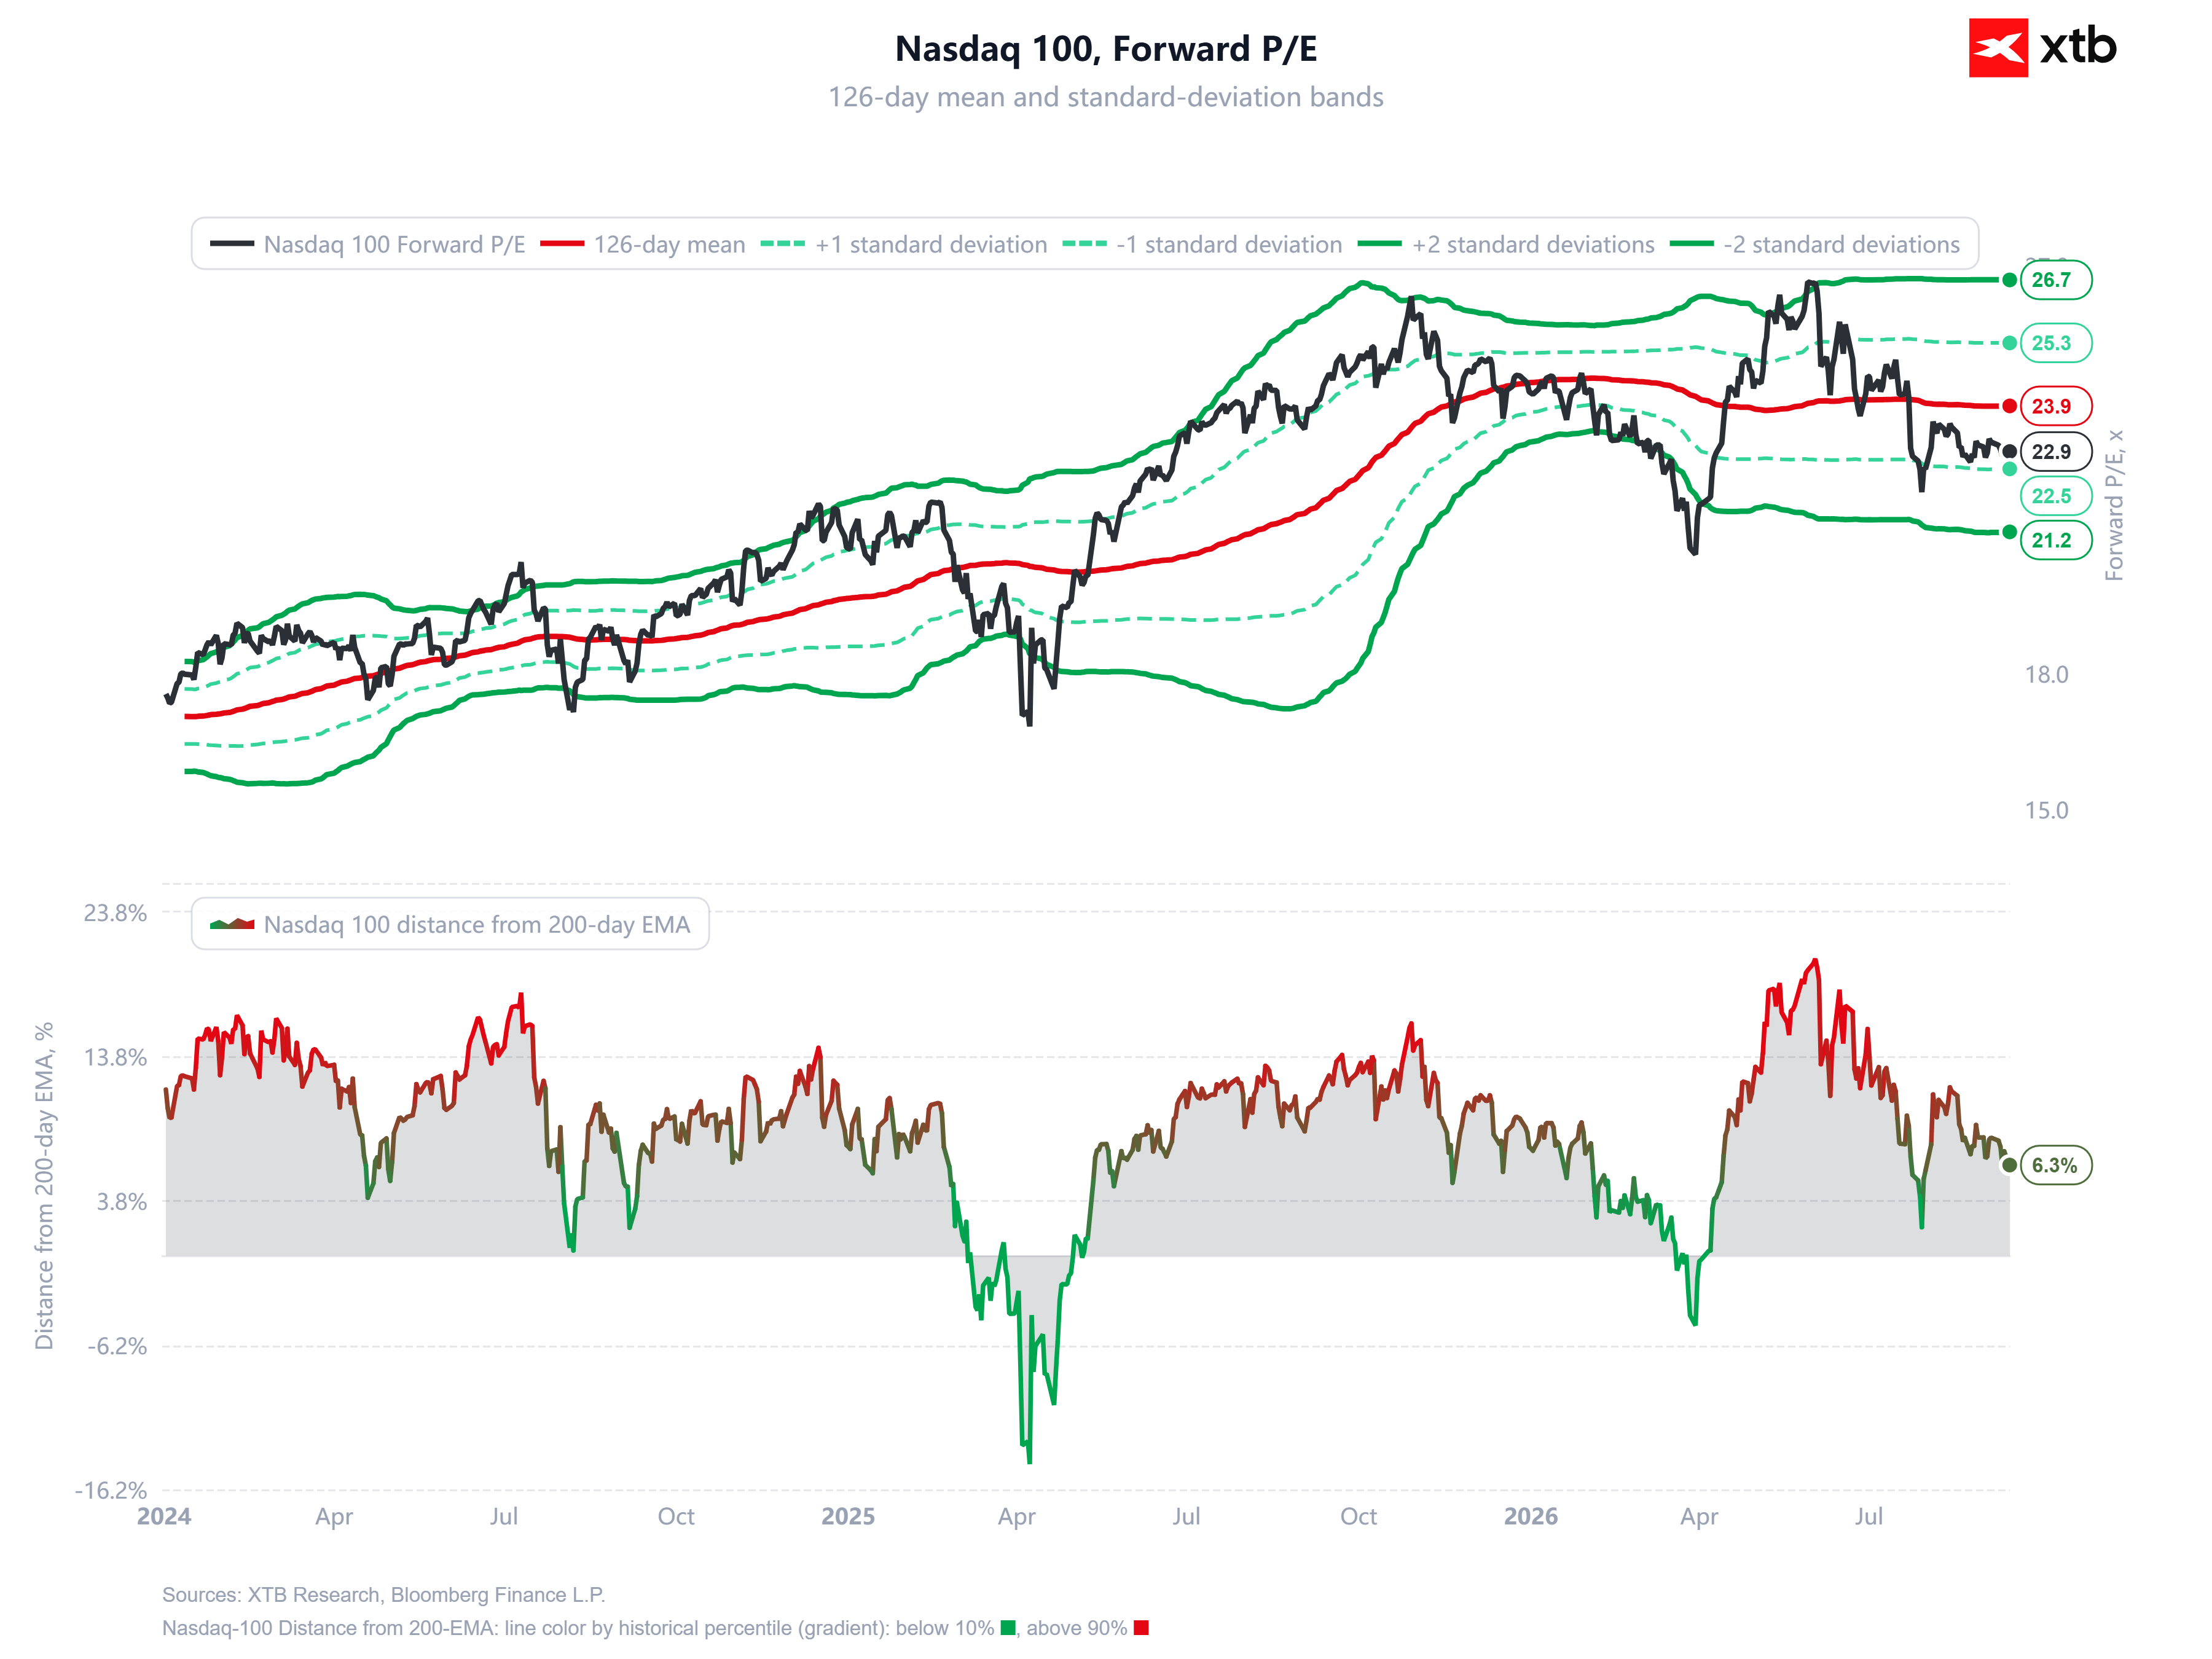
Interestingly, valuations are not sky-high at the moment. The forward P/E for the Nasdaq 100 stands at 22.9, which is below the 126-session average of 23.9 and roughly at the lower standard deviation. This is a significant nuance: the technology benchmark, a symbol of the era of cheap money, is entering a potentially more challenging interest rate environment without a valuation bubble hanging over it. The deviation from the 200-session moving average stands at a moderate 6.3 per cent, so it is hard to speak of euphoria. Source: XTB Research The conclusion? If the market is right and we are indeed returning to a world of high interest rates, the stock markets will probably weather this without disaster, albeit with greater volatility and more pronounced stock selection. Expensive money punishes speculation whilst rewarding quality and real profits. And the relatively subdued valuations on the Nasdaq suggest that part of this more challenging scenario is already priced in.