S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

U.S. grains and soybeans start the week with a solid rebound on Chicago Board of Trade (CBOT). Futures climbed at the start of the week, recovering from recent significant declines. Soybeans in particular bounced sharply after being heavily oversold in the previous sessions. Broad-based buying was fueled by commodity funds, which were net buyers of corn, soybeans, and wheat contracts. This renewed investment demand supported price recovery across the grain market.
- Global supply remains ample – Argentina and Australia are finishing record wheat harvests, while Brazil is starting a forecasted record soybean crop. This limits the potential for sustained strong rallies despite the short-term rebound.
- U.S. corn stocks – last year’s record corn harvest was largely offset by robust exports, keeping inventories at moderate levels and mitigating downward pressure on prices.
- Upcoming USDA report – the December 1 stock report, due January 12, could be a key market driver. Lower-than-expected figures would likely support further gains in grain and soybean contracts.
- Export optimism for soybeans – rumors of additional Chinese purchases, particularly by Sinograin, boosted market sentiment, reinforcing confidence in U.S. export demand.
- Weather risks – dry forecasts for Argentina could add a premium to corn and soybean prices if they threaten yields. Meanwhile, Brazil’s rainfall remains adequate, posing no immediate risk to the crop.
- Corn remains range-bound – despite the rebound, corn prices are still moving sideways, awaiting fresh catalysts such as the WASDE report to trigger a breakout.
- Wheat supported by weather and geopolitics – dry conditions in the U.S. Great Plains and tensions in the Black Sea export corridor are limiting supply and supporting prices. Russia’s recent attacks on Ukraine, including Bunge’s facilities in Dnipro, reduced exports from 3.58 to 3.28 million tons in December, reinforcing the market’s upside potential.
- Export sales data – U.S. corn net export sales fell to the lowest since September (756,000 tons), while soybean sales rose 27% week-over-week (1.24 million tons), reflecting differentiated global demand dynamics.
The grain market is in a corrective rebound phase after year-end lows. Prices are supported by local weather constraints and geopolitical risks, but ample global supplies remain a significant ceiling on a sustained uptrend.
Wheat, Soybean and Corn Charts (H1)
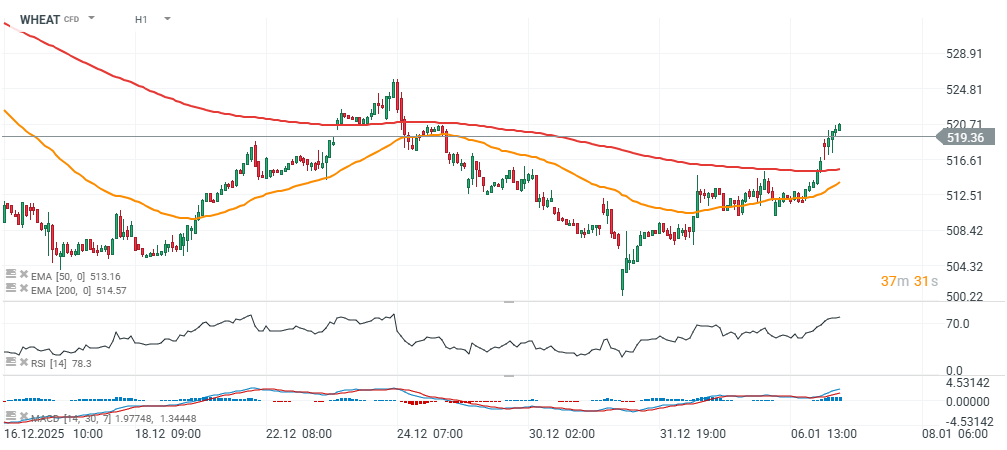
Source: xStation5
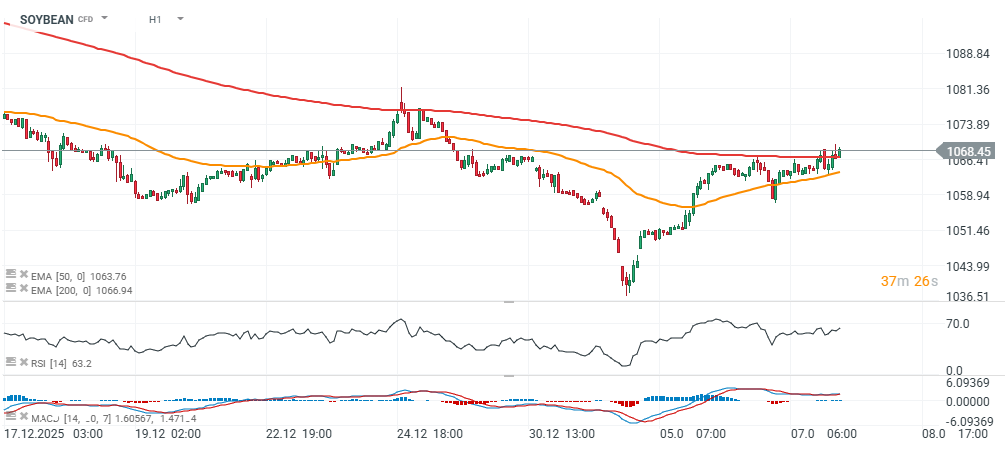
Source: xStation5
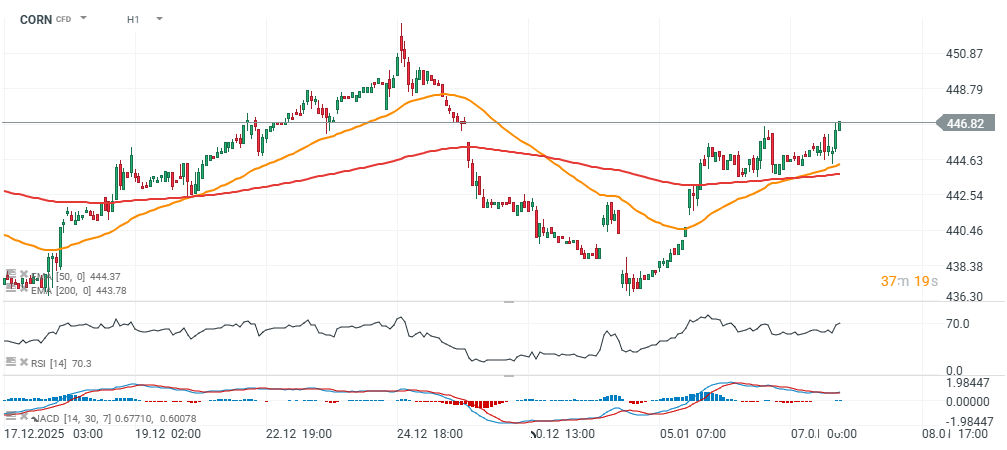
Source: xStation5
The material on this page does not constitute financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other specific needs. All information provided, including opinions, market research, mathematical results and technical analyzes published on the Website or transmitted To you by other means, it is provided for information purposes only and should in no way be construed as an offer or solicitation for a transaction in any financial instrument, nor should the information provided be construed as advice of a legal or financial nature on which any investment decisions you make should be based exclusively To your level of understanding, investment objectives, financial situation, or other specific needs, any decision to act on the information published on the Website or sent to you by other means is entirely at your own risk if you In doubt or unsure about your understanding of a particular product, instrument, service or transaction, you should seek professional or legal advice before trading. Investing in CFDs carries a high level of risk, as they are leveraged products and have small movements Often the market can result in much larger movements in the value of your investment, and this can work against you or in your favor. Please ensure you fully understand the risks involved, taking into account investments objectives and level of experience, before trading and, if necessary, seek independent advice.