Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
MarketsStocksTechnical Analysis

CoreWeave: Record Demand Collides with Crushing Costs

CoreWeave remains one of the clearest examples of the contradictions driving the artificial intelligence market. The cloud computing provider is rapidly growing revenue and securing multi year contracts, yet infrastructure expansion is consuming capital faster than the business can generate it. For investors, the pressing question is how much AI value accrues to shareholders, and how much goes to hardware suppliers or lenders.

Financials

  • CoreWeave’s revenue in the second quarter of 2026 increased by 112% year over year to USD 2.58 billion.
  • The company raised its full year sales forecast to USD 12.4 to 13.2 billion.
  • The backlog of contracted future revenue reached around USD 104 billion, and in early Q3 the company additionally secured more than USD 25 billion in new customer commitments.

Demand is strong, but the company still remains extremely inefficient at converting orders into profits.
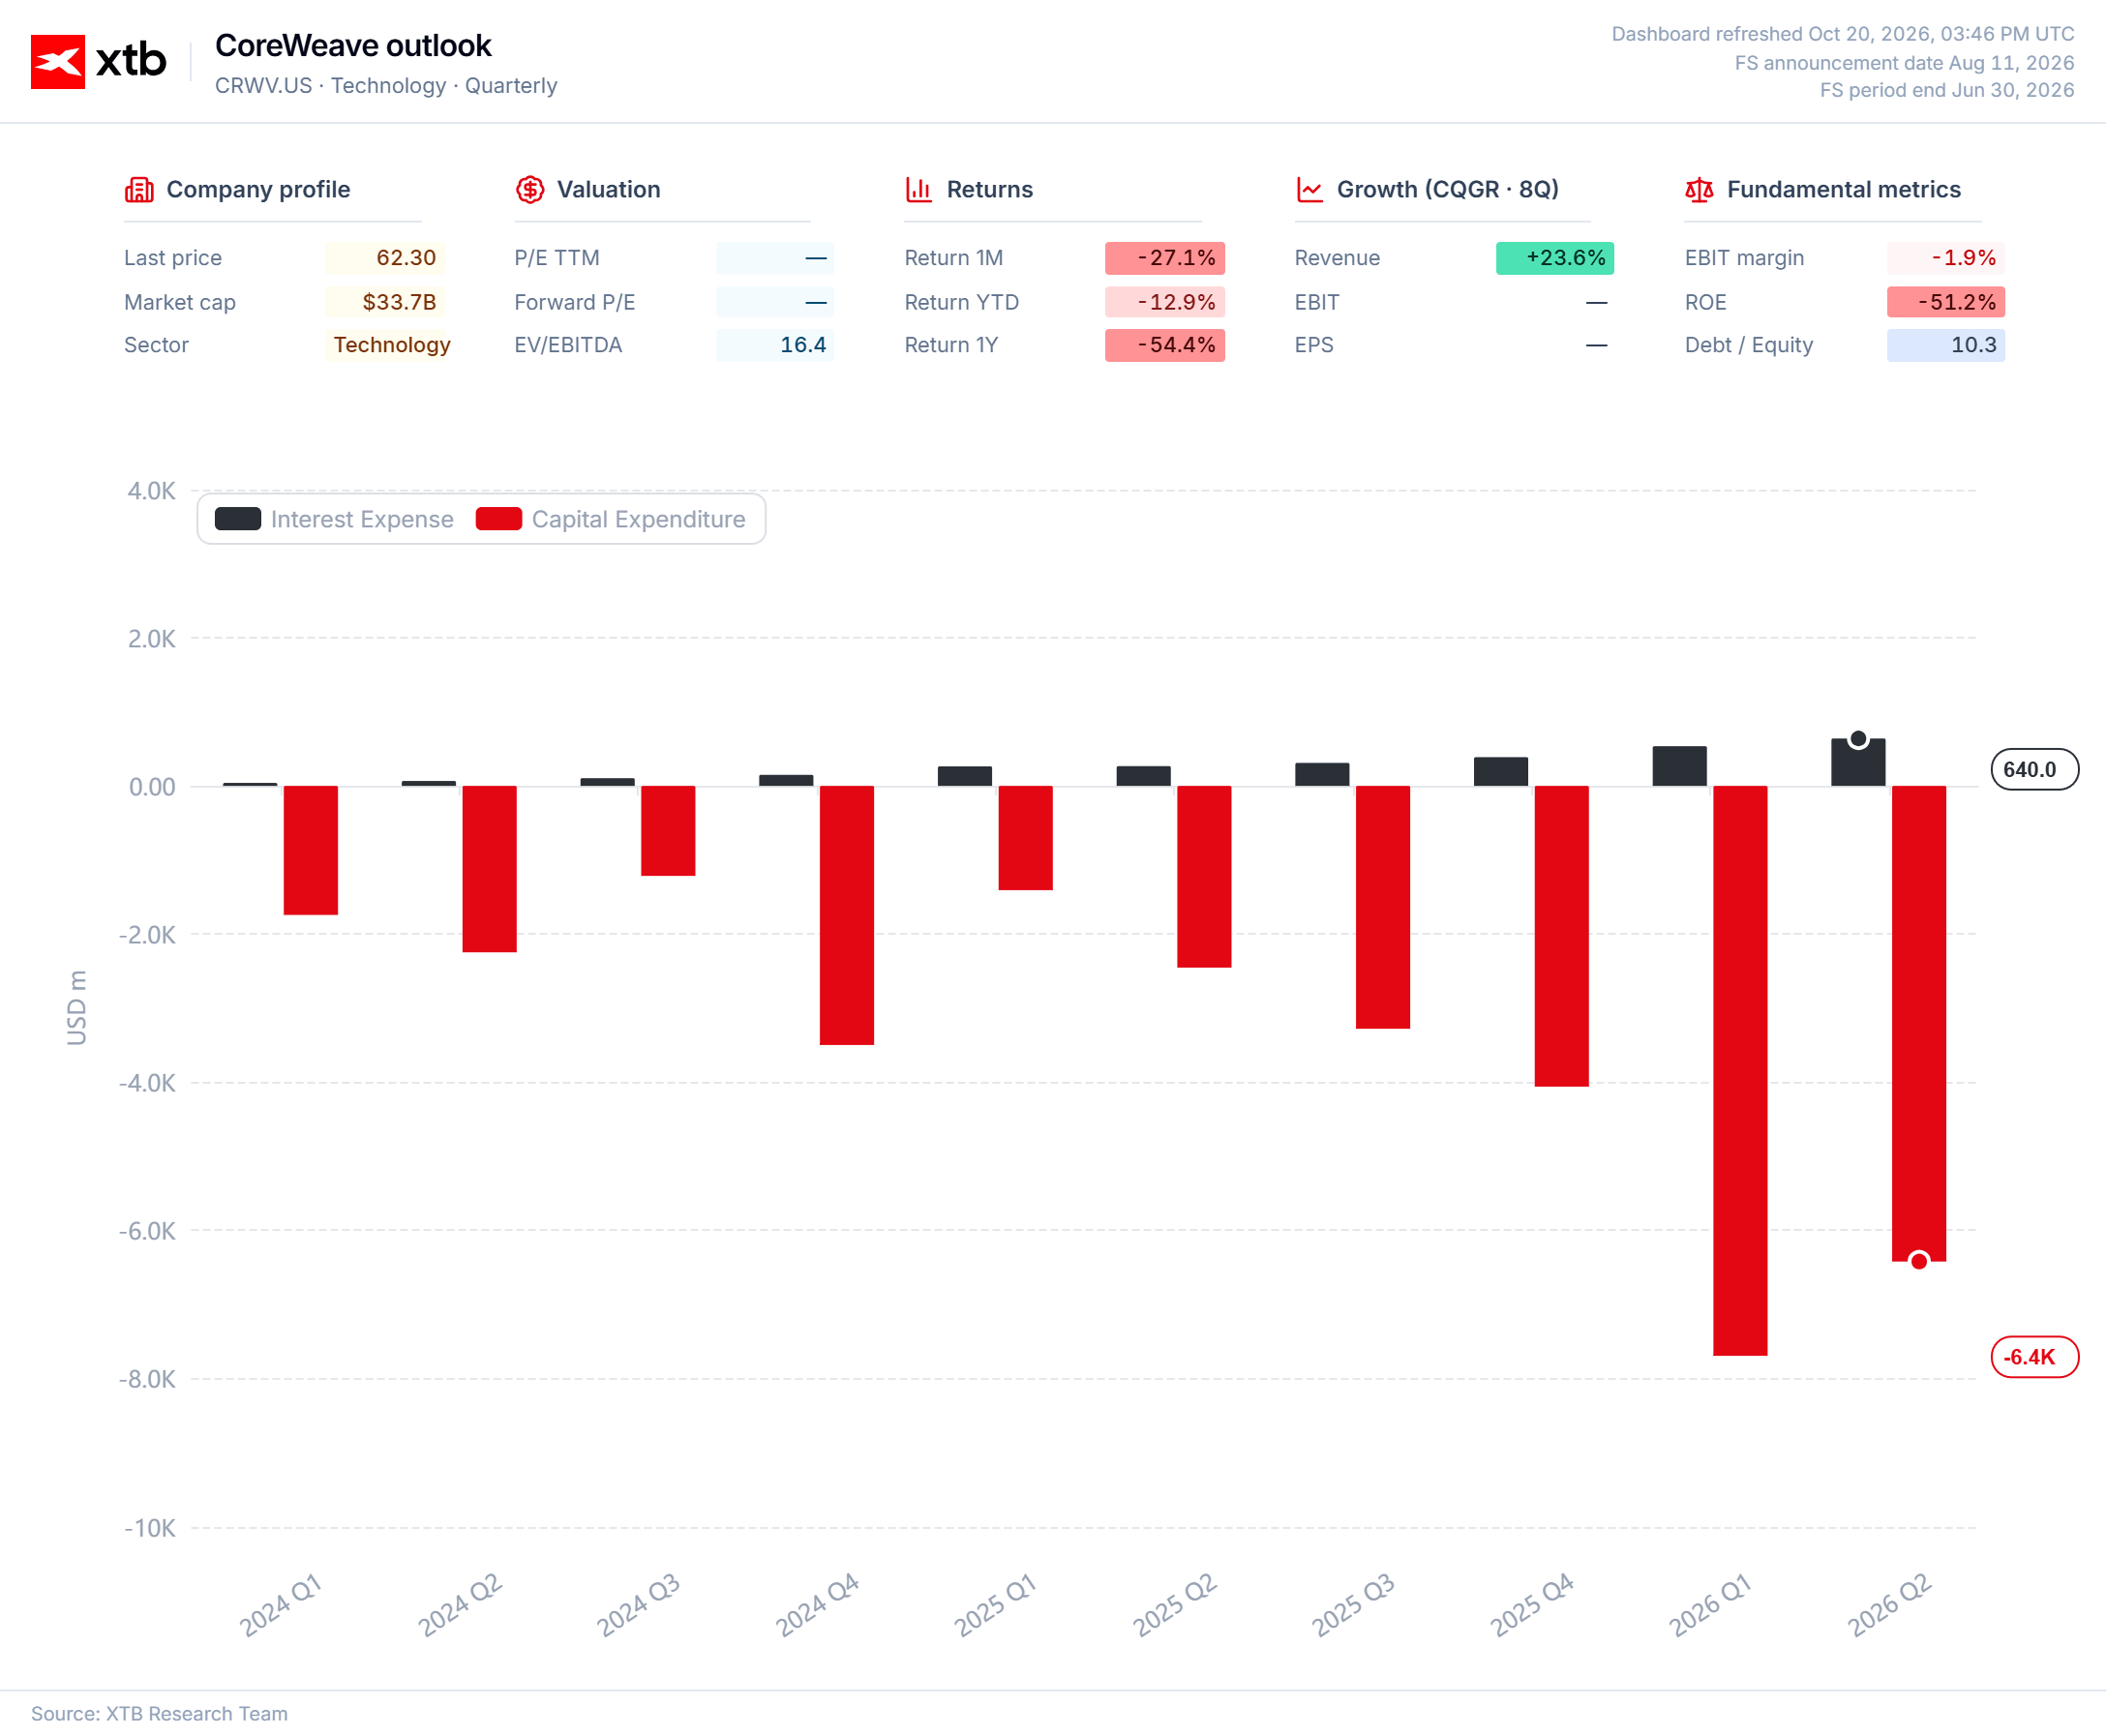
The gap between profits and the company’s ambitions is being financed by massive debt, even by industry standards. Planned capital expenditures for 2026 amount to USD 35 to 39 billion, almost three times projected revenue. In the second quarter, interest expense reached USD 640 million versus USD 267 million a year earlier, and the net loss increased to USD 626 million. Despite an approximately 59% (adjusted) EBITDA margin, the company is still not net profitable.
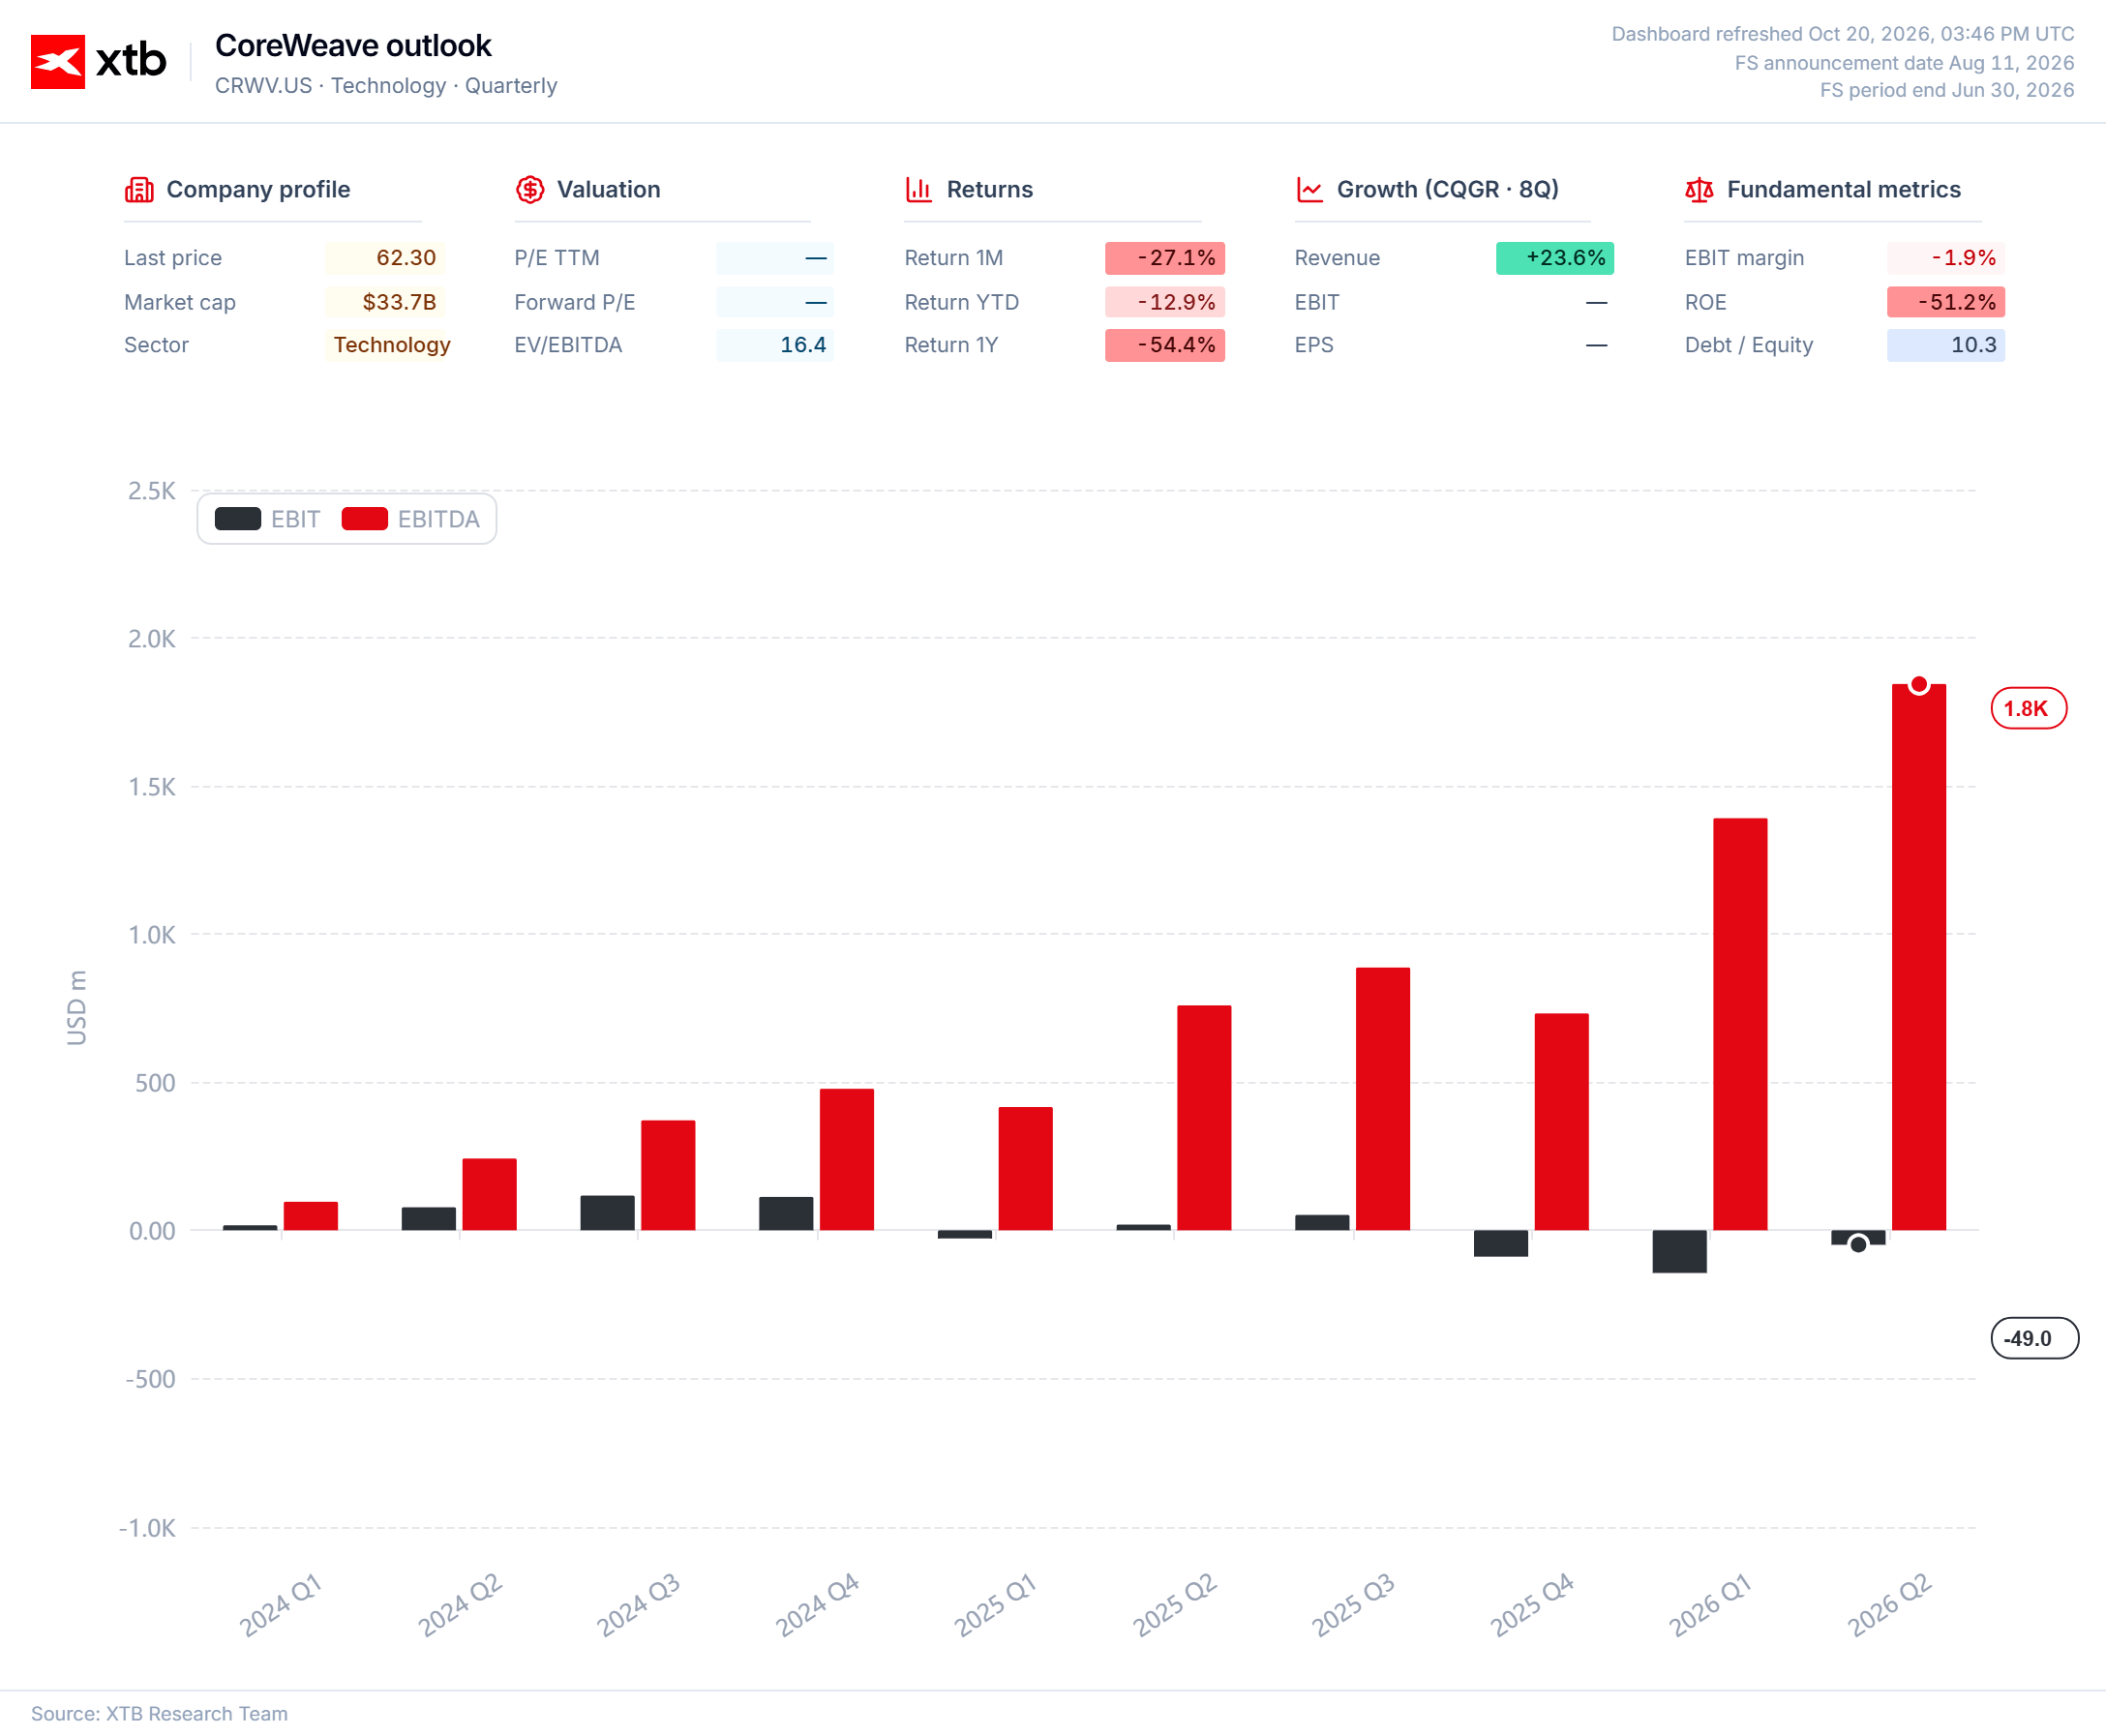
Importantly, as the name suggests, EBITDA does not include infrastructure depreciation or the cost of financing it. The company reports an enormous USD 2.5 billion in impairment charges. Also important, the company’s accounting policy assumes a 6 year useful life for assets, which seems misaligned with the breakneck pace of AI industry development.

The Burden of Debt

Financing is increasingly reflecting the company’s mounting challenges, and is becoming the biggest one. Yields on some bonds have risen to 16%, signaling serious creditor concerns.
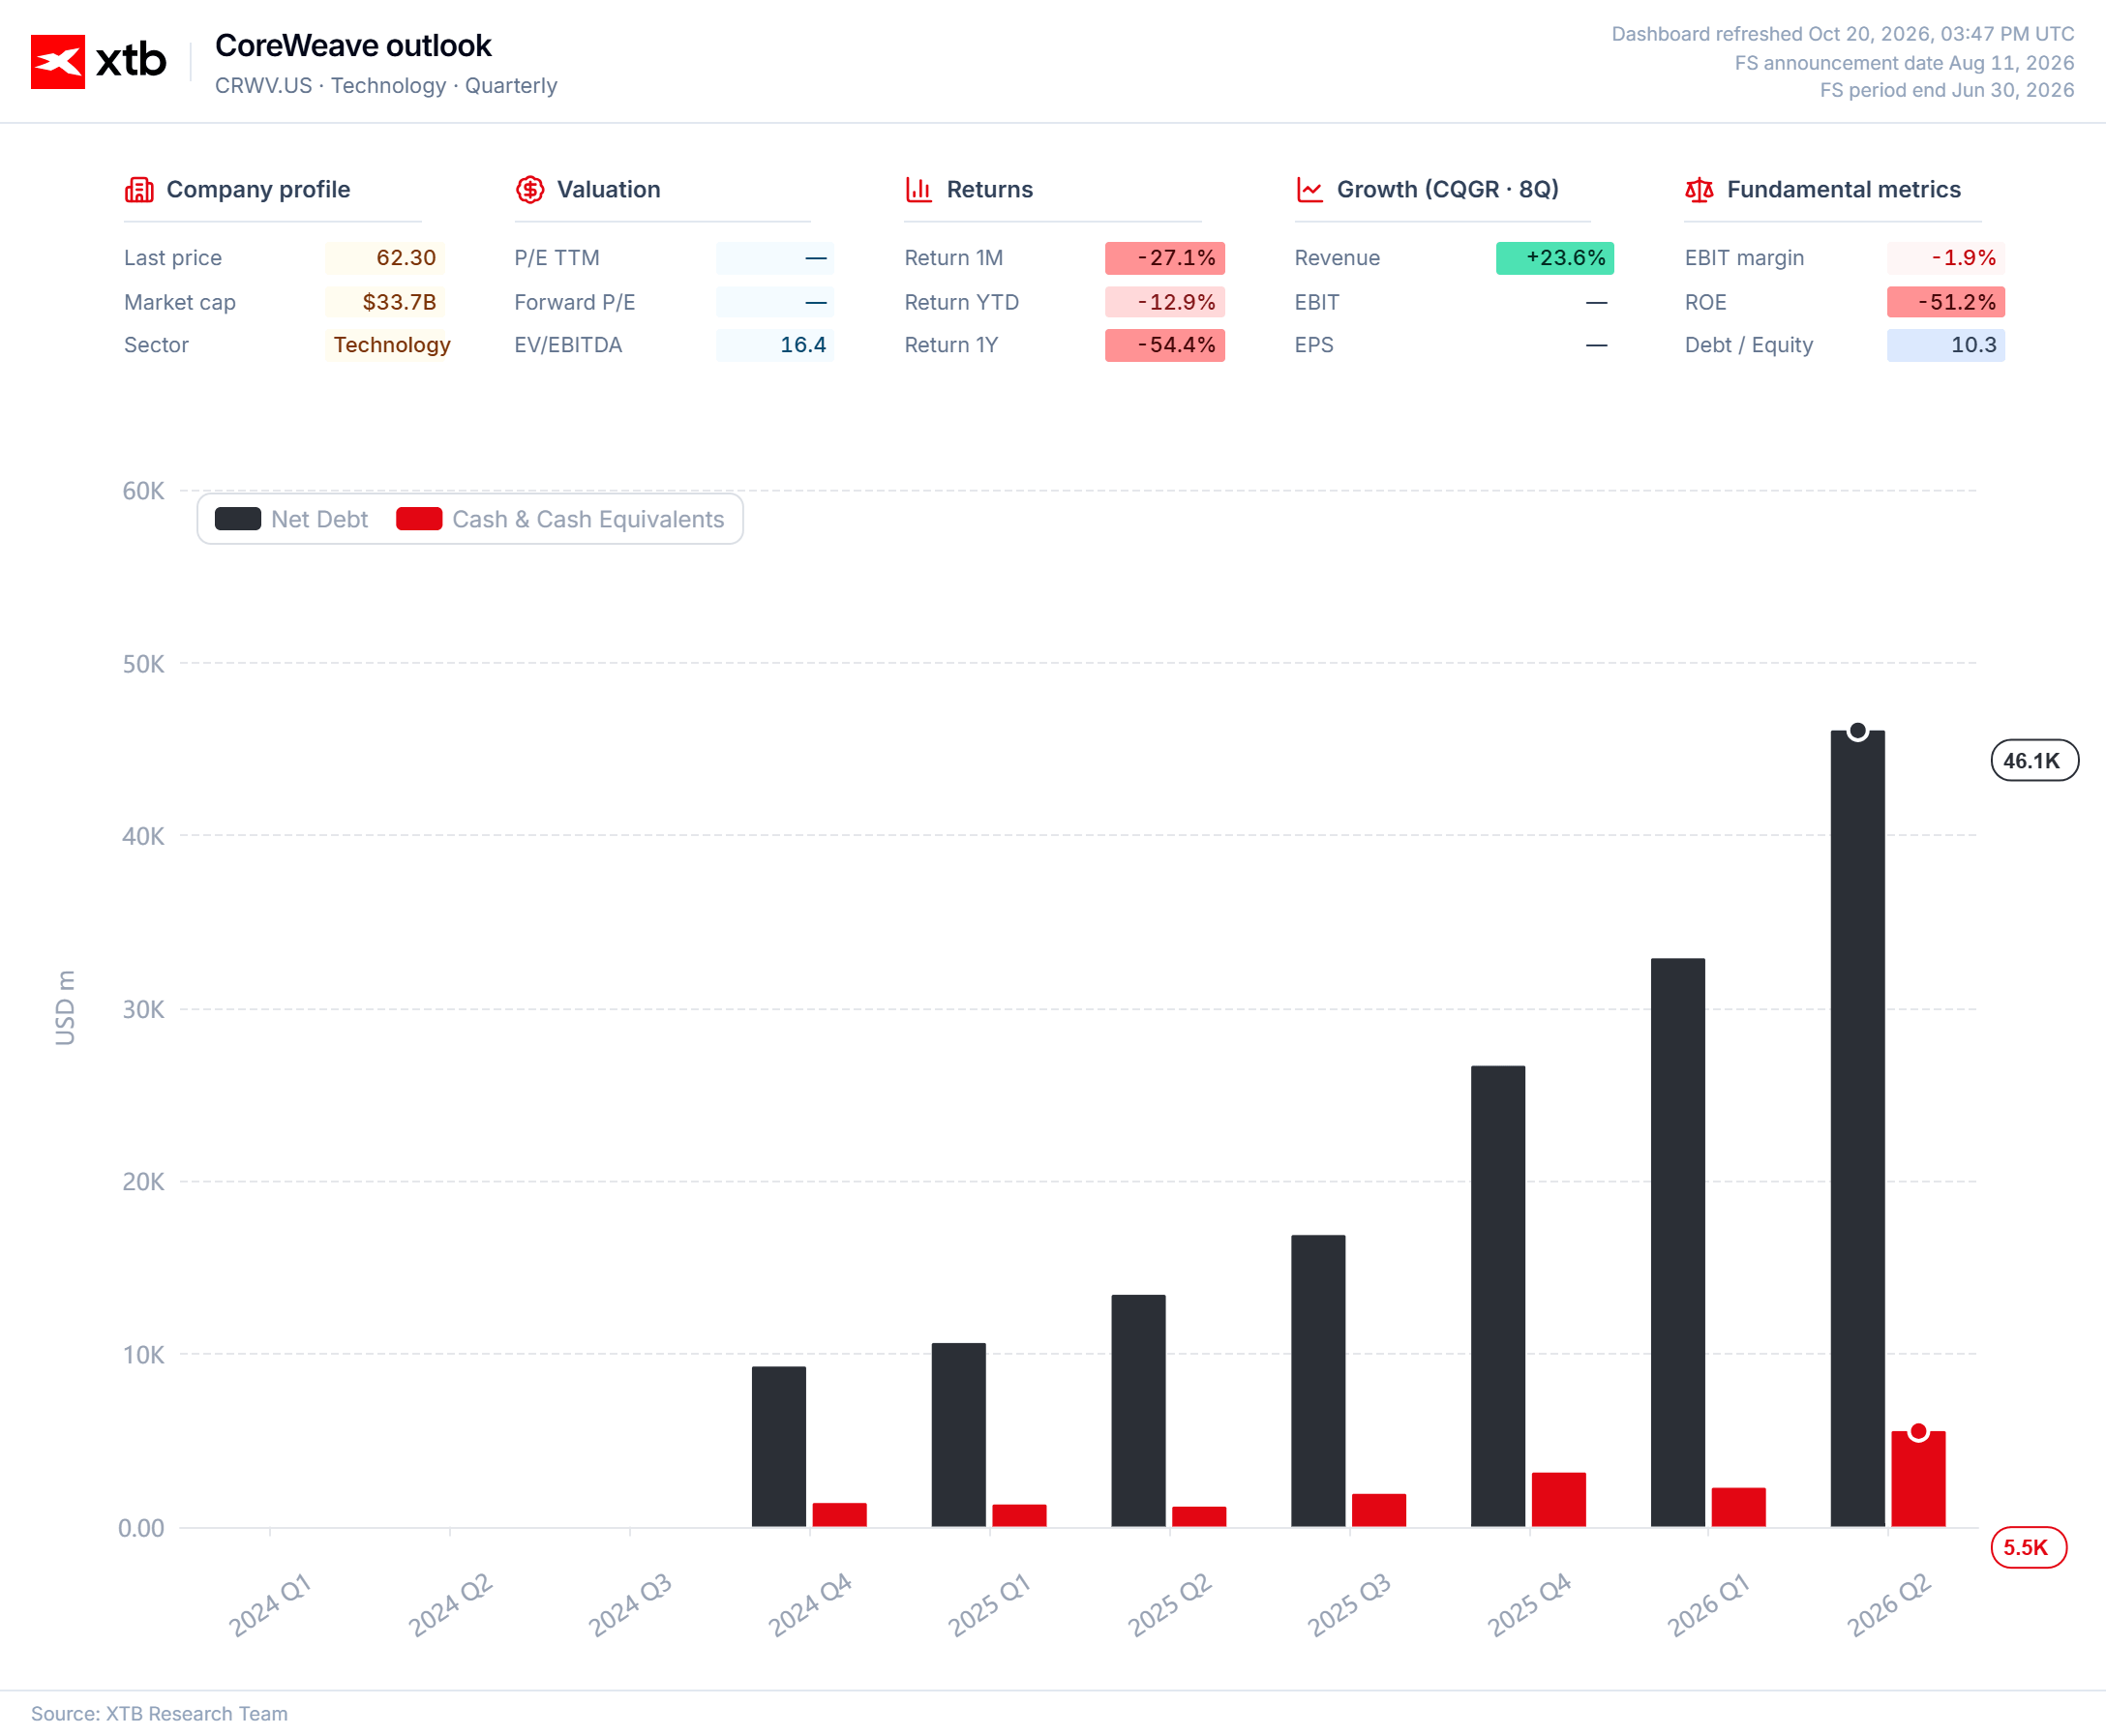
In addition, despite growing semiconductor supply, shortages remain severe and long term. In the short term, this means cost pressure, and in the long term, pressure on margins due to rising competition. CoreWeave’s situation is difficult, but not yet hopeless, and the company has room to improve operating efficiency. New contracts signed in the second quarter offered contribution margins up to 10 percentage points higher than in previous quarters. Expanding AI model deployment services as well as software, data storage, and networking could increase the revenue generated from existing infrastructure. Key factors here are the partnership with Nvidia and contracted access to power. If the company manages to reassure creditors while maintaining its current growth pace, the risk balance could shift dramatically in its favor. However, if component prices and availability remain this strained, the company may not be able to achieve the economies of scale necessary for the exponential growth assumed by the “neo cloud” business model.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button