S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Economic Calendar: Markets Await Reports from Procter & Gamble and Western Digital

The morning brings a return to risk-off mode, even though the previous session on Wall Street was strong (S&P 500 +0.58%, Nasdaq +1.05%). Investors have digested Meta’s and Tesla’s earnings, and sentiment has clearly deteriorated. The epicenter of the sell-off today is in Asia— CHN.cash (-3.16%) , which fits the picture of a Chinese bear market (the CSI 300 has fallen 20% from its June peak, marking its tenth consecutive week of declines amid an oversupply of power, a weak real estate market, and eroding retail investor confidence). Japan is also looking weak— JP225 (-2.76%) . In the U.S., the pressure is once again shifting to tech companies vulnerable to the funding boom in AI— US100 is down 1.63% , significantly more than the broader US500 (-0.86%) . Europe is also in the red: EU50 -1.08% , DE40 -0.77% , ITA40 -0.94% , while the UK100 (-0.28%) is holding up slightly better. The precious metals market saw a marked reversal of the previous trend— SILVER plummeted 3.07% to around $56.1, while GOLD fell by 1.12% below $4,100 (around $4,094), testing the key support level of $4,100–$4,117; a sustained decline below this level opens the way to the psychological level of $4,000. Rising yields and higher oil prices are putting pressure on metals. It is oil that is on the other side today —driven by a geopolitical premium (reports of plans to strike Iran again after the midterms, intensified Houthi attacks on Saudi Arabia) OIL is up 1.66% to about $107.5, and OIL.WTI is up 1.70% to about $99.4. In the foreign exchange market, the dollar is slightly weaker ( USDIDX -0.19% ) — EURUSD +0.15% to 1.1247, GBPUSD +0.10% , and USDJPY is down 0.63% to about 157.1. The risk-off sentiment isn’t sparing cryptocurrencies either — BITCOIN -2.66% to about 82,400 USD. What’s driving the market today:
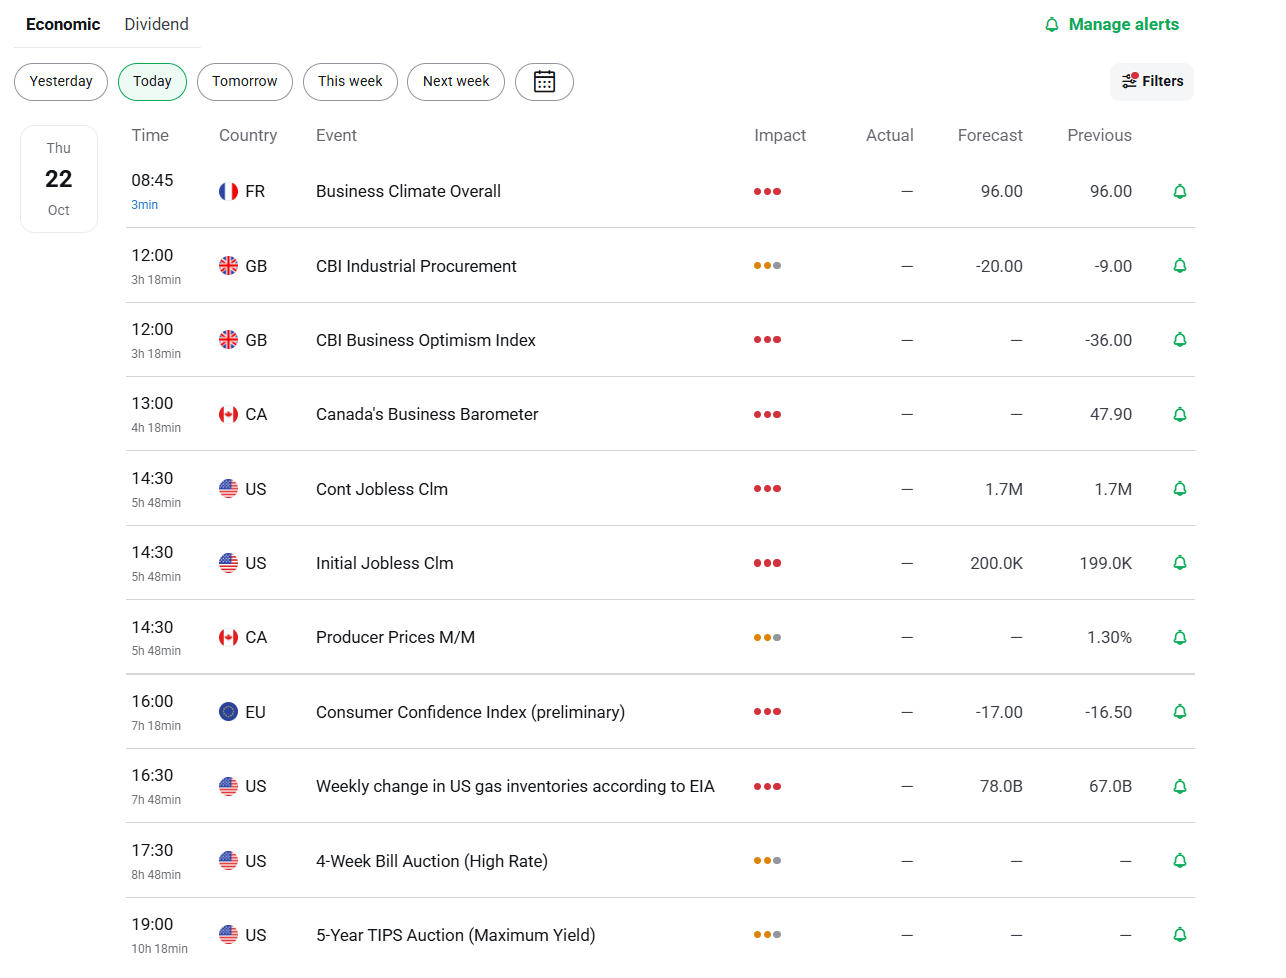
This trading session is light on macroeconomic data. News from Asia included a slowdown in inflation in New Zealand (3.7% y/y vs. a forecast of 3.8%) and the Bank of Korea’s decision to keep interest rates at 3.00%, leaving the door open for a move in November. Here in Poland, at 9:00 a.m. , we’ll see the Polish retail sales figures (year-over-year). However, the highlight of the day remains the U.S. weekly initial jobless claims at 14:30 (consensus around 200,000), followed by the EIA natural gas inventory report at 16:30 . The earnings season is setting the pace. Yesterday was dominated by reports from Meta (record revenue up 26% year-over-year to $64.6 billion and a strong forecast for Q4, but capex up 80% year-over-year and negative free cash flow—the cost of the “all-in on AI” strategy) and Tesla (a positive surprise in earnings quality and talk of a potential merger with SpaceX). Today, before the market opens, Procter & Gamble (PG.US) , Western Digital (WDC.US) , and Lockheed Martin (LMT.US) will report before the market opens, and Valero Energy (VLO.US) will report after the market closes. Bill Ackman’s appearance on CNBC (around 5:00 p.m.) will also draw attention. In the broader context, it will be worth watching whether the Asian sell-off (particularly the Chinese bear market) and this morning’s weakness will intensify at the U.S. market open, as well as whether a further rise in oil prices will reignite inflation fears and put pressure on central banks.