Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
Economic Calendar

Economic Calendar: Markets Await Reports from Procter & Gamble and Western Digital

The morning brings a return to risk-off mode, even though the previous session on Wall Street was strong (S&P 500 +0.58%, Nasdaq +1.05%). Investors have digested Meta’s and Tesla’s earnings, and sentiment has clearly deteriorated. The epicenter of the sell-off today is in Asia— CHN.cash (-3.16%) , which fits the picture of a Chinese bear market (the CSI 300 has fallen 20% from its June peak, marking its tenth consecutive week of declines amid an oversupply of power, a weak real estate market, and eroding retail investor confidence). Japan is also looking weak— JP225 (-2.76%) . In the U.S., the pressure is once again shifting to tech companies vulnerable to the funding boom in AI— US100 is down 1.63% , significantly more than the broader US500 (-0.86%) . Europe is also in the red: EU50 -1.08% , DE40 -0.77% , ITA40 -0.94% , while the UK100 (-0.28%) is holding up slightly better. The precious metals market saw a marked reversal of the previous trend— SILVER plummeted 3.07% to around $56.1, while GOLD fell by 1.12% below $4,100 (around $4,094), testing the key support level of $4,100–$4,117; a sustained decline below this level opens the way to the psychological level of $4,000. Rising yields and higher oil prices are putting pressure on metals. It is oil that is on the other side today —driven by a geopolitical premium (reports of plans to strike Iran again after the midterms, intensified Houthi attacks on Saudi Arabia) OIL is up 1.66% to about $107.5, and OIL.WTI is up 1.70% to about $99.4. In the foreign exchange market, the dollar is slightly weaker ( USDIDX -0.19% ) — EURUSD +0.15% to 1.1247, GBPUSD +0.10% , and USDJPY is down 0.63% to about 157.1. The risk-off sentiment isn’t sparing cryptocurrencies either — BITCOIN -2.66% to about 82,400 USD. What’s driving the market today:
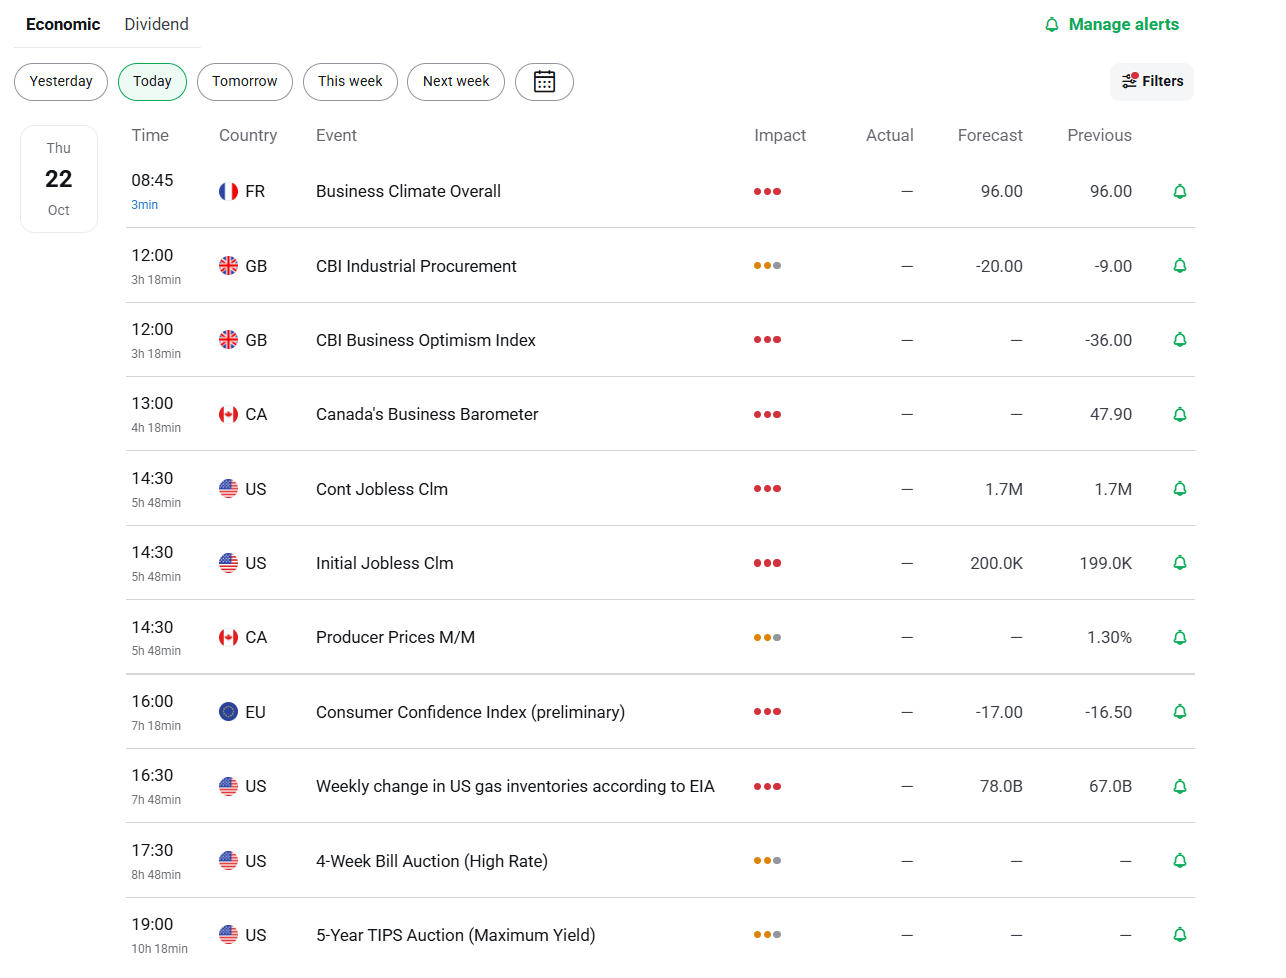
This trading session is light on macroeconomic data. News from Asia included a slowdown in inflation in New Zealand (3.7% y/y vs. a forecast of 3.8%) and the Bank of Korea’s decision to keep interest rates at 3.00%, leaving the door open for a move in November. Here in Poland, at 9:00 a.m. , we’ll see the Polish retail sales figures (year-over-year). However, the highlight of the day remains the U.S. weekly initial jobless claims at 14:30 (consensus around 200,000), followed by the EIA natural gas inventory report at 16:30 . The earnings season is setting the pace. Yesterday was dominated by reports from Meta (record revenue up 26% year-over-year to $64.6 billion and a strong forecast for Q4, but capex up 80% year-over-year and negative free cash flow—the cost of the “all-in on AI” strategy) and Tesla (a positive surprise in earnings quality and talk of a potential merger with SpaceX). Today, before the market opens, Procter & Gamble (PG.US) , Western Digital (WDC.US) , and Lockheed Martin (LMT.US) will report before the market opens, and Valero Energy (VLO.US) will report after the market closes. Bill Ackman’s appearance on CNBC (around 5:00 p.m.) will also draw attention. In the broader context, it will be worth watching whether the Asian sell-off (particularly the Chinese bear market) and this morning’s weakness will intensify at the U.S. market open, as well as whether a further rise in oil prices will reignite inflation fears and put pressure on central banks.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button