Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
MarketsNasdaq 100StocksTechnical AnalysisUS100Wall Street

US100 drops 1.8%

The tech sector is reversing its previous gains and testing an important support level Nasdaq-100 futures plunged nearly 1.8% on Thursday, with the US100 falling to 29,467 points (-554 points, -1.85%), as investors once again focused on the “cost” of investing in artificial intelligence. Although Meta beat revenue forecasts (up 26% to $64.6 billion) and SpaceX reported its first profit as a public company, optimism had already evaporated in Asia. The market focused on the costs of AI investments—Meta’s plan to issue Class C shares reignited concerns about the scale of its capital commitments, and Lam Research’s weak outlook sent the company down more than 8% after the close. Tesla is down about 5% in premarket trading, and the chip sector is retreating across the board (Intel and Marvell down more than 5%, Nvidia down 2.2%). The macroeconomic backdrop isn’t helping: Brent crude is up more than 2% to around $108 following further Houthi attacks on Saudi Arabia, while U.S. 10-year Treasury yields are falling to about 5.09%. In France, the situation looks worse, as yields on 10-year OATs are already rising to 5.05%, widening the spread against German bonds. Technical Analysis (US100, daily timeframe)
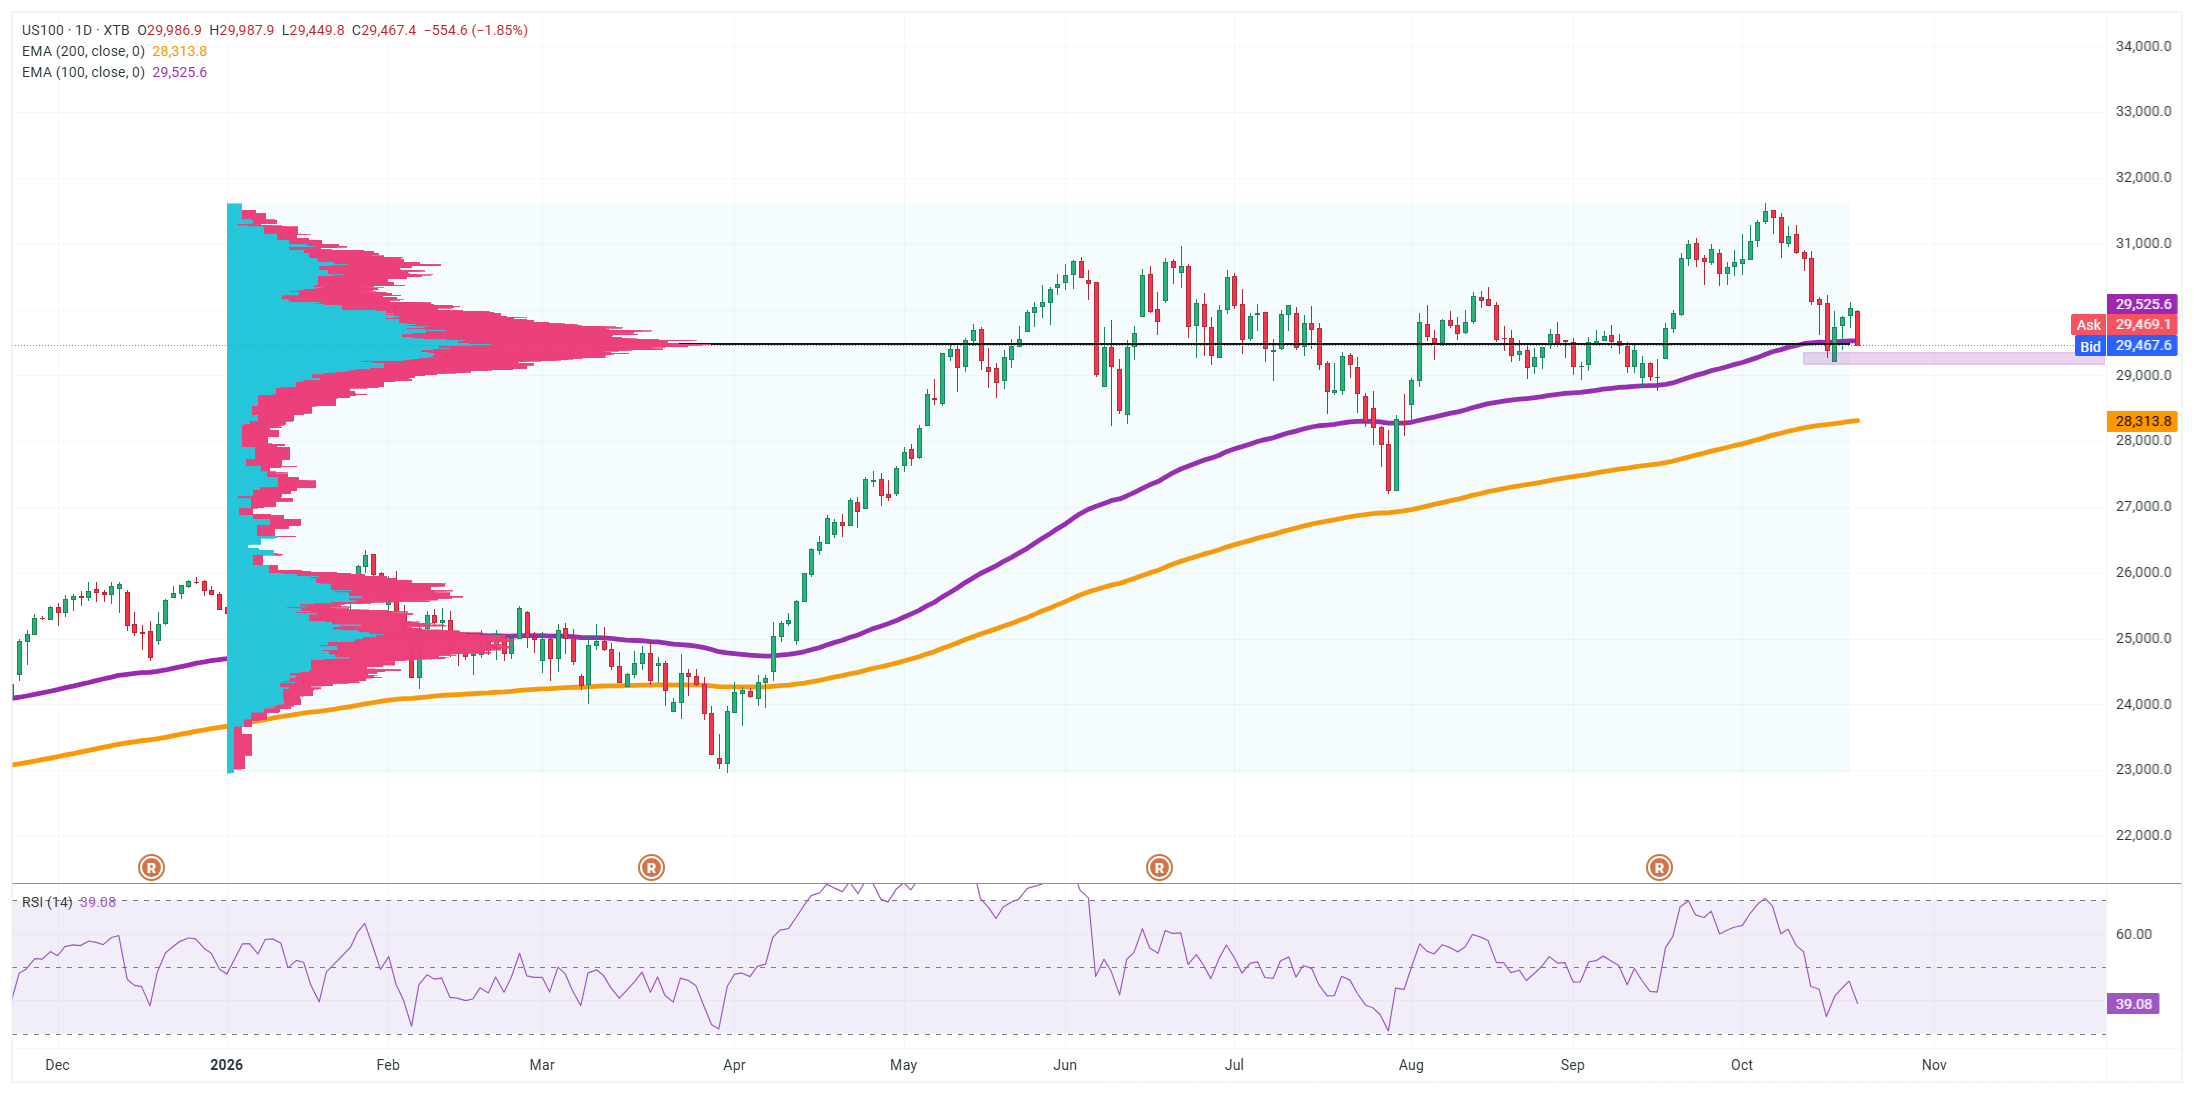
The price fell below the EMA100 (29,526) today, which had served as dynamic support over the past few weeks—this is the first sign of a weakening in the short-term trend. The key support zone is around 29,000–29,300 points (the highlighted support rectangle coinciding with the volume profile and the September lows); whether this level holds will determine whether we are dealing merely with a correction within an uptrend. Below this level, the path opens up to the EMA200 at 28,314 points, which is the structural defense line for the entire rally since April. The RSI (14), currently at 39, is moving toward the oversold zone but has not yet reached extreme levels—this leaves room for the downtrend to continue before a technical rebound occurs.
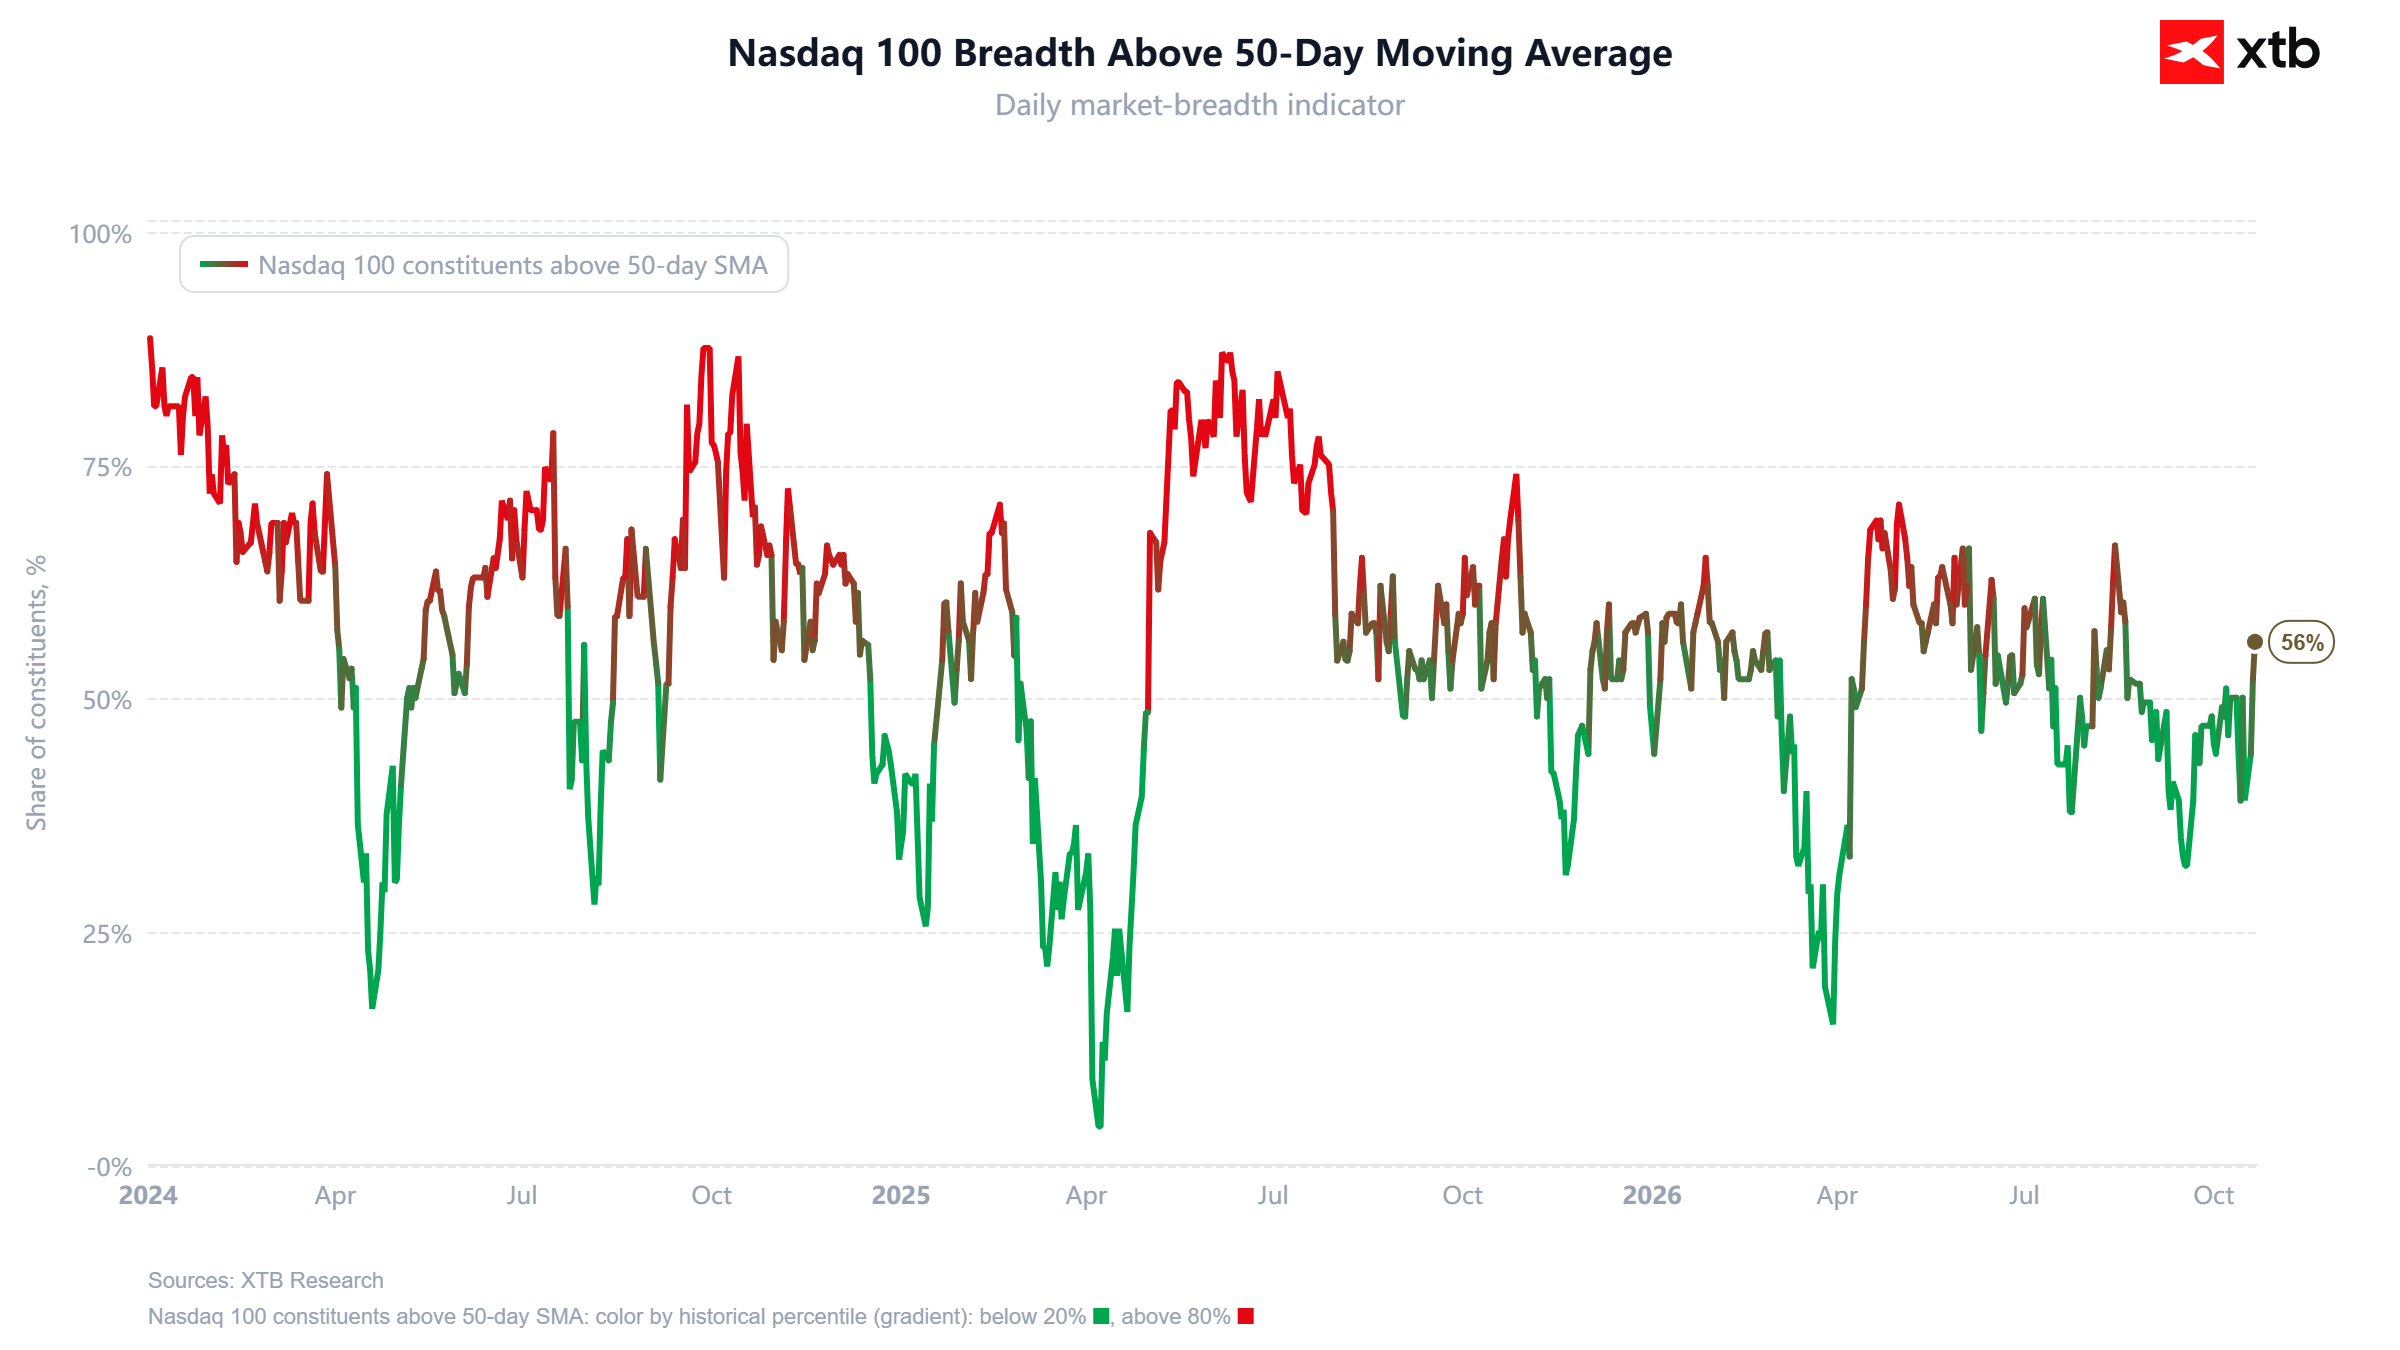
Market breadth reflects caution: only 56% of Nasdaq-100 companies are trading above their 50-day moving average, and the index’s gap from the 200-day EMA has narrowed to +6.2%—a far cry from earlier, overheated levels. Source: XTB
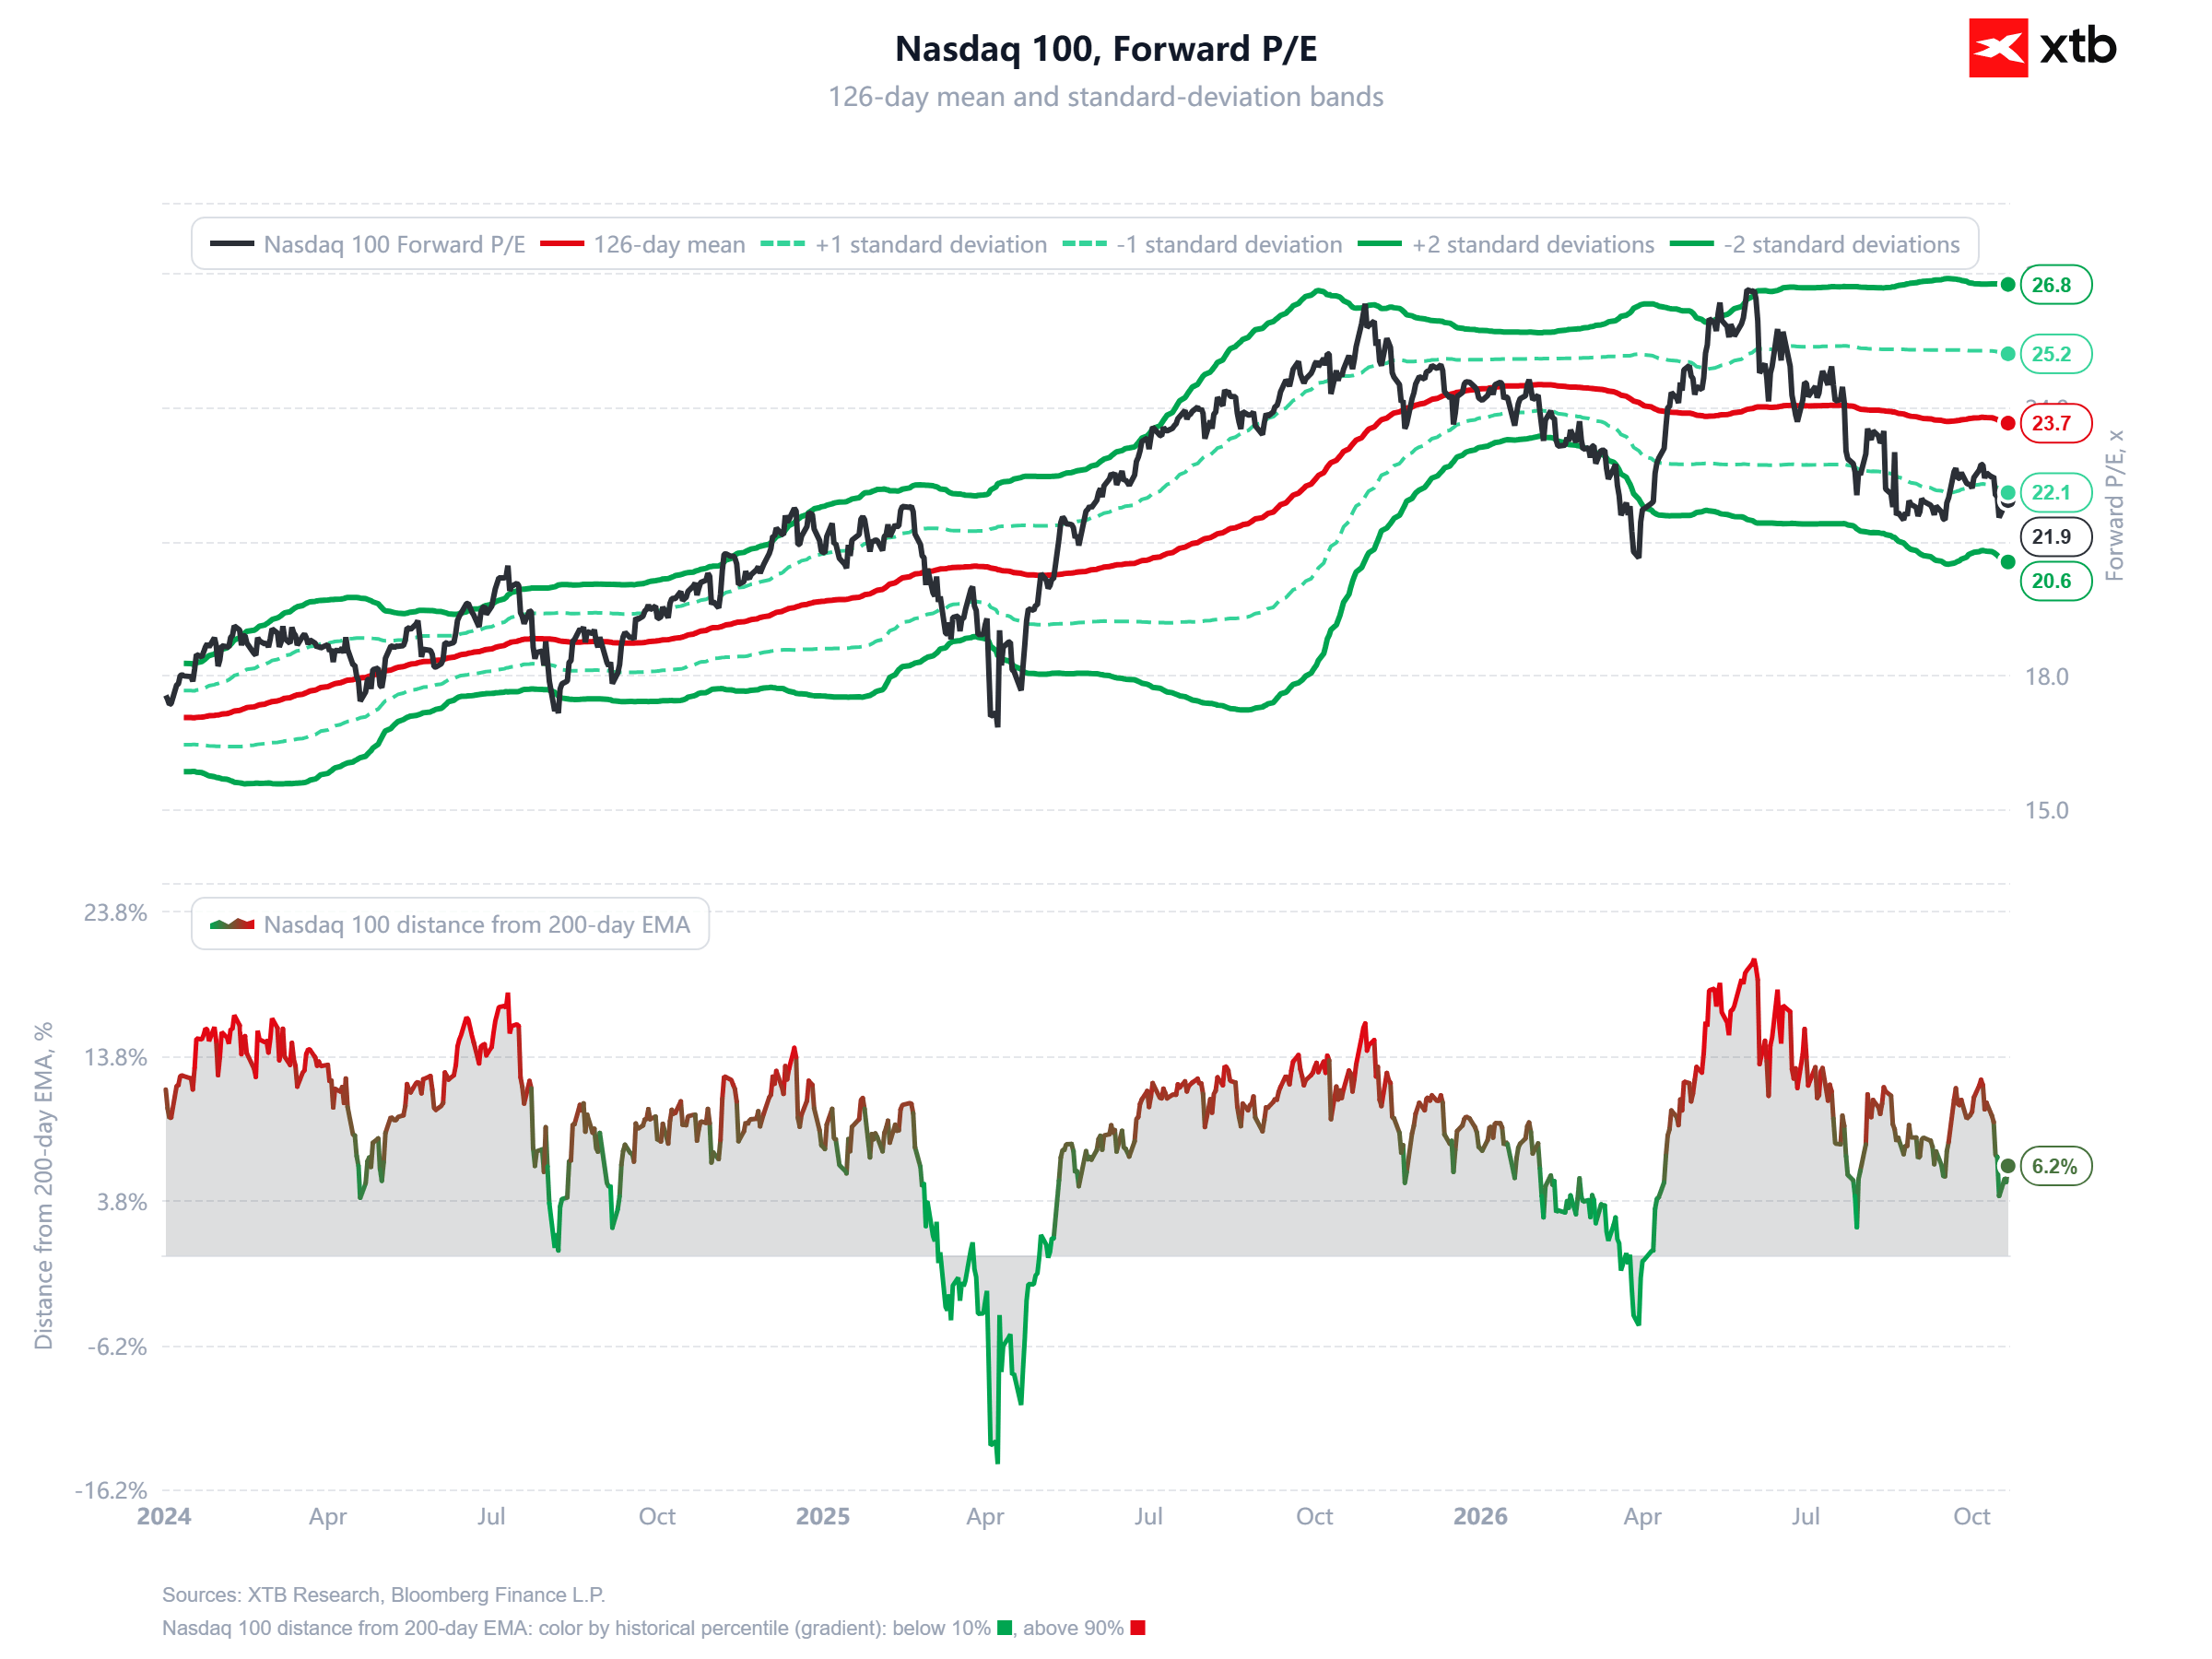
The Nasdaq-100 forward P/E ratio has fallen to 21.9x (below the 126-day average of 23.7x), which somewhat tempers the argument that the market is extremely overvalued; however, in the current environment, it is the valuation of future earnings growth—not multiples—that may determine the direction of the stock market. Source: XTB

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button