S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- Scotiabank analysts warn that narrowing UK-US yield spreads are weakening fundamental support for the British pound.
- Rising oil prices revive UK stagflation fears, posing a dilemma for the Bank of England.
- Safe-haven demand from escalating Strait of Hormuz tensions boosts the US Dollar as global market instability grows.
GBP/USD extends its losses for the second consecutive day, trading around 1.3450 during the Asian hours on Friday. The pair depreciates as the British Pound (GBP) softens even as United Kingdom (UK) political risk fades.
Analysts at Scotiabank observe that “fundamentals appear to be somewhat less supportive for the GBP, as we note the renewed softening in yield spreads,” tempering the near-term backdrop for the currency. However, they also highlight that “sentiment continues to improve” as “market participants continue to fade politically-motivated concerns following the recent political transition and arrival of PM Burnham.” In their view, “the new PM’s commitment to fiscal responsibility appears to be much stronger than expected,” helping to offset the drag from softer yield differentials and underpinning a more constructive tone toward the Pound.
Rising oil prices have reignited fears of sticky inflation and sluggish economic growth in the UK, presenting the Bank of England (BoE) with a challenging “stagflationary” dilemma. This pressure directly tests the central bank’s stance following last week’s monetary policy meeting, where Governor Andrew Bailey downplayed the necessity for further rate hikes. At the time, Bailey expressed confidence that the UK’s disinflation process remains firmly on track, even against a backdrop of ongoing geopolitical uncertainty.
The GBP/USD pair faces downward pressure as the US Dollar (USD) gains strength, propelled by renewed safe-haven demand among global investors. Escalating tensions in the Strait of Hormuz have rattled market stability and created significant skepticism regarding the reopening of this critical shipping route. Market caution remains elevated as Iran’s parliament evaluates a draft proposal that seeks to prohibit US and Israeli vessels, levy a 20% cargo penalty on hostile nations, and maintain restrictions on the corridor until the US blockade is removed.
Musalem flags upside inflation risks and defends surprise moves, keeping Dollar bulls alert
Fed’s Musalem delivers a slightly more hawkish tone, with a 7.4/10 FXS Speechtracker score relative to the historical average of 7/10, emphasizing that inflation expectations risk losing their anchor even as they currently align with the 2% target. The focus on core inflation amid energy volatility, a preference for incremental rate hikes, and an assessment that core inflation likely sits between 2.5% and 3% underscore the concern that inflation may stay above target, while the assertion that sometimes it is acceptable for the central bank to surprise markets signals a willingness to prioritize the mandate over market guidance. Musalem’s view that the Dollar’s reserve status is secure, the labor market is strong but not an inflation driver, and financial conditions remain highly accommodative reinforces a backdrop where upside rate risks remain on the table.
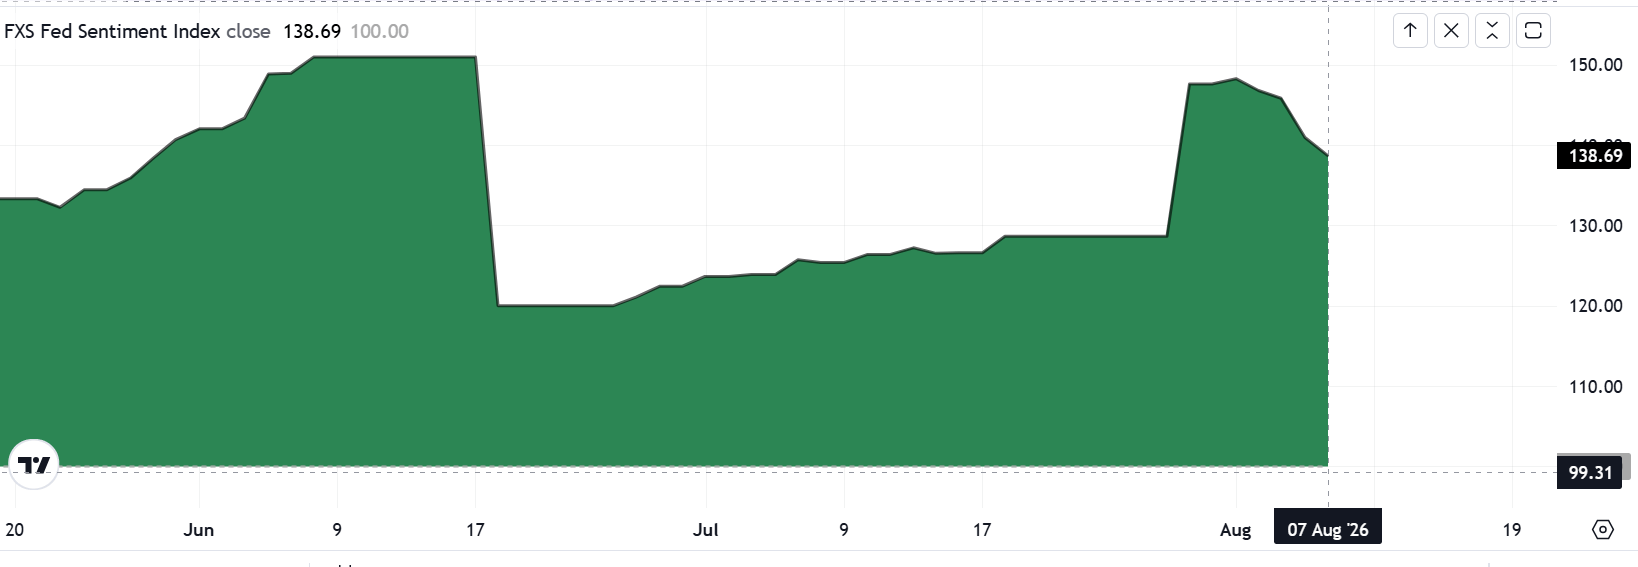
The FXS Fed Sentiment Index was unchanged, moving 0.00 points to a still distinctly hawkish level of 138.69, indicating that Musalem’s remarks fit comfortably within the prevailing hawkish bias rather than shifting it further. The combination of a slightly above-baseline FXS Speechtracker score and a stable, elevated FXS Fed Sentiment Index suggests the speech consolidates existing expectations for a Fed inclined to keep policy tight, supporting the Dollar while limiting fresh directional impetus.