S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Intel Surprised the Market. Is the Turnaround Finally Gaining Momentum?


Ahead of Intel’s earnings release, the key question on investors’ minds was whether the company’s lengthy restructuring efforts were finally starting to deliver tangible results. The second-quarter report provided a much stronger answer than expected. Intel not only comfortably beat analysts’ estimates on both revenue and earnings, but also issued a stronger-than-expected outlook for the third quarter, a development that was welcomed enthusiastically by investors.
Key Second-Quarter Highlights
- Revenue: $16.1 billion vs. $14.4 billion expected
- Adjusted EPS: $0.42 vs. consensus of $0.21
- Data Center & AI revenue: $6.3 billion, up 59% year over year
- Intel Foundry revenue: $5.8 billion, up 31% year over year
- Gross margin: 40.4% vs. 39.2% expected
- Q3 revenue guidance: $15.8–16.8 billion vs. consensus of around $15.1 billion
- Q3 EPS guidance: $0.38 vs. expectations of $0.27
Following the earnings release, Intel shares moved sharply higher in after-hours trading. Investors were encouraged not only by the stronger-than-expected quarterly results but also by management’s decision to raise guidance for the coming quarter. In the technology sector, forward-looking guidance often carries even greater weight than historical results. One of the strongest aspects of the report was the Data Center & AI business, where revenue surged 59% year over year. The performance suggests Intel is beginning to benefit from the massive wave of investment in computing infrastructure. As more companies expand their data center capacity, demand for server processors—one of Intel’s core products—continues to accelerate.
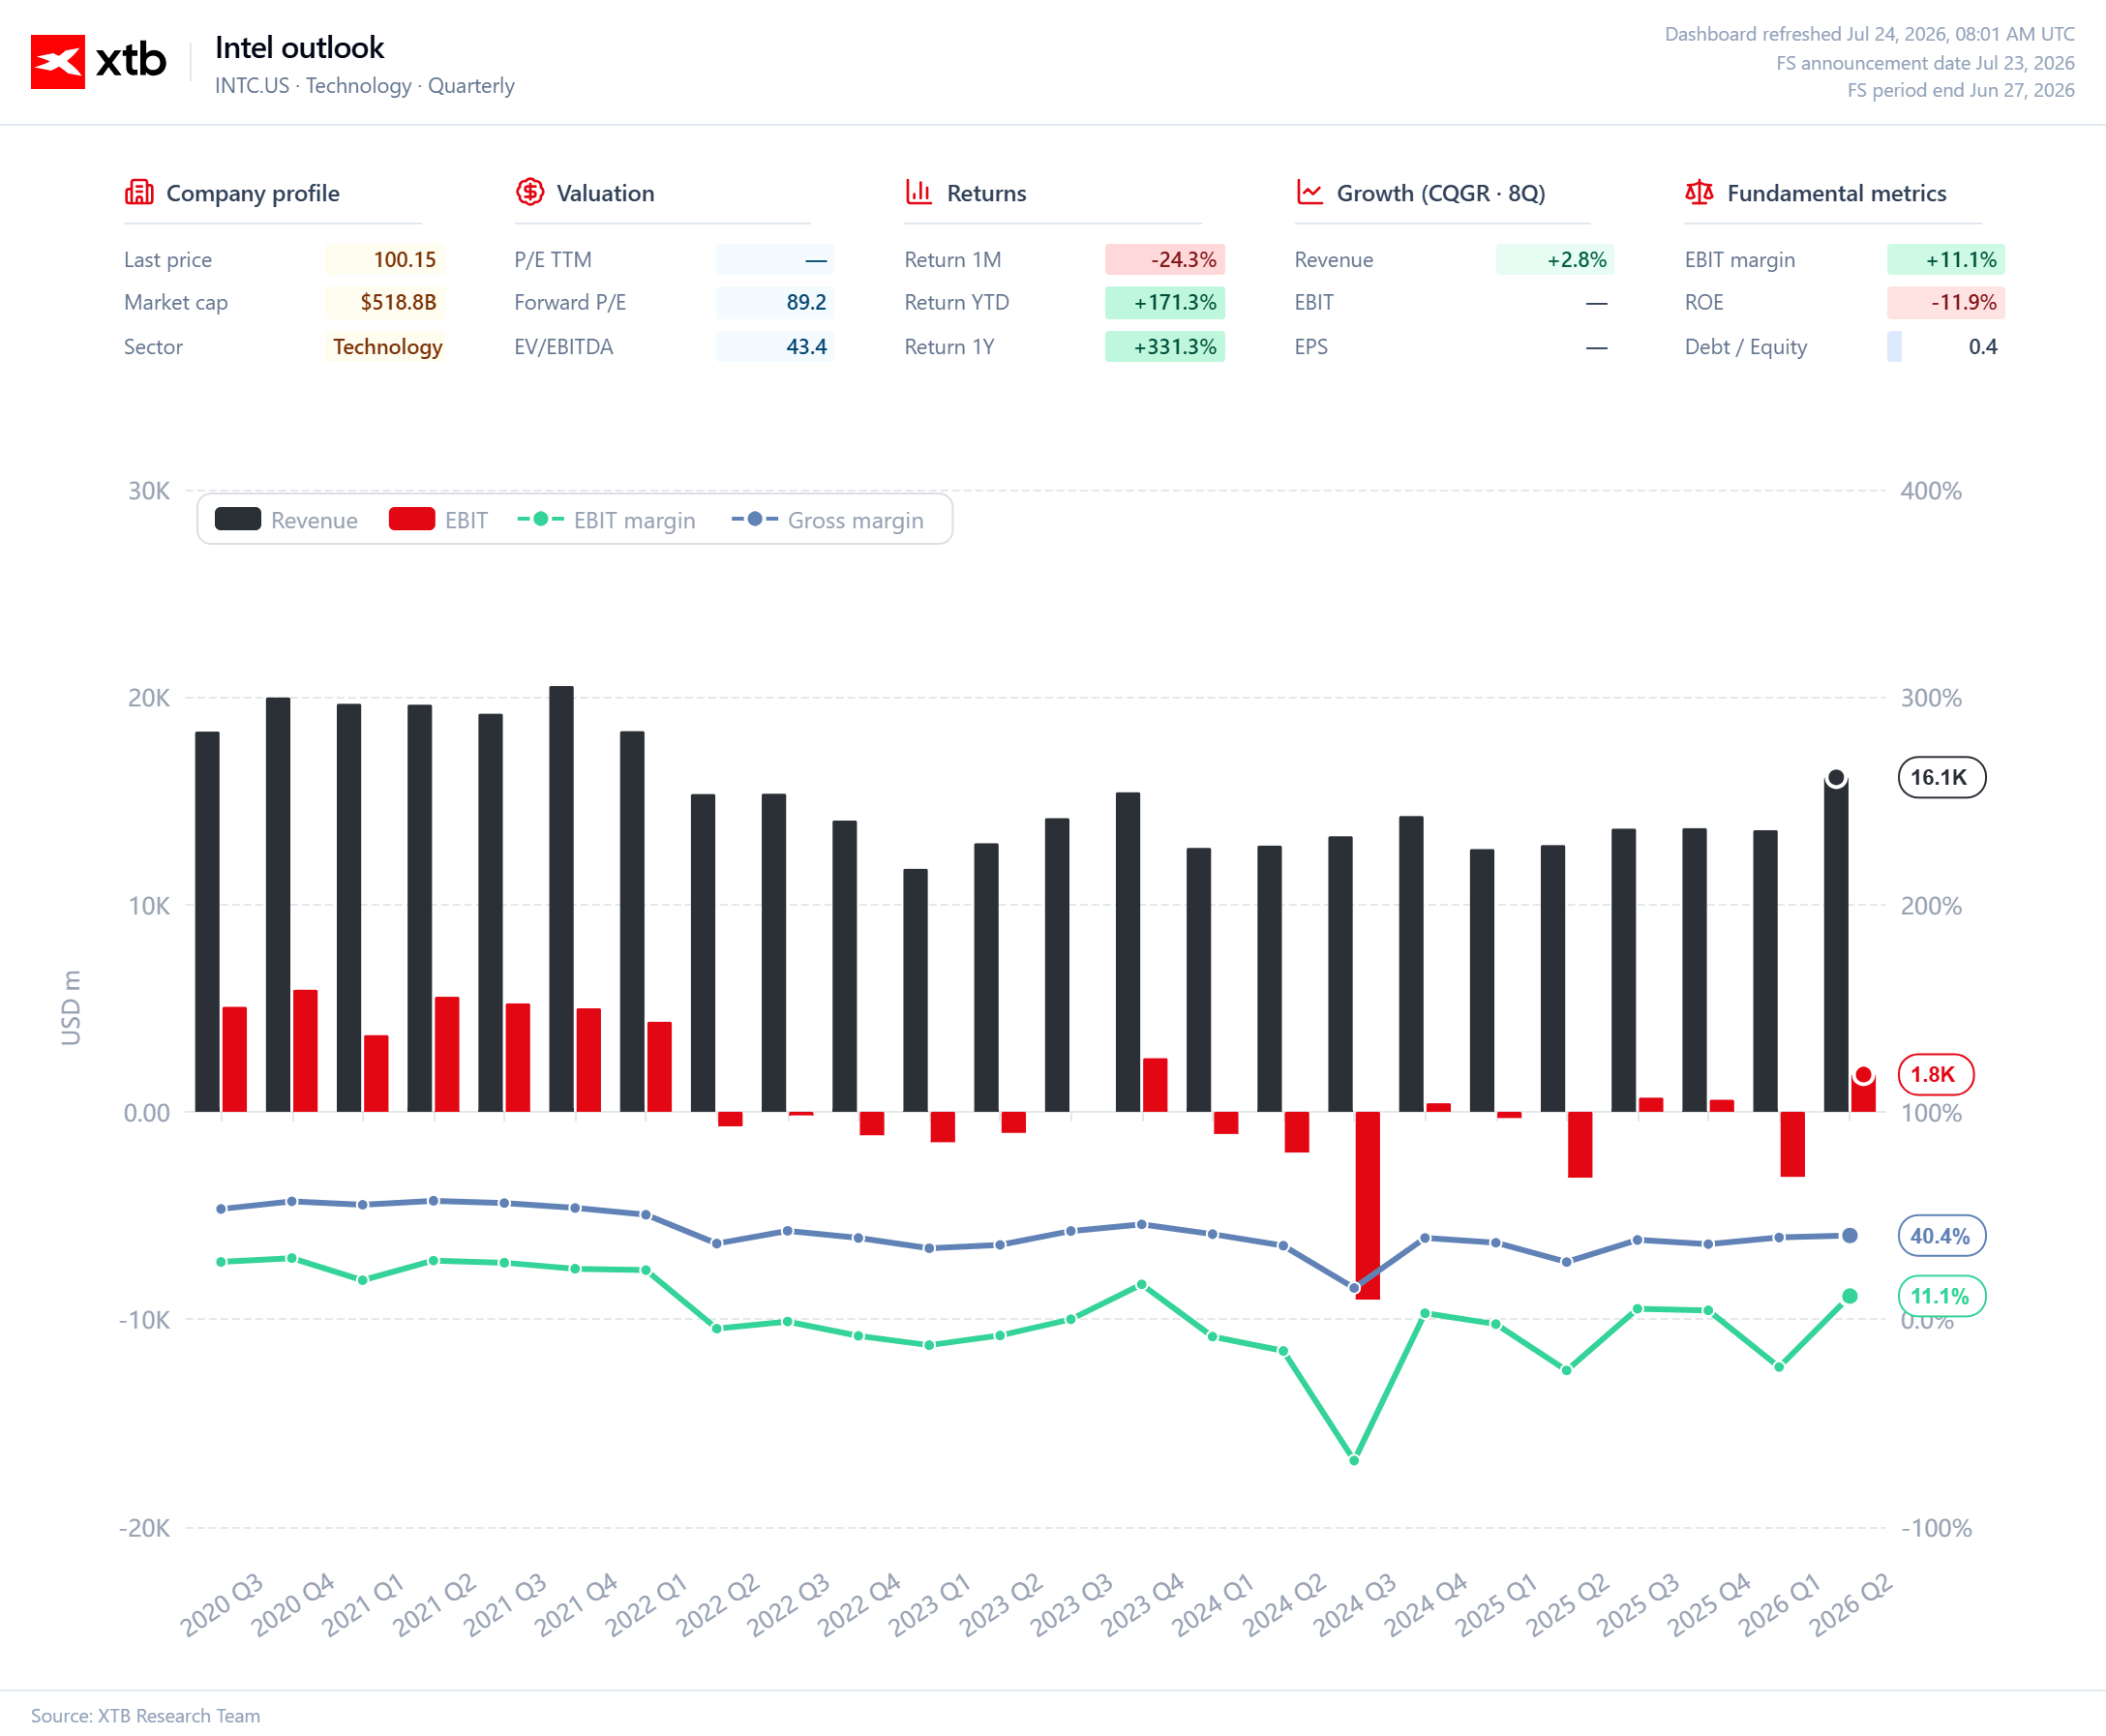
Management’s commentary also reinforced the positive outlook. CEO Lip-Bu Tan stated that demand for Intel’s server processors is currently exceeding the company’s manufacturing capacity. In response, Intel plans to increase capital spending to expand production and meet growing demand for both its own chips and foundry services provided to external customers. This reflects a broader shift in the AI investment cycle. Early in the boom, most attention was focused on chips used to train artificial intelligence models. Increasingly, however, the market is turning its attention to the infrastructure required to deploy and run those models at scale. In that environment, server CPUs remain a critical foundation of modern data centers. Another encouraging sign was the significant improvement in profitability. Gross margin rose to 40.4%, up from 29.7% a year earlier, while Intel returned to positive operating income. At the same time, the company announced plans to increase this year’s capital expenditures to approximately $20 billion, citing robust demand for computing infrastructure and continued expansion of its manufacturing business. That said, Intel’s turnaround is far from complete.
The company is still rebuilding after years of losing technological leadership and market share. Profit margins remain well below historical peak levels, and the foundry business continues to rely primarily on internal demand from Intel’s own business units. Winning more external customers and sustaining the current pace of improvement remain key challenges. Still, today’s earnings report delivers something investors have been waiting for: evidence that Intel’s restructuring is no longer just about cost cuts and workforce reductions. The benefits are now becoming visible in the financial results. Stronger revenue, improving profitability, and higher guidance all suggest that Intel is beginning to regain its footing in one of the semiconductor industry’s most important segments. Today’s report does not mean Intel has fully returned to its former position. It does, however, suggest that the turnaround is no longer just a story told in investor presentations. For the first time in quite a while, it is being backed up by the numbers.
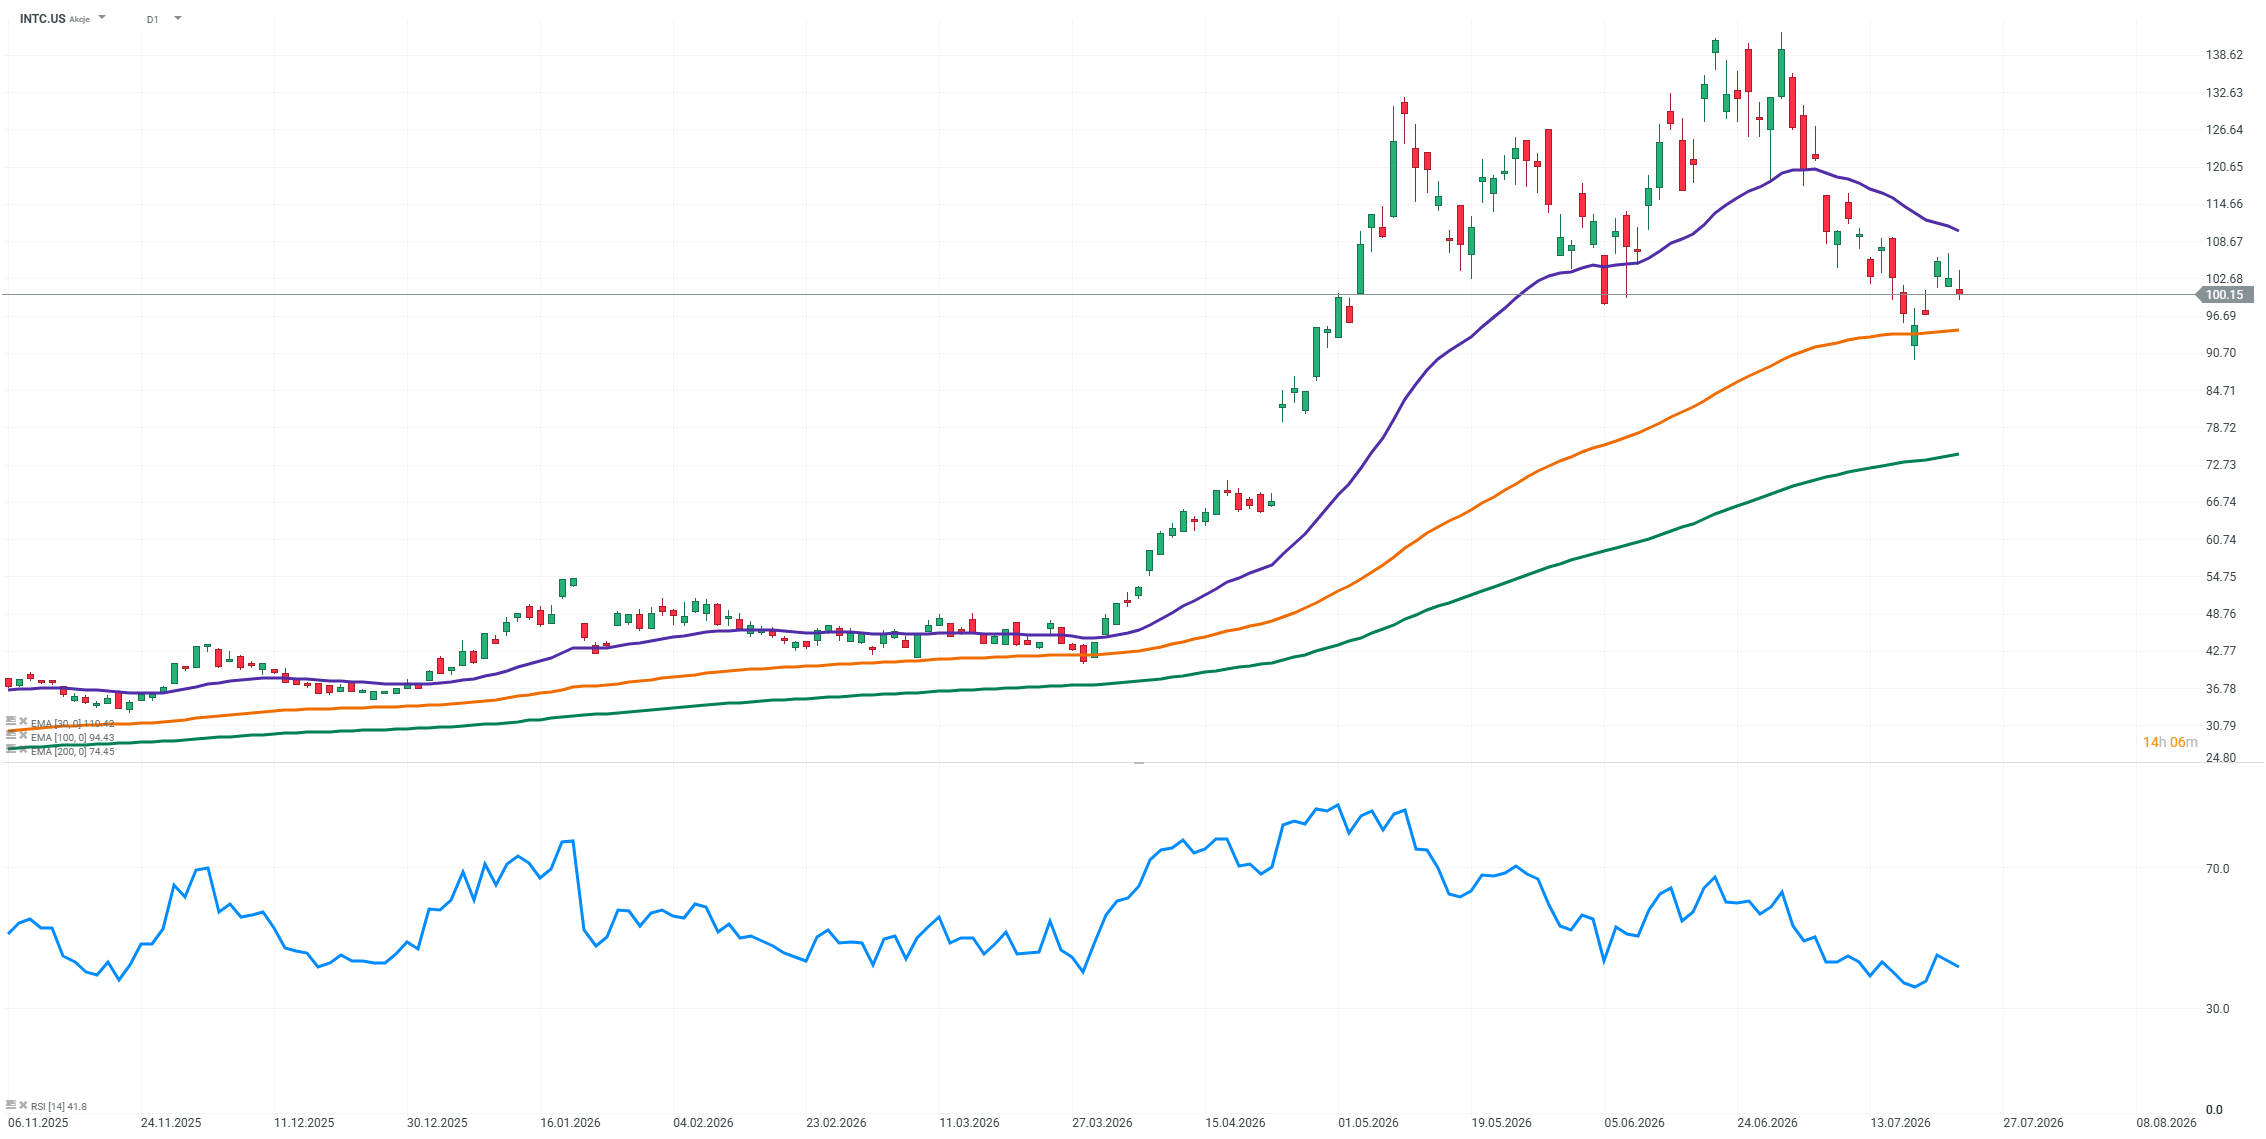
Źródło: xStation5