 S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

- Escalation in the Middle East back in the spotlight. On Wednesday evening (US time), the US carried out a “heavy wave” of air strikes against targets belonging to Iran’s Islamic Revolutionary Guard Corps, in retaliation for Iranian missile attacks on US bases on Tuesday. Trump had previously announced a “heavy strike” against Iran, saying “we’re going to hit them, they’re going to get a beating”. UN Secretary-General Guterres warned that a protracted conflict risks dragging the entire region into the conflict, whilst tanker traffic through the Strait of Hormuz has virtually ground to a halt following Iran’s rejection of Oman’s proposal to share control of the waterway.
- The Fed kept interest rates on hold, but Warsh’s comments took the market by surprise. The FOMC, led by its new chairman Kevin Warsh, kept rates at 3.5–3.75% in a 9–3 vote, with Warsh describing it as a “family squabble” and emphasising a move away from clear guidance on the policy path, shifting the responsibility for pricing to the bond market. Today in Europe, we face a very packed data calendar: preliminary Q2 GDP figures from France, Spain, Germany, Italy and the eurozone as a whole, as well as preliminary July CPI figures from Germany and Spain – the market is pricing in a roughly 64 per cent chance of another ECB move (a rate rise) in September.
- The Bank of England is due to announce its decision today at 13:00. The consensus strongly points to the rate being held at 3.75 per cent (vote likely to be 7–2), despite geopolitical tensions driving up inflationary pressure via oil prices. Following the decision at 13:30 GMT, Governor Bailey will hold a press conference, which may provide further guidance for September.
- Wall Street had a weak trading session following the Fed’s decision and the resumption of the war with Iran. The Dow fell by 1,153 points (-2.19 per cent), the S&P 500 by 1.52 per cent and the Nasdaq Composite by 1.74 per cent, ending the session more than 10 per cent below its record high in June. The yield on 30-year US bonds rose by more than 11 basis points to 5.21 per cent – the highest since 2007 – which dragged technology share prices down.
- US futures are rebounding this morning as the market digests the results from Big Tech. Dow futures are up 0.14 per cent, S&P 500 futures 0.35 per cent, and Nasdaq 100 futures as much as 0.78 per cent, as can also be seen in our summary (US100 +0.78 per cent, US500 +0.44 per cent). The market is quickly shifting its focus from geopolitics and interest rates to the Big Tech results announced after the close of Wednesday’s session.
- Meta and Microsoft following their quarterly results. Meta’s shares fell by around 10–11% after CFO Susan Li announced that spending on AI would continue to rise through to 2028 and beyond, whilst free cash flow plummeted to $784 million from $8.55 billion a year earlier. Microsoft, by contrast, gained around 7–8% in after-hours trading, thanks to a 43% rise in Azure revenue in Q4 and the maintenance of its forecast for positive free cash flow in FY27, despite capital expenditure of around $175 billion.
- Asian markets are mixed, with the KOSPI still in a liquidity crisis. The Nikkei 225 is up by around 1% today (recouping some of its losses), but the KOSPI is down by around 1.1% after falling by more than 10% earlier this week and by 6% in the following two sessions, prompting regulatory intervention by the South Korean government (limits on leveraged ETFs on Samsung and SK Hynix). SK Hynix is down a further 6% today, despite record results – operating profit rose by 557% to 60.5 trillion won, but fell short of analysts’ expectations, fuelling concerns about the memory sector being overvalued.
- Samsung – a bright spot in the memory sector, even as the stock market punishes the entire segment. Samsung’s semiconductor division reported a 250-fold increase in profit thanks to AI-driven demand for memory, with an operating profit of 89.2–89.5 trillion won (approx. US$62 billion), beating forecasts of 79.3–88.1 trillion won. The company has signed a contract with Broadcom worth over US$200 billion for chip supplies until 2030 and is finalising long-term agreements with its five largest data centre clients, giving it greater revenue visibility despite market volatility. The company’s shares are up by over 7% following the announcement.
- Currencies: the dollar weaker despite higher yields. The euro gained 0.70% against the US dollar, the pound 0.56%, whilst only the Australian dollar lost ground (-0.36%) during Wednesday’s session – an unusual reaction, as higher yields would normally support the dollar, which may reflect a general sell-off of US assets. This morning, the spot market is stabilising: EUR/USD -0.03%, GBP/USD -0.07%, USD/JPY +0.07% and the USD Index +0.12%.
- Commodities: oil surges on fears over the Strait of Hormuz; gold and silver consolidate after gains. Brent jumped 7.9% to $90.74, whilst WTI rose 6.6% to $84.46 in response to the escalating conflict with Iran and the closure of the Jazan refinery in Saudi Arabia following Houthi attacks. Gold, after rising by almost 1% on Wednesday (as a safe-haven asset), is correcting today by -0.58% to around $4,041, whilst silver is down -0.77% to $57.14 – a natural profit-taking move following a strong rally.
- Stablecoins are holding steady, whilst Bitcoin is up slightly this morning. After falling by 0.5% on Wednesday to $63,525, Bitcoin is up 0.25% this morning to around $63,900, as the market awaits further developments in the macroeconomic and geopolitical landscape.
- The key events in today’s trading session will be: GDP and CPI data from Europe, the BOE’s decision, Amazon/Apple/Coinbase results after the close of Wall Street, and developments regarding Iran and the Strait of Hormuz. OPEC+ is set to announce on 2 August an increase in supply of 188,000 barrels per day for September, which could limit oil price rises in the longer term, provided that geopolitical tensions ease. It is also worth monitoring the reaction of KOSP, Samsung I and SK Hynix – if volatility in South Korea persists, this could once again affect global sentiment towards the semiconductor sector.
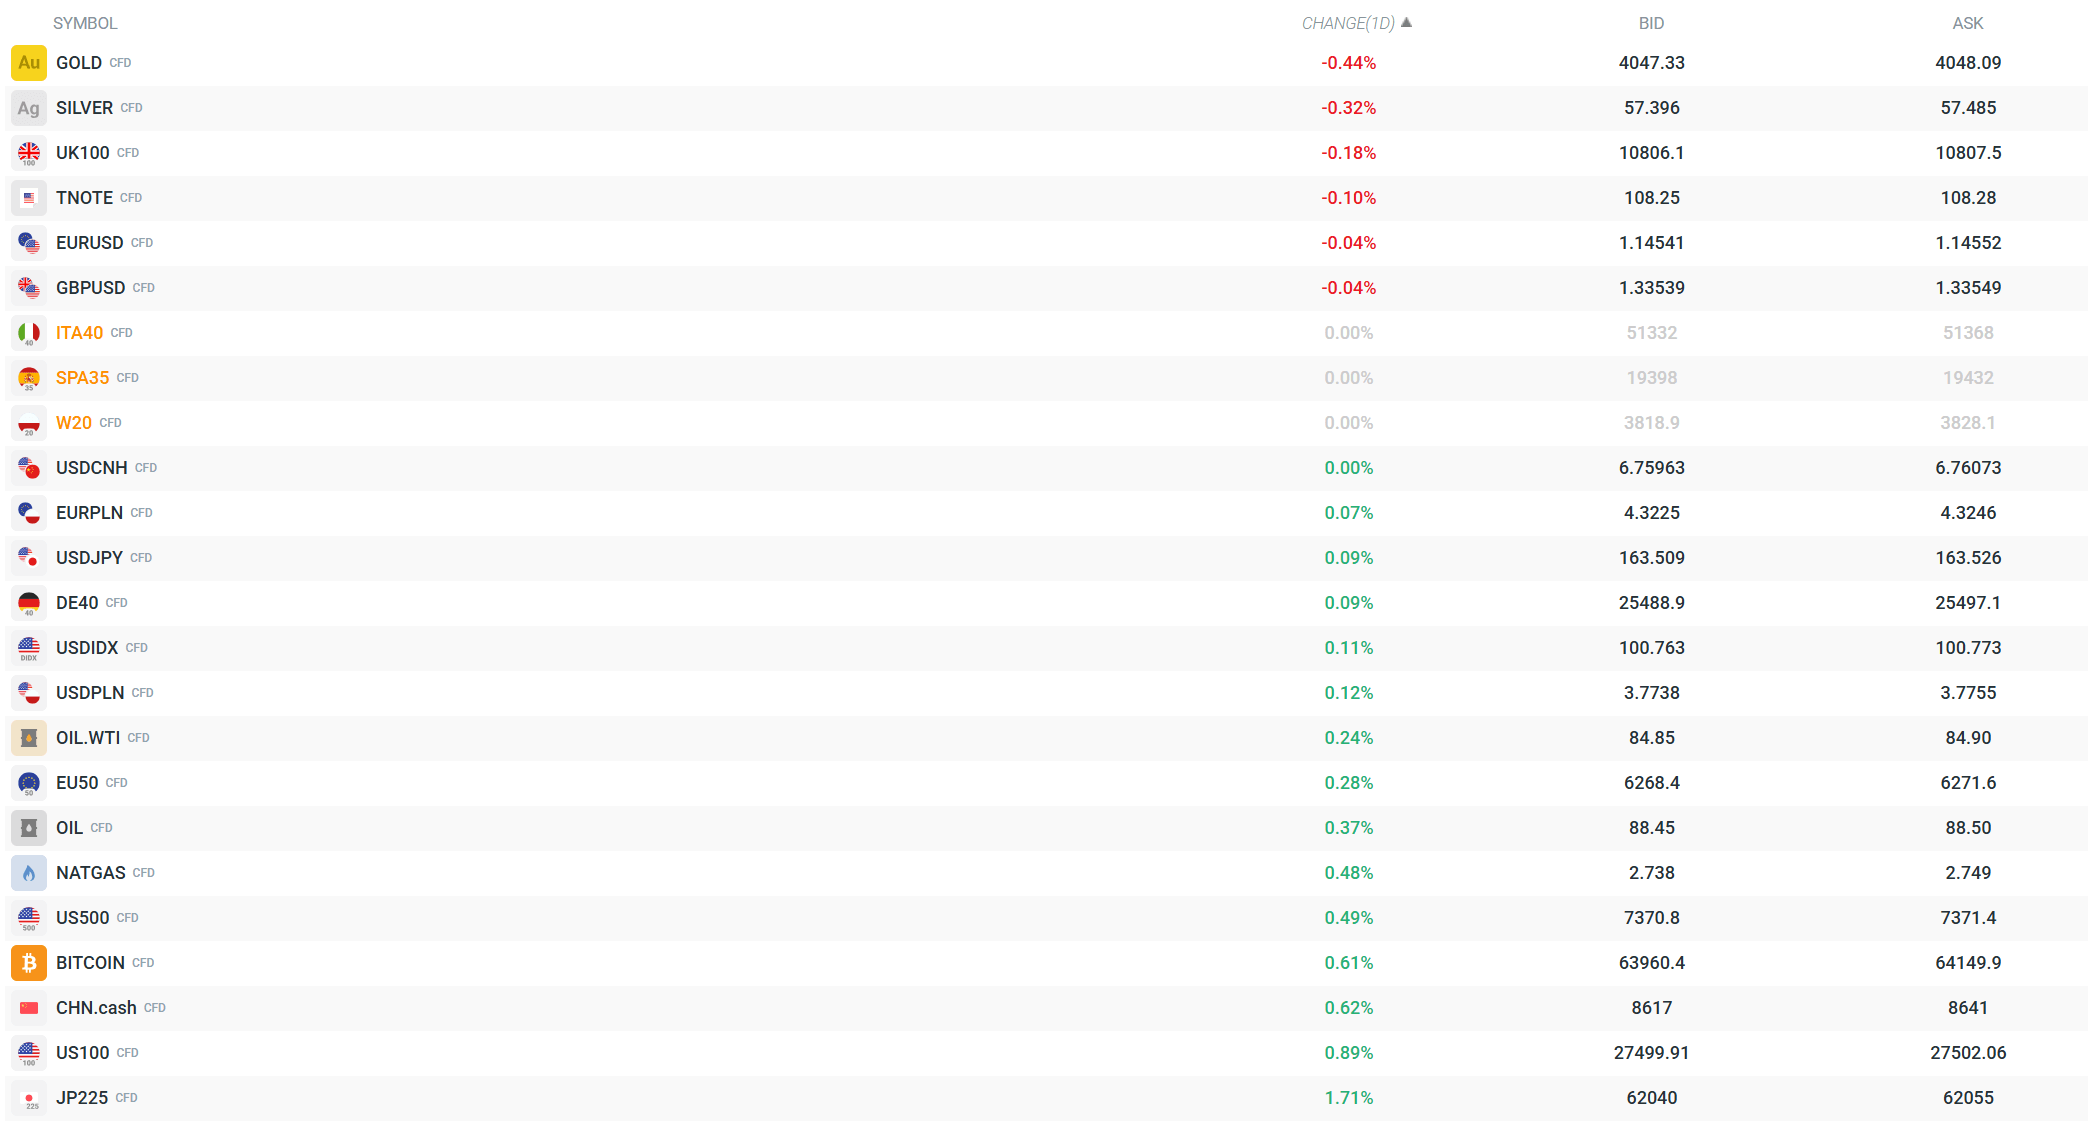
Volatility currently observed in selected instruments. Source: xStation



