S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Rheinmetall Earnings: Double-digit declines after the earnings release

Key takeaways
- Rheinmetall shares fell over ten percent to around 835 EUR following Q3 2026 results.
- Revenue reached 3.149bn EUR, missing market expectations of 3.200bn EUR.
- Free cash flow dropped to a negative 1.73bn EUR due to inventory buildup and investments.
- Management lowered full-year revenue guidance from the previous range down to 13.2bn EUR.
- Project Arminius negotiations for the German army faced delays and will not finalize this year.
Rheinmetall is experiencing a crushing correction after publishing its Q3 2026 results. The share price is down by more than ten percent in today’s session, falling to around EUR 835 per share. This is the company’s lowest share price since February 2025.
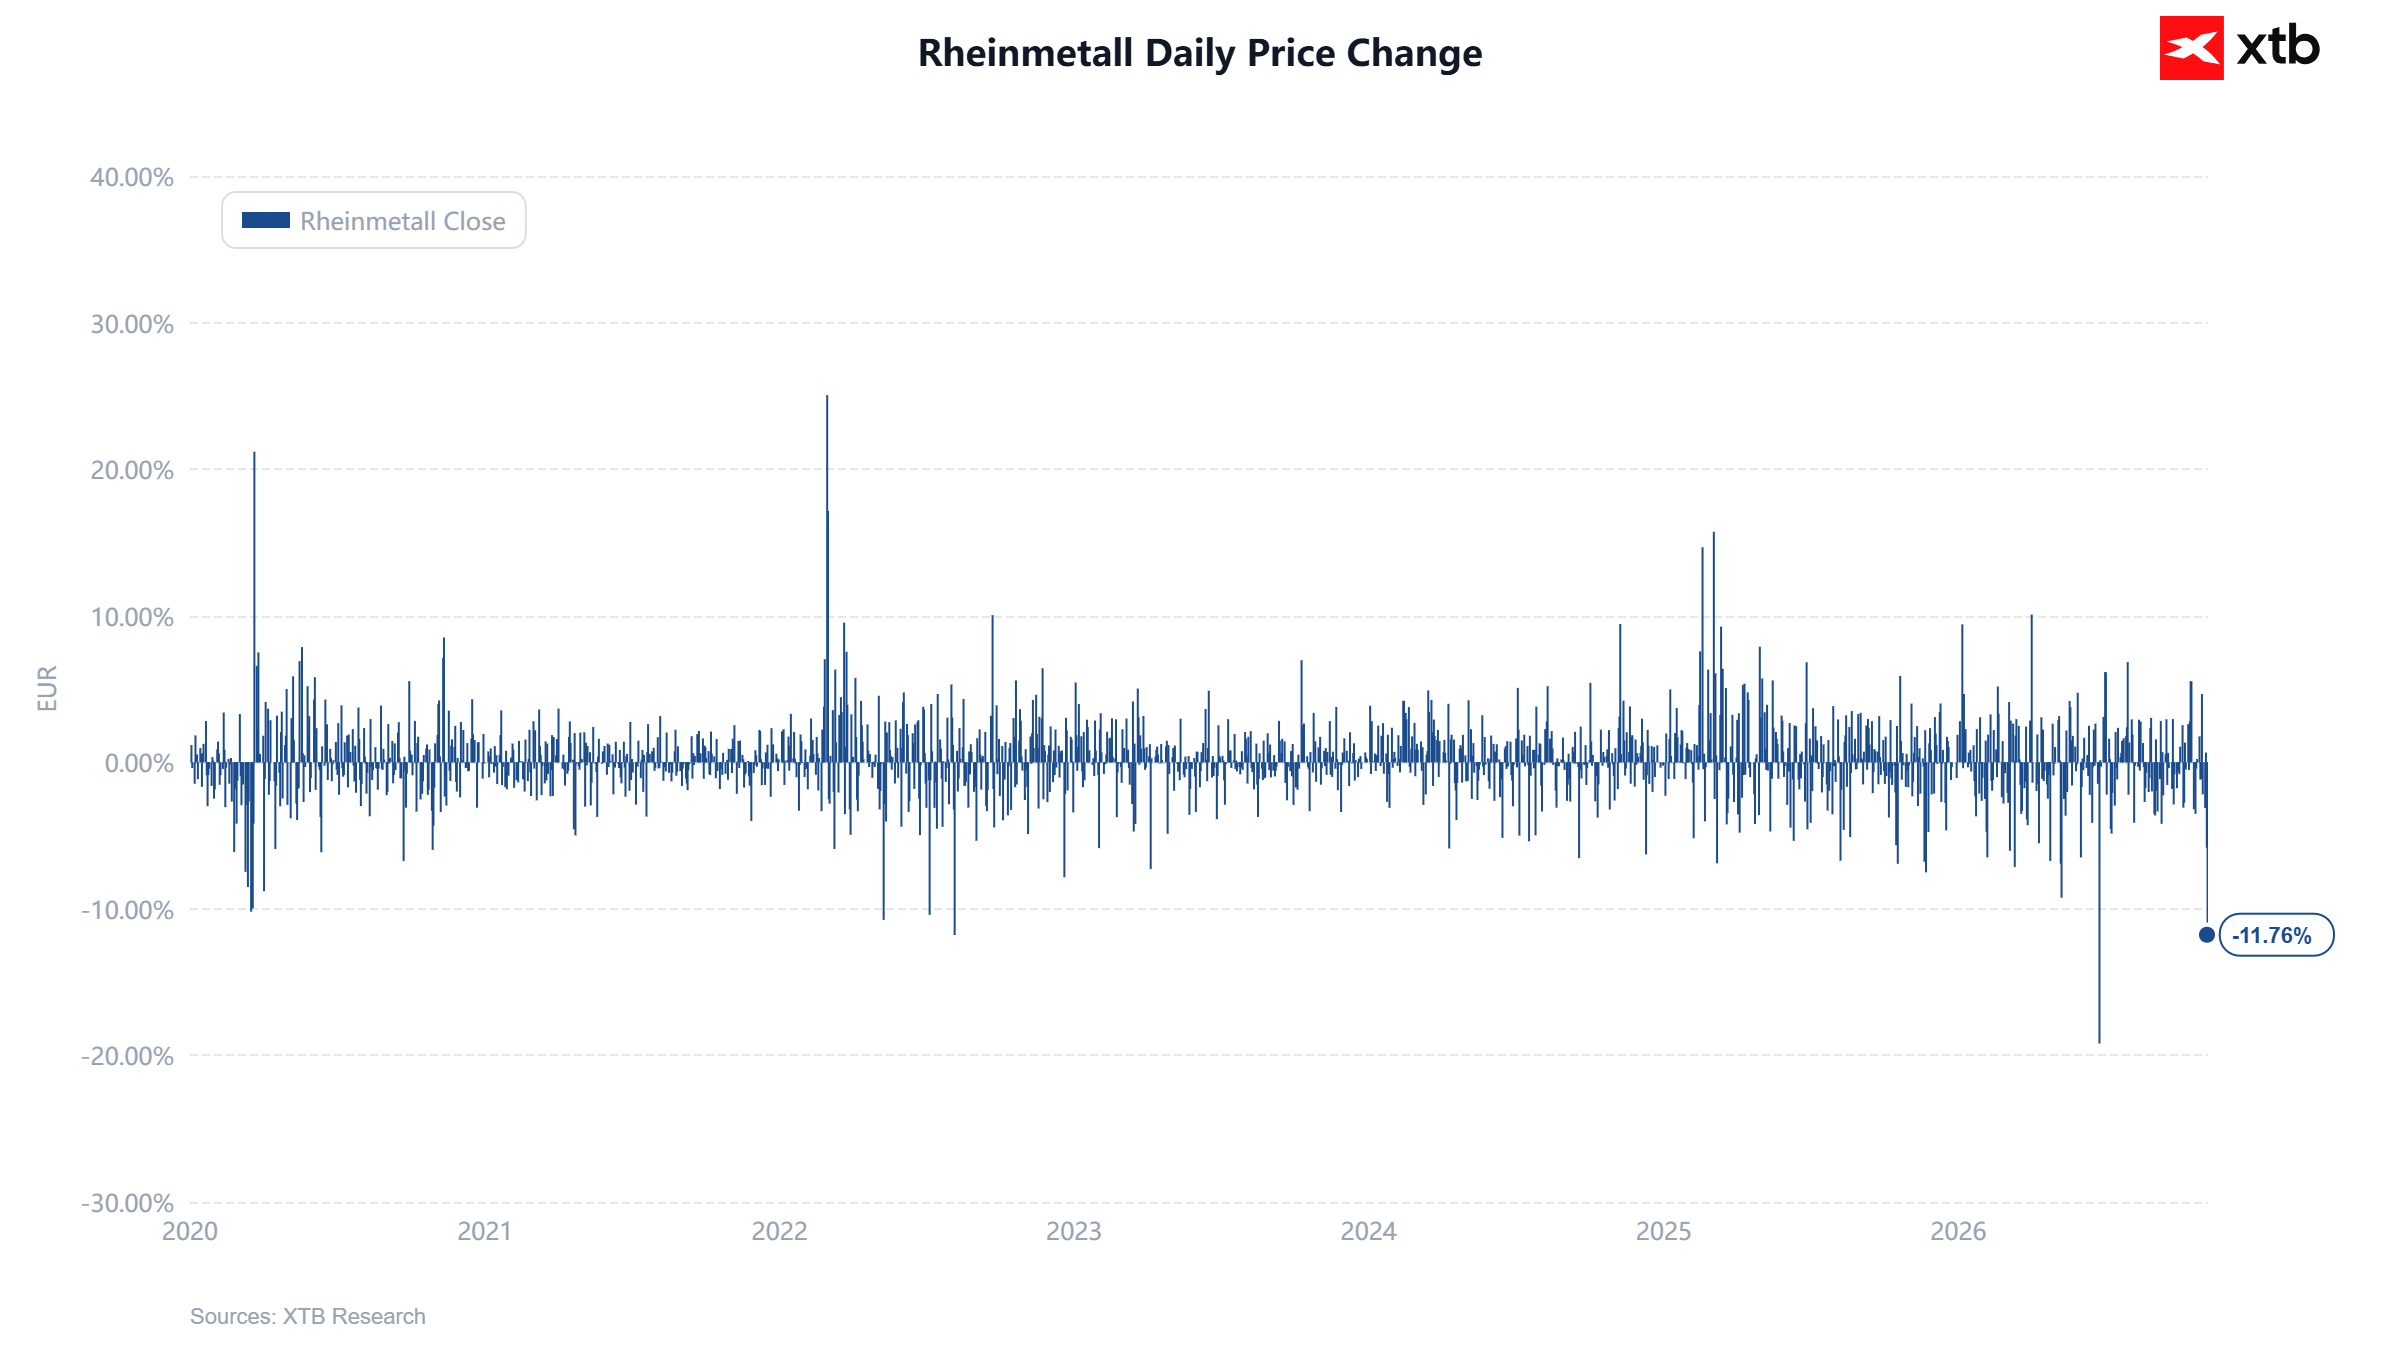
Some figures came in clearly below market expectations, although the biggest burden on the stock price is likely the outlook section presented by management.
Financial results
- Revenue reached EUR 3.149bn. This means a roughly 3% decline versus the previous quarter and a miss versus market expectations, which had been for revenue to hold at EUR 3.200bn. Sales look better on a YTD basis, as growth still stands at 38% and currently totals EUR 8.4bn.
- Gross margin fell to 47% versus the expected 55%. A major positive, however, is that the company managed to raise its operating margin to 16% (previously 13.1%), resulting in record operating profit of EUR 1.339bn for the first nine months of the year (up 69% year over year). This is an important long-term signal, as it addresses one of the company’s most fundamental problems, namely cost efficiency.
- Operating and net results are, however, only small consolation for shareholders, at least in the short term, due to the sharp drop in free cash flow. Free cash flow came in at negative EUR 1.73bn, which was a major disappointment versus the already modest level of around EUR 150m expected by the market.
- Management explains that the large decline is linked to the need to build up inventories and make investments intended to meet the company’s ambitious sales targets for next year.
- By segment, revenue from land vehicles and ammunition came in slightly below expectations, missing consensus by about 5%. Air defense systems and naval systems surprised on the upside, beating consensus by around 8% and 12%, respectively.
Guidance
Potentially the weakest element of the earnings call was guidance. The company lowered its forecast revenue from the EUR 13.7 to 14.2bn range to EUR 13.2bn. Another major issue is the reduction in the projected group operating margin from 19% to 18.5%. This implies a 5% to 10% decline in operating profit, although for now this is an extrapolation of trends rather than a formal forecast.
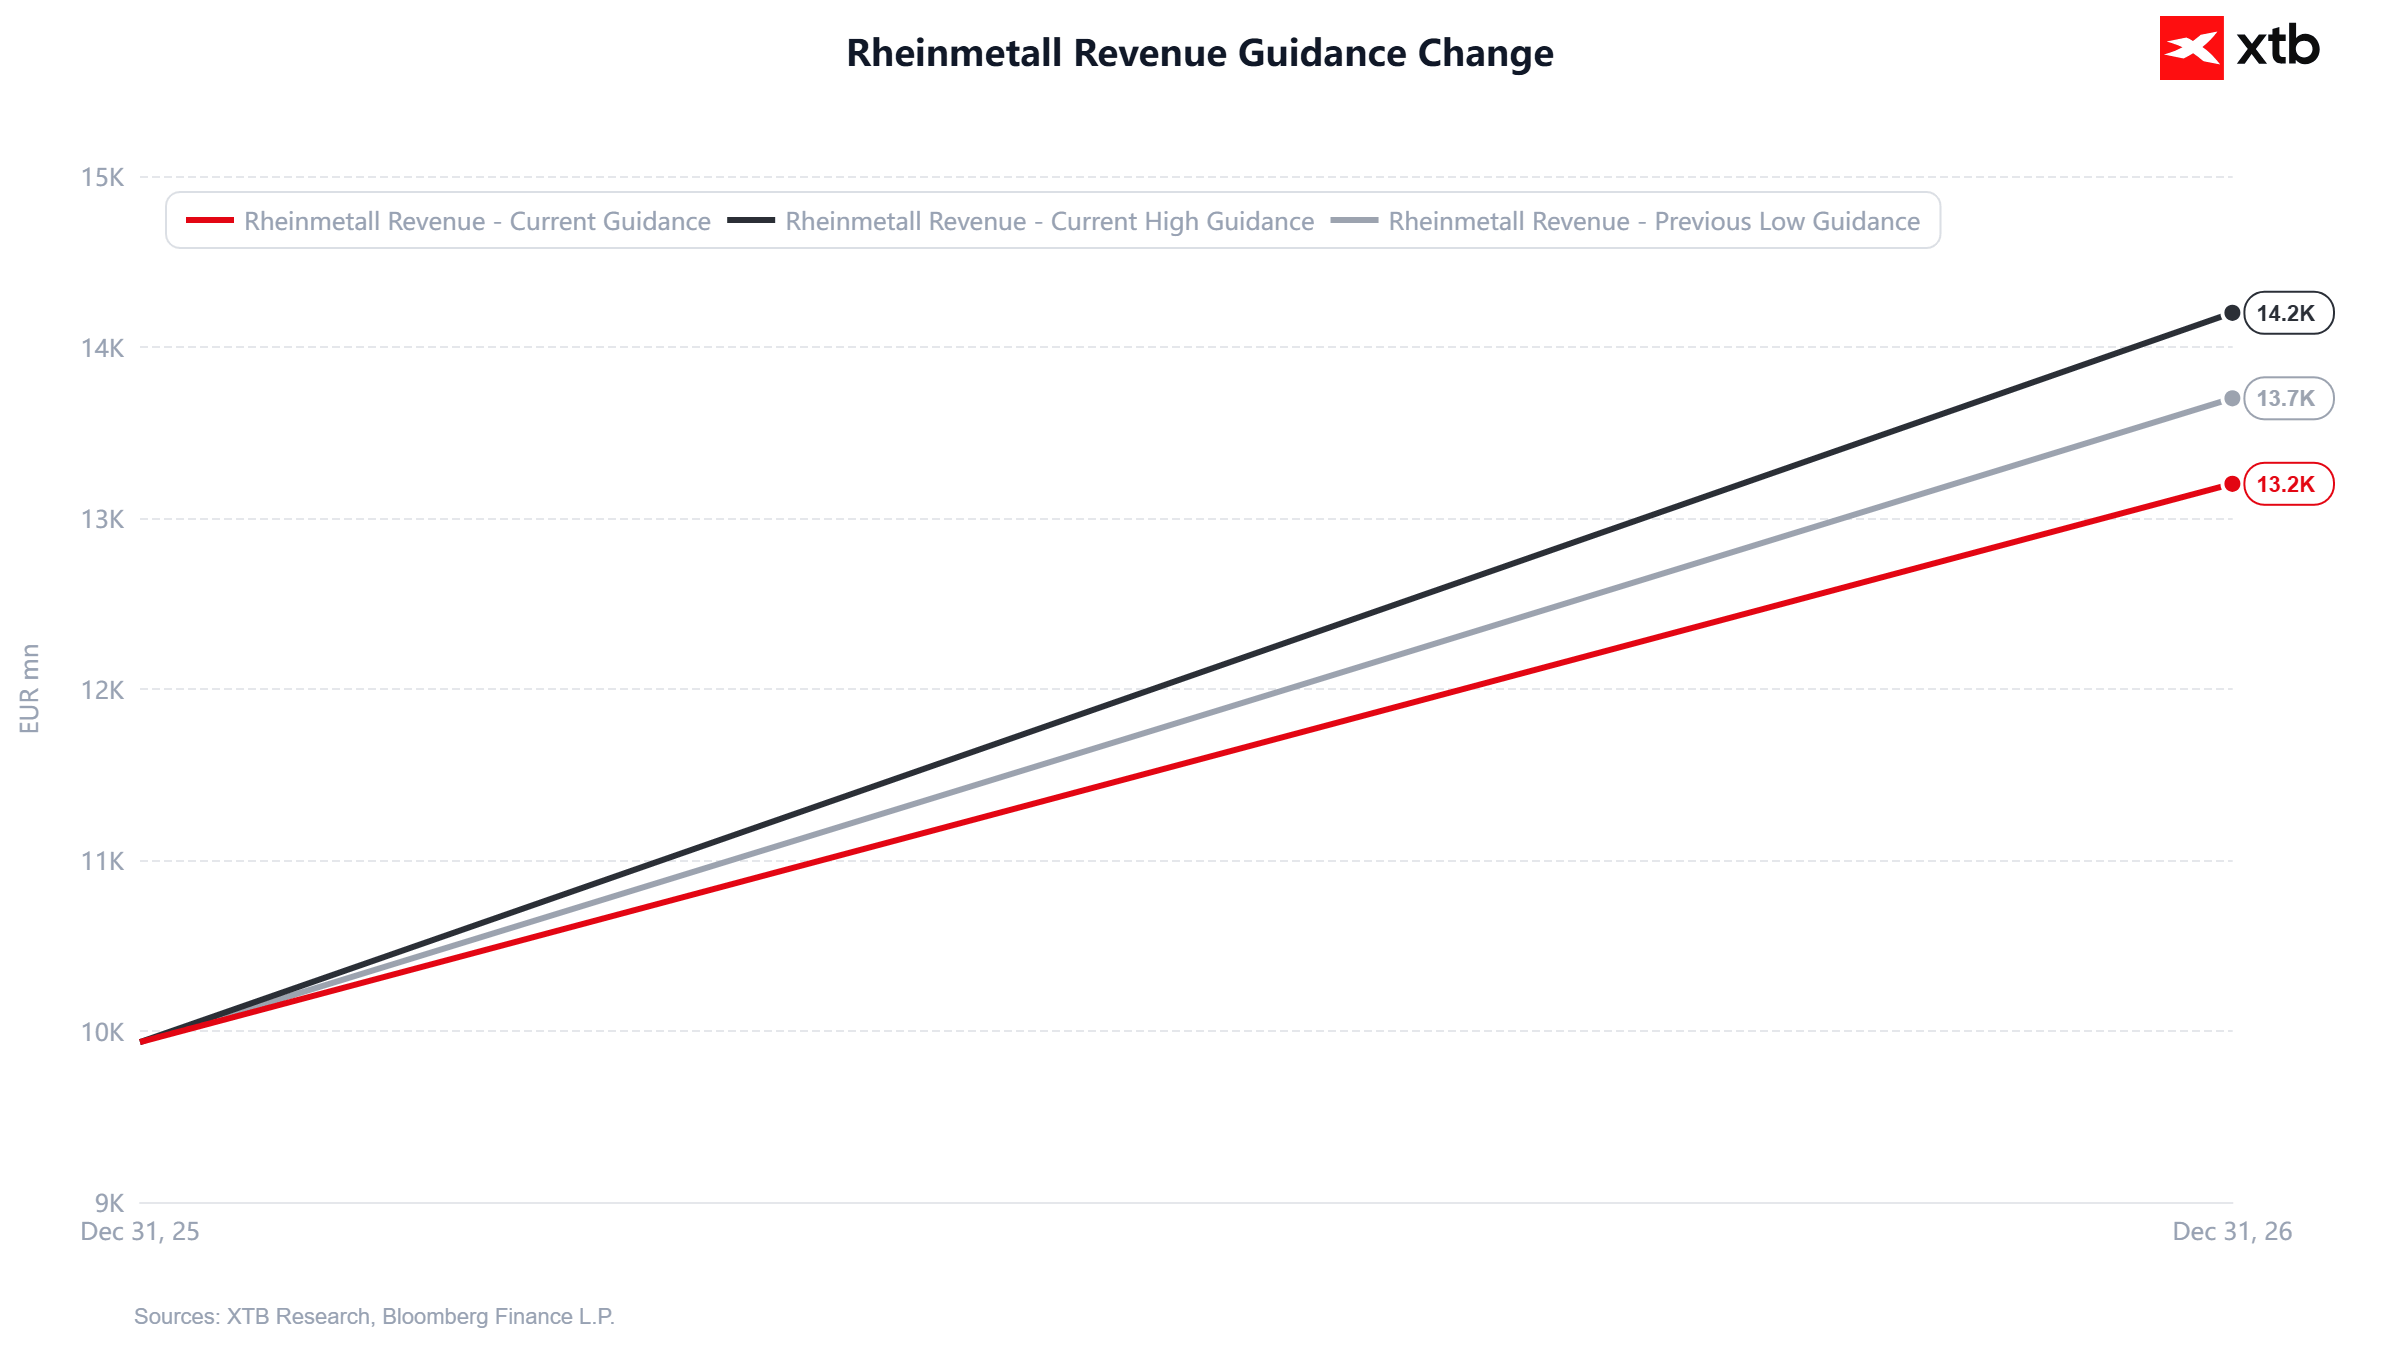
The guidance cut has several specific reasons cited by management and the CEO. The most important is the delay of “Project Arminius,” which is a very significant issue for Rheinmetall’s short-term results. Project Arminius is a broad rearmament program for the German army and includes, among other items, several thousand BOXER armored vehicles. Potential revenue from this program is currently estimated at EUR 40 to 80bn. The CEO pointed to delays in negotiations which, contrary to expectations, cannot be finalized this year.
Conclusion
At the moment, the company is suffering from a problematic mix of extreme and often inconsistent investor expectations combined with the specific nature of the business, which is not helped by the way company representatives communicate. Rheinmetall is showing unprecedented growth considering the industry and the scale of operations, but this growth comes at the cost of equally unprecedented investment, which means shareholder returns in the form of free cash flow are increasingly being pushed out in time. The company’s long-term prospects look as good today as they did several or a dozen months ago. At present, the key risks for the company, namely problems in the naval segment and delays to the main order package in Germany, have materialized. Even so, even the most conservative forecasts point to the maintenance of a very high growth rate. In a broader perspective, this means that while the company’s long-term outlook remains intact, in the short term further significant pressure on the share price is possible.
RHM technical analysis (D1)
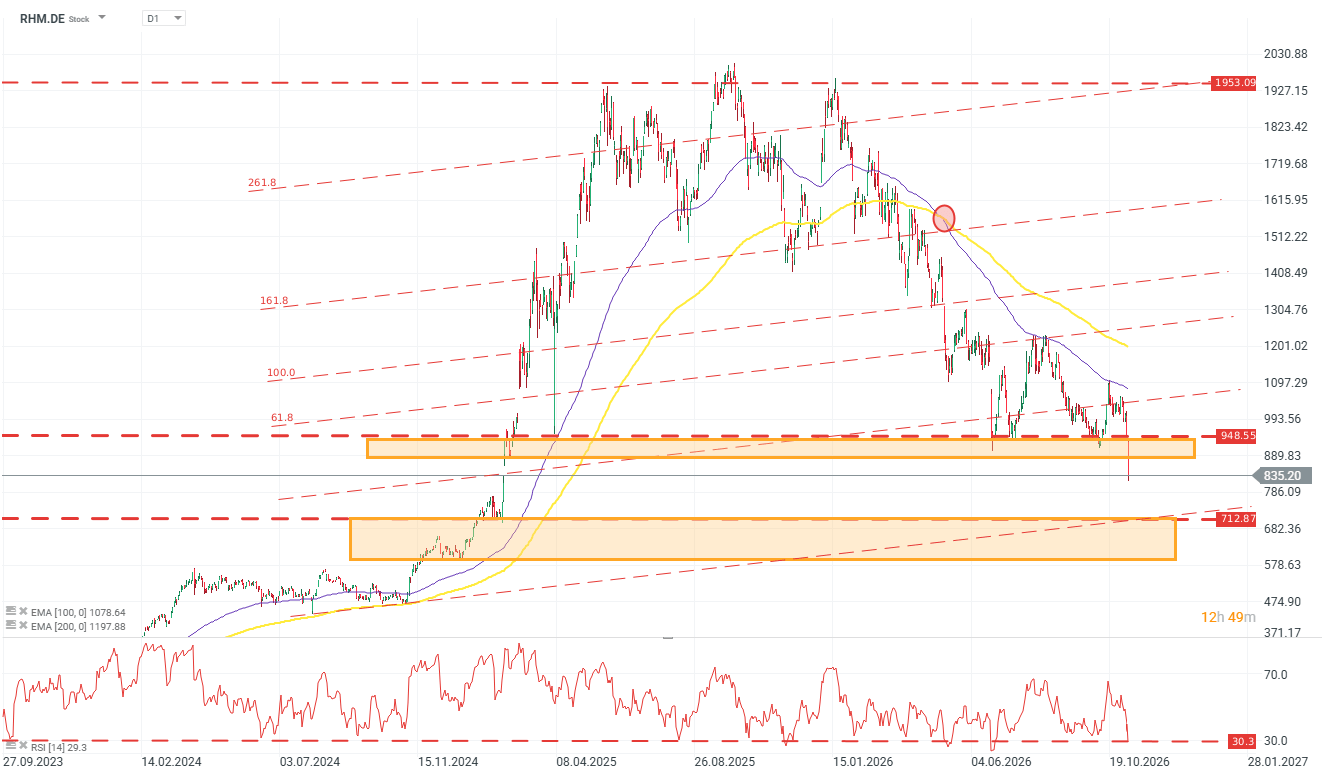
After breaking the resistance at around EUR 950, the next resistance zone, indicated by levels from December 2024, is the range between around EUR 750 and EUR 700. Additional support in this area is also provided by the lower boundary of the multi-year uptrend. RSI [14] reaches 30, which corresponds to an oversold level. Source: xStation5.