S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Baltic Dry Index Fell for a Second Day as Capesize Rates Weakened While Panamax Freight Advanced – Monday Shipping Market Outlook

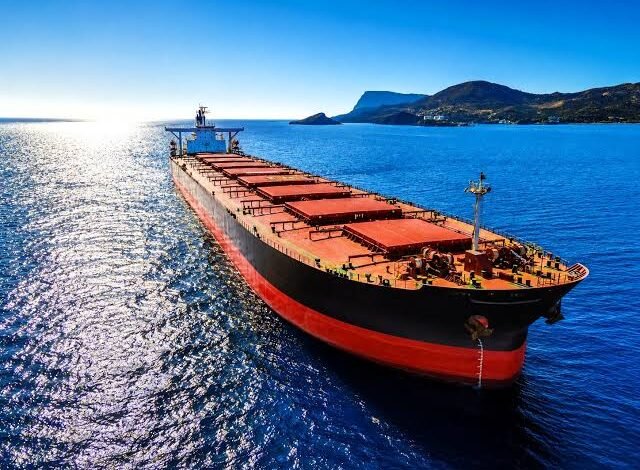
The Baltic Dry Index (BDI) declined for a second consecutive session on Friday, falling 0.1% to 2,898 points, as weakness in capesize and supramax freight rates offset gains in the panamax segment.
The benchmark index also recorded a 2.8% decline over the week, highlighting softer overall conditions in the dry bulk shipping market.
Capesize rates, which reflect the cost of transporting large cargoes such as iron ore and coal, fell 0.3% to 4,502 points. The supramax index declined 0.2% to 1,810 points.
However, panamax freight rates moved in the opposite direction, advancing eight points to 2,140, their highest level since October 22. The contrasting performance highlighted differences in demand and pricing conditions across vessel categories.
Heading into Monday, traders will be watching whether the benchmark index extends its two-session decline or whether stronger panamax rates provide support to the wider shipping market.
Baltic Dry Index Market Snapshot
| Freight index | Friday movement | Latest reading |
|---|---|---|
| Baltic Dry Index | -0.1% | 2,898 points |
| Capesize Index | -0.3% | 4,502 points |
| Supramax Index | -0.2% | 1,810 points |
| Panamax Index | +8 points | 2,140 points |
| Weekly BDI performance | -2.8% | Weekly decline |
Baltic Dry Index Extended Its Decline for a Second Session
The Baltic Dry Index fell 0.1% on Friday to 2,898 points, marking its second consecutive daily decline.
The benchmark measures the cost of transporting dry bulk commodities by sea and provides an important indicator of activity across global shipping markets.
Its 2.8% weekly decline indicated that overall freight conditions weakened during the reporting period.
The latest movement suggests that gains in selected vessel categories were insufficient to offset weakness elsewhere in the dry bulk market.
Capesize Freight Rates Fell as Large-Vessel Market Weakened
The capesize index declined 0.3% to 4,502 points on Friday.
Capesize vessels typically transport large cargoes of approximately 150,000 tonnes, including iron ore and coal.
The decline contributed to the broader weakness in the Baltic Dry Index, reflecting softer freight pricing in the large-vessel segment.
Traders will be watching whether capesize rates stabilise on Monday, particularly given the importance of iron ore and coal transportation to global dry bulk shipping activity.
Supramax Index Also Recorded a Decline
The supramax index fell 0.2% to 1,810 points, adding to Friday’s negative performance across parts of the dry bulk market.
Although the decline was modest, it reinforced the broader downward movement in the benchmark index.
The supramax segment will remain important to monitor for signs of stabilisation during the coming sessions.
Panamax Freight Rates Reached Their Highest Level Since October 22
Panamax freight rates provided the strongest positive signal in Friday’s shipping market update.
The panamax index advanced eight points to 2,140, reaching its highest level since October 22.
Panamax vessels typically carry between 60,000 and 70,000 tonnes of commodities, including coal and grain.
The improvement contrasted with the declines in capesize and supramax rates, highlighting stronger relative performance in the panamax segment.
Whether this strength can continue into Monday will be important in determining whether panamax rates can provide broader support to the Baltic Dry Index.
Bullish Sentiment
- Panamax freight strength: The panamax index advanced eight points to its highest level since October 22.
- Positive performance in a major vessel category: Panamax gains demonstrated that freight conditions were not weakening uniformly across all vessel classes.
- Potential benchmark support: Continued panamax strength could help offset further weakness in capesize and supramax rates.
- Dry bulk trade relevance: Continued transportation requirements for iron ore, coal and grain will remain important to shipping demand.
Bearish Sentiment
- Second consecutive daily decline: The Baltic Dry Index fell for a second session, indicating continued short-term weakness.
- Weekly losses: The benchmark index declined 2.8% over the week.
- Capesize weakness: The capesize index fell 0.3%, adding pressure to the overall benchmark.
- Supramax decline: The supramax index also moved lower, confirming that weakness extended beyond the largest vessel category.
Baltic Dry Index Forecast: What Traders Are Watching
The Baltic Dry Index enters the new week with a mixed outlook following Friday’s contrasting vessel performance.
Capesize and supramax rates remained under pressure, while panamax freight reached its highest level since October 22.
The key question is whether the improvement in panamax rates can offset continued weakness in the other segments.
Traders will be monitoring:
- Whether the Baltic Dry Index extends its two-session decline.
- Whether capesize rates stabilise following Friday’s fall.
- Whether supramax freight rates recover.
- Whether panamax rates maintain their recent strength.
- Whether the 2.8% weekly decline develops into a broader downward trend.
Dry Bulk Shipping Supply Outlook
The supplied market update does not include vessel availability, fleet capacity, port congestion or shipping supply figures.
Consequently, Friday’s movements do not establish whether the changes in freight rates were driven by vessel availability or other supply-side developments.
Fleet availability and shipping capacity will remain important factors in determining freight pricing during the coming sessions.
Dry Bulk Shipping Demand Outlook
Demand for dry bulk shipping remains closely linked to international transportation of commodities such as iron ore, coal and grain.
The capesize and panamax segments are particularly relevant to these cargo categories, with different vessel sizes serving different transportation requirements.
Friday’s contrasting movements suggest that freight conditions varied across vessel categories. However, the supplied figures do not identify specific changes in cargo volumes or underlying commodity demand.
Further shipping activity and freight data will be needed to establish whether the recent weakness reflects softer transportation demand or short-term pricing adjustments.
Market Outlook for Monday’s Open and Coming Sessions
Monday’s opening bias: Cautious to bearish for the overall Baltic Dry Index, with panamax rates providing a positive countertrend.
The Baltic Dry Index enters Monday after declining for a second consecutive session and recording a 2.8% weekly loss.
The weakness in capesize and supramax rates suggests that the broader dry bulk market remains under pressure. However, panamax freight rates have demonstrated relative strength, reaching their highest level since October 22.
If panamax rates continue advancing, they could help limit further losses in the benchmark index. Conversely, additional declines in capesize and supramax rates could reinforce the negative direction.
Key developments traders should watch on Monday:
- Whether the Baltic Dry Index records a third consecutive daily decline.
- Whether capesize rates recover from Friday’s 0.3% fall.
- Whether supramax freight stabilises.
- Whether panamax rates extend their recent advance.
- Whether the benchmark begins recovering from its 2.8% weekly decline.
Overall, the near-term outlook remains cautiously bearish for the Baltic Dry Index, although the strength in panamax freight offers some support. The direction of capesize and supramax rates will be particularly important in determining whether the wider shipping market stabilises or continues lower.
Currency Hedger – Market Contributor
Currency Hedger provides market participants with currency exchange, international payment and hedging solutions designed to support businesses managing cross-border financial exposure.
Disclaimer: This article is provided for informational and market commentary purposes only. It does not constitute investment advice, financial advice or a recommendation to buy or sell any financial instrument. Shipping and freight markets can experience significant volatility due to changes in global trade, vessel availability, commodity demand and transportation costs. Readers should conduct their own research before making investment decisions.