Global Markets
S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market

S&P 500 — US Large Cap Index
NASDAQ 100 — Tech Growth Index
Dow Jones — Industrial Average
FTSE 100 — UK Blue Chips
Euro Stoxx 50 — Eurozone Leaders
DAX 40 — German Equities
CAC 40 — French Market Index
Nikkei 225 — Japan Benchmark
Hang Seng — Hong Kong Index
Shanghai Composite — China Mainland
ASX 200 — Australian Market
TSX Composite — Canada Index
Nifty 50 — India Large Cap
STI Index — Singapore Market
KOSPI — South Korea Index
Bovespa — Brazil Equities
JSE Top 40 — South Africa Index
IPC Index — Mexico Market
AED • EUR • GBP • USD IBANs   |   CROSS BORDER FX   |   LOCAL CURRENCIES   |   GLOBAL COVERAGE
Crude OilGeo-PoliticalMarketsOpinionTechnical AnalysisWTI Oil

China, Saudi Aramco and Oil – What’s Next?

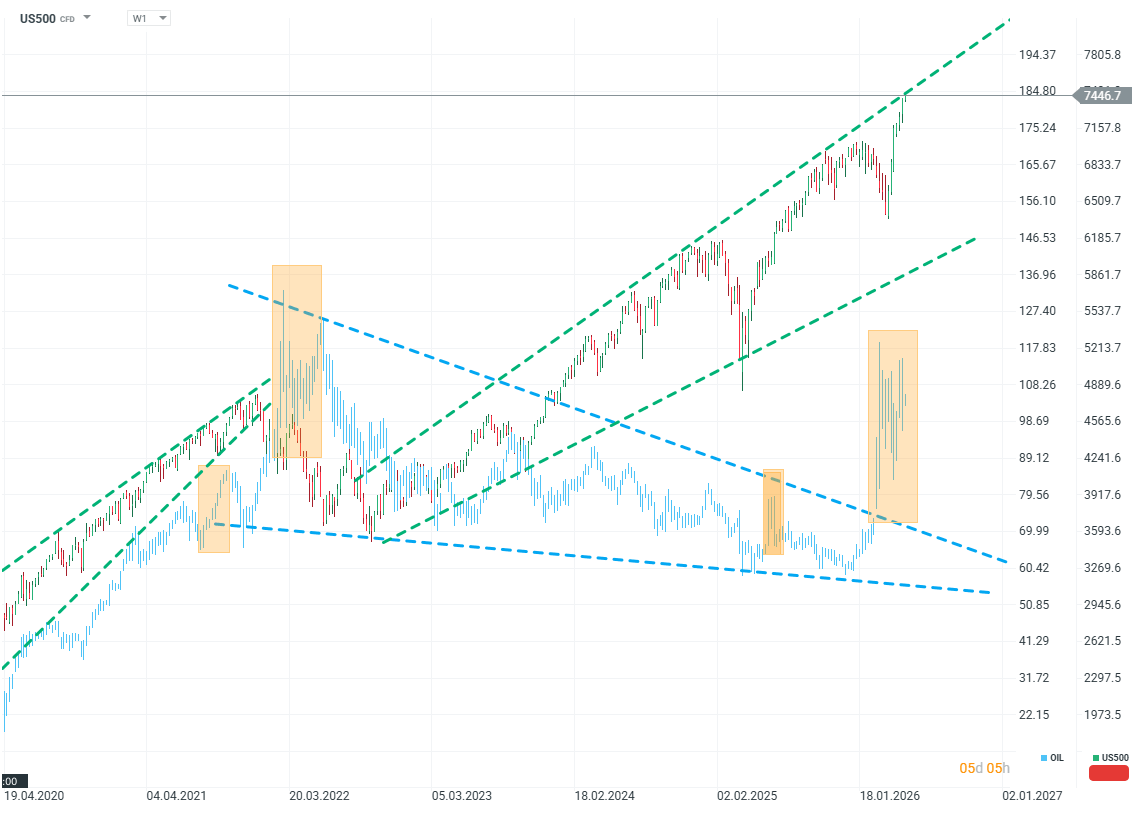
One of the most striking developments in recent months is how completely sentiment and expectations have diverged – clearly visible in the difference between commodity-market analysts and equity-market analysts. Commodity analysts are sounding the alarm and warning of a catastrophe stemming from the loss of around 20% of global oil and fuel supply. At the same time, equity analysts are explaining successive upward revisions to EPS forecasts.

Who is right? US500 vs OIL (W1)
Source: xStation5

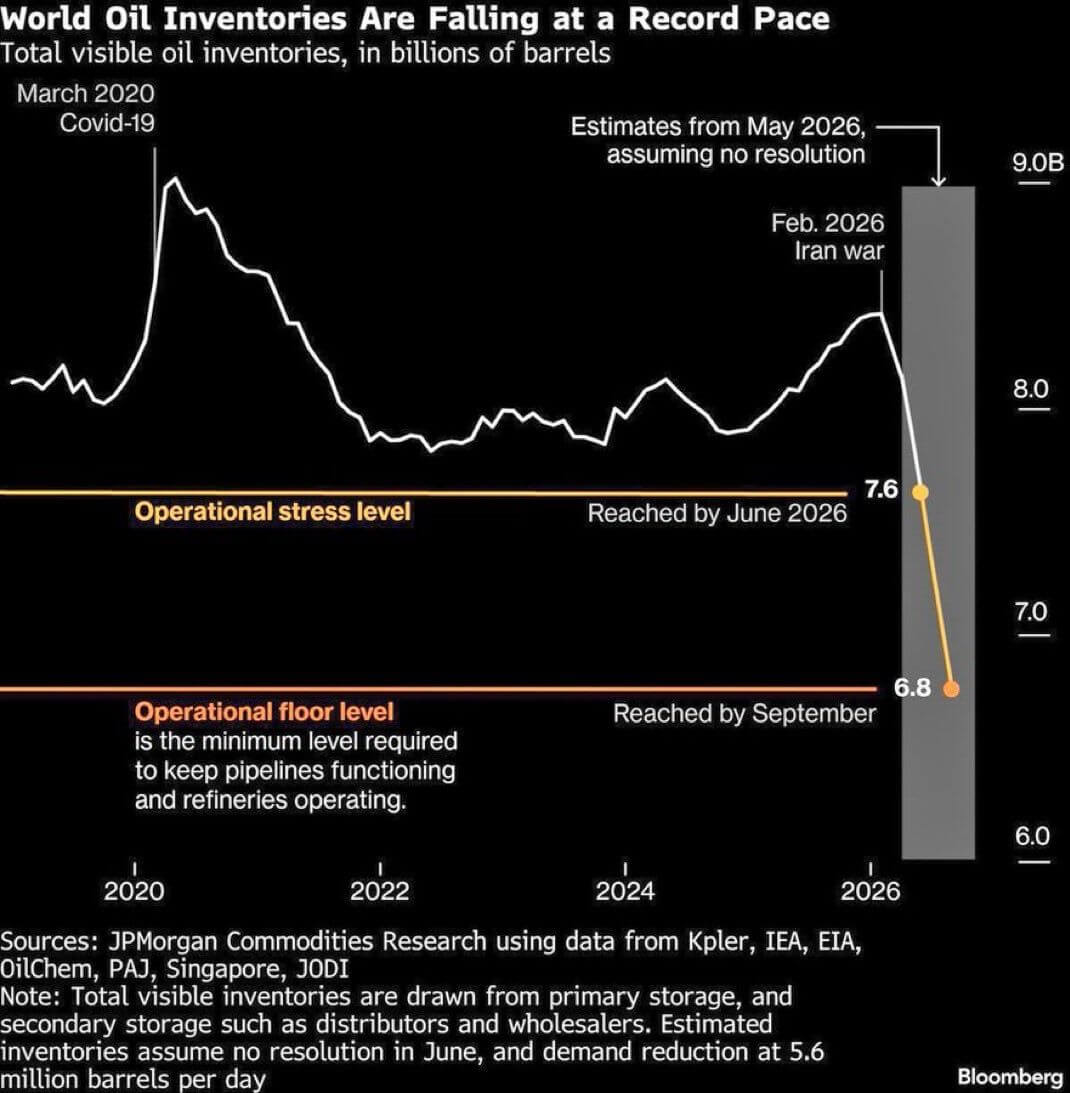
For now, a mysterious stalemate can still be observed – indices and stock prices are setting new records even though oil prices are far above the levels expected just a few months ago. Saudi Aramco is the world’s largest energy company, controlling an industry built around crude oil in Saudi Arabia. The company’s CEO has commented on the market situation. The CEO uses strong language. According to Amin Nasser, the market is in a period of deep imbalance between supply and demand. He estimates that even if the Strait of Hormuz were reopened tomorrow, the market would need about a year to normalize. The company’s president speaks of a loss of one billion barrels of oil supply and points out that the scale of the crisis is unprecedented. It is also hard to say that the current situation is not beneficial for the company. Saudi Arabia built the powerful “East–West” pipeline across the Arabian Desert precisely for a scenario like the one unfolding now. At the same time, the company’s results show that the surge in oil prices drove net profit up by nearly 25% in Q1 2025. What could be the reason why oil prices seem to be reacting rather cautiously to a crisis of this magnitude?
Source: Bloomberg Finance Lp

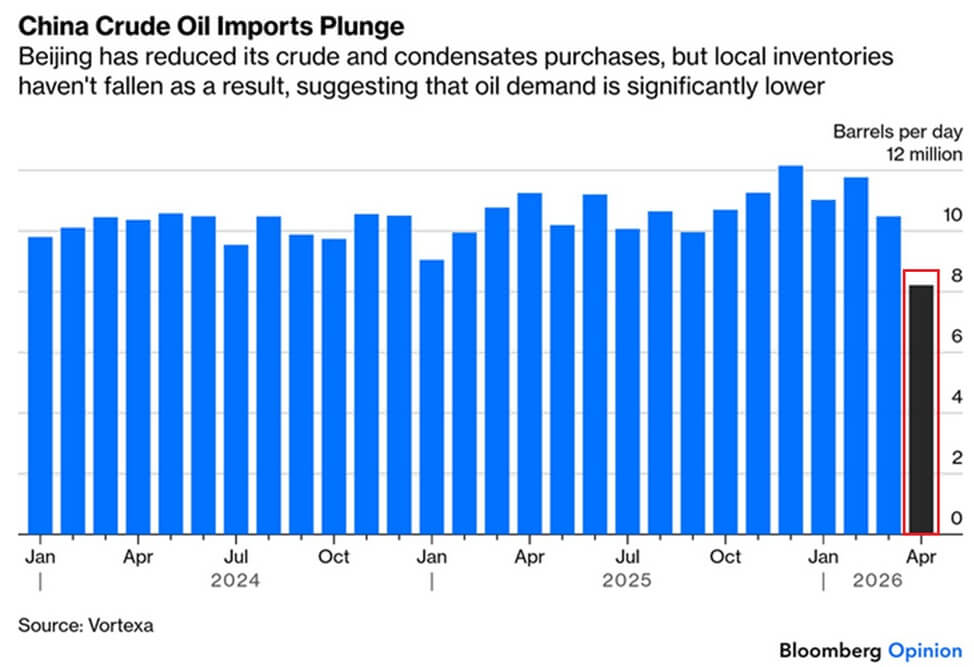
One factor highlighted by both Morgan Stanley and Bloomberg analyses is inventories – oil stockpiles are among the most important elements. The most important player in this context is China. China imported about 25–35% of its oil from the Persian Gulf. At the same time, the latest data show that China’s oil imports fell from 12 million barrels to just over 8 million—a drop of more than 3 million barrels, or over 30%. This is no coincidence: China used falling oil prices in 2025 to build a huge stockpile of crude. Were these stockpiles built precisely for such a contingency?
Source: Bloomberg Finance Lp

It’s impossible to say – and in practice it doesn’t matter. What it effectively means is that, due solely to China’s actions, we may see a significant delay in how reduced supply feeds through into prices. China is absorbing shortages and inflationary pressure—and has a strong incentive to do so. Chinese industry remains in a slowdown phase, while maintaining trade with the West is an imperative for China. Higher domestic inflation could, under current circumstances, help reduce the real burden of rising debt and stimulate consumption and investment. Meanwhile, the West avoids a recession – sone that would be just as painful for China as it would be for the West itself. What’s crucial to understand is that this market freeze will persist as long as China continues to de facto subsidize global disinflation. This may be one of the key yet rarely mentioned issues in the context of the upcoming Trump-XI meeting.

Register a Revolut Business Account
```

Market Analysis & Disclaimer

The market information, analysis, commentary, forecasts and opinions contained in this publication are provided by Octalas Group Ltd on behalf of Today Markets and Currency Hedger using information and data obtained from sources believed to be reliable. However, Octalas Group Ltd, Today Markets and Currency Hedger do not warrant or guarantee the accuracy, completeness or timeliness of the information presented and accept no responsibility for any loss or damage arising from reliance upon information contained herein, to the extent permitted by applicable law.

Market forecasts, expectations and opinions are based on analysis of available information and a number of assumptions regarding economic, financial, political and market conditions. Such assumptions may prove to be incorrect, and actual market developments may differ materially from those described or anticipated.

Nothing contained in this publication constitutes investment advice, financial advice, a personal recommendation, an offer, solicitation or invitation to buy, sell or otherwise transact in any financial instrument or investment product. The information is provided for general informational and educational purposes only and does not take into account the investment objectives, financial situation, experience or particular circumstances of any individual reader.

Past performance is not indicative of future results. Financial markets, including foreign exchange, commodities, equities, derivatives and other financial instruments, involve risk and prices can move rapidly. Readers should conduct their own independent research and, where appropriate, obtain advice from an appropriately authorised financial professional before making any investment or trading decision.

Where this publication refers to Today Markets, it represents market news, research, analysis and commentary published for informational purposes. Where Currency Hedger is referenced, it represents commentary concerning foreign exchange, currency exposure, international payments and hedging-related topics. References to particular financial instruments, markets, companies, currencies or commodities should not be interpreted as a recommendation to transact in them.

Octalas Group Ltd, Today Markets and Currency Hedger may have commercial interests or relationships with businesses, financial-service providers, technology providers or other market participants mentioned in their publications. Where relevant, such relationships or interests may create potential conflicts of interest. Appropriate measures are intended to be taken to ensure that published analysis and commentary are presented objectively and that commercial considerations do not determine the substance of market analysis.

The views expressed in this publication are those of the author or contributors at the time of publication and may change without notice as market conditions develop. Readers should not assume that any information contained herein has been updated following publication.

Related Articles

Leave a Reply

Your email address will not be published. Required fields are marked *

Back to top button