S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Shares of Chocoladefabriken Lindt & Sprüngli (LISN.CH) fell as much as 8.7% on Tuesday, hitting their lowest level since February 2021, after the Swiss chocolate maker lowered its sales growth forecast for the second time this year. For the first time in more than four years, the company’s stock price fell below 8,000 francs, placing it at the very bottom of the European STOXX 600 index. The management board, led by CEO Adalbert Lechner, cut its organic sales growth forecast for 2026 to a range of 0–2%, down from the previous 4–6%—and well below the market consensus of 3.9%. This is the second revision in six months; the company announced the first one in March.
Europe as a Source of Problems
Lindt cited weakening demand in three key markets—Germany, Switzerland, and Austria—as the main reason, noting that consumers there have become exceptionally price-sensitive following a series of price hikes. Some products have risen in price by as much as 50% in recent years, which ultimately resulted in lower-than-expected orders, particularly in the segment of seasonal products and higher-priced chocolate gift boxes. Added to this was a record-breaking heat wave, which is estimated to have shaved off about 1.5 percentage points from growth. The price increases are driven by historically high cocoa prices—in the last six months alone, the commodity has risen by about 80%, and LCCc2 futures in London have climbed back above 4,300 GBP per metric ton. Although prices have fallen from their peaks, they have been rising again since February amid concerns about a smaller harvest in West Africa during the 2026/27 season, due to plant diseases, unfavorable weather, and the risk of a strong El Niño.
The myth of “pricing power” is under pressure
What hurts investors the most, however, is what this price cut says about Lindt’s business model itself. For years, the company’s pricing power—stemming from the brand’s premium image—has been its bargaining chip: the market believed that Lindt could easily pass on rising costs to customers without losing sales volume. That assumption is now being called into question. “The second downward revision in six months is undermining Lindt’s reputation as a provider of reliable forecasts, which is a key pillar of its premium valuation,” wrote Vontobel analyst Jean-Philippe Bertschy. “Pricing power, long a strength of Lindt, is now being put to the test.”
Answer: lower prices and smaller packages
In response, the company announced price cuts—first as part of its holiday promotion, and then, starting in January, more broadly across its entire product line. Lechner also announced smaller package sizes, which are intended to encourage more frequent purchases and better fit consumers’ budgets. The company expects to return to positive volume growth in 2027, supported by the normalization of cocoa costs (though its hedging strategy is delaying the benefits), greater investment in the brand, and cost savings. It has no plans for layoffs but has implemented a hiring freeze. Despite cutting its sales forecast, Lindt maintained its target of improving its EBIT margin by 20–40 basis points in 2026, as well as its medium-term organic growth targets of 6–8% starting in 2028. The Broader Industry Context
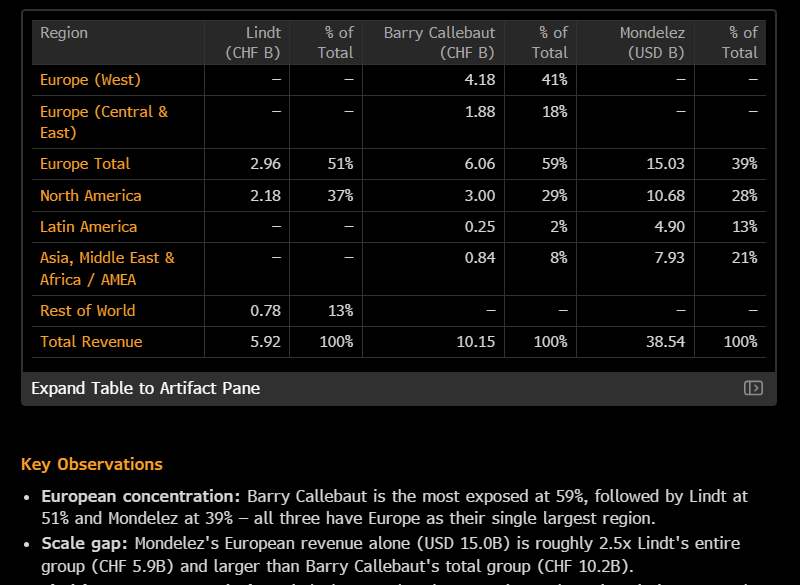
Signs of weakness are evident across the entire industry. In July, Barry Callebaut—which generates as much as 59% of its revenue in Europe—forecast a 1% decline in annual volumes. Mondelez is also under pressure; Europe remains its largest market as well, although its stock has recently been more stable than that of its Swiss rivals. Source: Bloomberg Financial Lp The next test will be the presentation of the annual results in January 2027. If Lindt fails to show a return to volume growth by then, its medium- and long-term goals will also be called into question—and a price-to-earnings ratio of 27 times projected earnings, historically low for this company, may no longer serve as a barrier to the continuation of the current downward trend.