S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Deutsche Bank, UBS, and Santander earnings in the spotlight

European stock markets are edging lower on a day dominated by quarterly results announcements — the STOXX 600 is down by around 0.2–0.3%, the Euro Stoxx 50 is down 0.18%, whilst the CAC 40 and the UK’s FTSE 100 are retreating by around 0.12–0.14%; the German DAX is holding on to a symbolic gain (+0.03%), and the WIG20 is virtually flat (-0.02%). Investors are sifting through a flood of reports — mainly from the banking sector — whilst eagerly awaiting key decisions from central banks, namely today’s announcements from the Fed and the Bank of Canada, and tomorrow’s ECB meeting, at which interest rates are expected to remain unchanged. Microsoft and Alphabet’s results, due to be published after the close of trading on Wall Street, will also be crucial.
Sentiment is being dampened by two factors: rising oil prices and ongoing political and fiscal uncertainty in France. The risk premium on French debt continues to worry the market — the OAT-Bund yield spread reached almost 178 basis points last week. Crude oil continues its upward trend — Brent is up by over 1.28 per cent (around $111), whilst WTI has risen by as much as 1.72 per cent, which is boosting energy companies but dampening risk appetite ahead of interest rate decisions. The dollar is stable (DXY index -0.04 per cent), the euro has barely moved (EUR/USD +0.02 per cent at around 1.1332), the pound is weakening slightly (GBP/USD -0.12 per cent), whilst gold is correcting by 0.35% to around $4,049, ceding ground to energy commodities.
By sector, energy leads the way (+1.08 per cent), buoyed by high oil prices, followed by industry (+0.35 per cent) and a slightly positive technology sector (+0.13 per cent), which remains on edge ahead of this evening’s results from Microsoft and Alphabet across the Atlantic — these are set to set the tone for the entire ‘AI trade’ . The weakest performers are healthcare (-0.96 per cent), materials (-0.72 per cent) and financials (-0.70 per cent), weighed down by mixed reports from banks and a sell-off in Santander.
Company information:
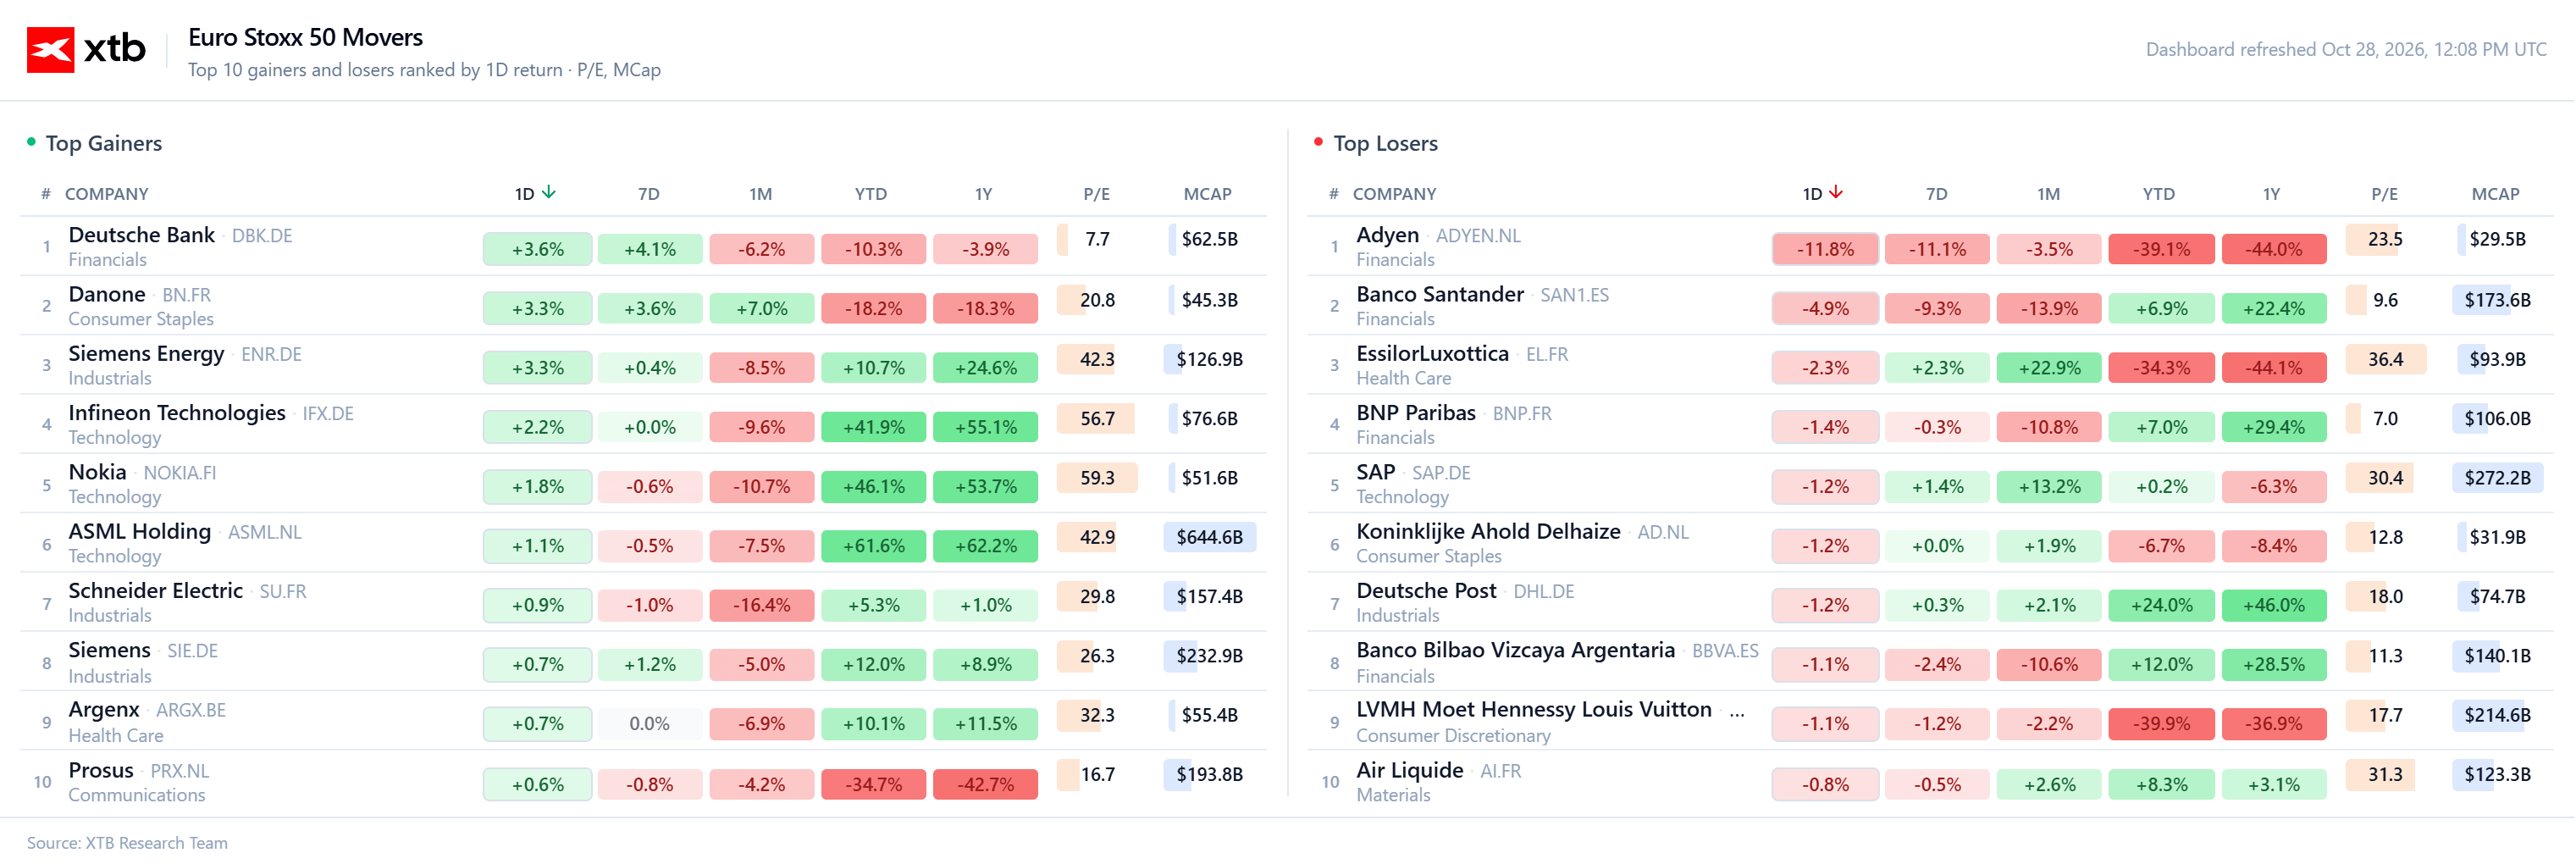
The earnings season in the European banking sector generally turned out better than feared and allayed some of the concerns following Tuesday’s disappointment from HSBC. Deutsche Bank (+3.6 per cent, Euro Stoxx 50 leader) reported a 2 per cent rise in quarterly profit to €1.59 billion despite a fall in investment banking revenue, whilst the strength of its retail and corporate banking divisions enabled it to raise the group’s revenue forecast to over €33 billion. The British bank Standard Chartered (+3.7%) also delivered a strong surprise by raising its revenue targets, whilst BNP Paribas increased its profit by 14% thanks to excellent equity trading results and announced a share buyback worth €1.3 billion (although the share price still fell by 1.4%). A notable exception is Banco Santander (-4.9 per cent), whose 19 per cent rise in core profit was overshadowed by weakness in Brazil — profit in this key market fell by 15 per cent, whilst provisions rose by 23 per cent, which, following President Lula’s surprise re-election, is weighing on the bank as a whole; the sell-off dragged the Spanish IBEX down by around 1.5 per cent. UBS (-1.1%) reported results in line with expectations (US$2.69 billion), but stepped up its share buyback programme, planning to complete the US$3 billion programme by February.
The biggest loser of the day is the Dutch payment processor Adyen (-11.8%), which slashed its 2026 EBITDA margin target to 50 per cent from around 52 per cent and withdrew its medium-term profit target to “maintain flexibility” for investment in recruitment (1,000–1,100 new jobs) — despite beating forecasts for revenue and payment volumes; broker Degroof Petercam described the move as a “nasty surprise”, and this year’s share price loss has already reached around 40 per cent.
On the upside, Valmet (+8.5 per cent) stood out; thanks to a 30 per cent surge in orders, it wiped out its full-year losses and jumped to the top of the STOXX 600, as did Stellantis (+5.7 per cent) following a slight rise in operating profit. In contrast, German company Symrise (-12 per cent, its worst day since 2008), a manufacturer of flavours and fragrances, fared disastrously after warning of a weaker end to the year and pressure on margins, losing €1.4 billion in market capitalisation.