S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Global market sentiment is sharply divided today: European stock exchanges (DAX, STOXX 600) are hitting new record highs, while U.S. index futures are under pressure following fresh reports surrounding Nvidia. Nasdaq 100 futures are down about 0.6%, and S&P 500 futures are losing around 0.3%, driven mainly by Nvidia shares dropping over 5% in pre-market trading. Signals from Asia are mixed (MSCI Asia Pacific -0.8%, Nikkei 225 -0.7%, Hang Seng -1.3%), while the VIX volatility index is up around 2%. Nvidia is at the epicenter of today’s developments. The company’s board is searching for a successor to Jensen Huang, according to Bloomberg, the firm is working with an external search firm to identify CEO candidates. This follows an investigation into Huang’s affair with a woman accused of spying for China, as well as another scandal involving Jensen Huang’s romantic relationships made public by the WSJ. However, the market fears broader repercussions beyond the share price itself, which is down about 6% in pre-market trading.
The matter also carries a geopolitical dimension, testing the U.S.-China trade truce set to expire in January, while Democratic senators are demanding the preservation of documents regarding Nvidia’s chip exports to China. Still, we do not believe this will derail the AI trend in the long term. For now, competitors AMD, Broadcom, and Alphabet, are gaining ground. Two upcoming deals will test market appetite for AI: CoreWeave raising at least $4 billion through an investment loan, and Anthropic’s initial public offering, which is multiple times oversubscribed. Buyers dominate European trading floors, with indices sitting at record highs. Germany’s benchmark DAX index broke above the 27,000-point mark for the first time in history (27,001 points), fueled by optimism around the AI boom and solid corporate earnings, with Siemens lending major strength to the index following record profits.
The current backdrop for the DAX is highly favorable: falling energy prices, convincing quarterly results, and hopes for a sustained economic recovery are building an increasingly solid foundation for a year-end rally. Macro data is also providing support, the council of economic advisers to the German government sharply raised its GDP growth forecast for this year to 1.3%, while UK GDP grew 0.7% quarter-on-quarter in Q3, its fastest pace in two and a half years. The DAX is gaining about 1.1%, and other regional markets are also advancing: France’s CAC 40 is up around 0.5%, the UK’s FTSE 100 is up 0.2-0.3%, and both the Euro Stoxx 50 and the pan-European STOXX 600 are gaining about 0.5%, with the STOXX 600 extending its winning streak to four sessions and setting new records. The biggest risk for the DAX remains the Nvidia situation, as rumors surrounding the search for Huang’s successor weigh on sentiment.
FX Market
- EURUSD: The pair remains steady (+0.03%), while the U.S. dollar index (DXY) edges slightly lower to 102.8 points. Lacking a clear catalyst, the market is awaiting remarks from Federal Reserve officials.
- GBPUSD: Sterling is trading steady too (-0.04%). Strong UK GDP data (+0.7% QoQ) failed to translate into a meaningful rally for the pound, leaving the pair in a narrow consolidation range.
- USDJPY: The exchange rate is hovering just below the psychological 160 level, around 159.68 (+0.01%), with little movement during the session.
Commodities Market
- Crude Oil: Brent crude is pulling back by about 0.3% to $92.3 per barrel, while WTI is down roughly 0.5% to around $86. Oil remains under pressure from easing geopolitical tensions: U.S. envoys Steve Witkoff and Jared Kushner arrived in Russia for talks with Vladimir Putin on ending the war in Ukraine, and the market is also seeing a softer tone regarding the Middle East conflict, curbing the geopolitical risk premium.
- Natural Gas: European natural gas contracts are surging over 3% to around €89.6/MWh, while U.S. natural gas is up about 0.5% to $3.26. The European market is climbing on supply concerns ahead of winter: EU storage levels reportedly stand at roughly 72% compared to a five-year average close to 90%, LNG shipments through the Strait of Hormuz remain constrained, and QatarEnergy has extended force majeure until at least the end of December.
- Gold and Silver: Gold is losing over 1%, dropping below $3,950 per ounce, while silver is down more than 1% to around $51. Precious metals remain under pressure from rising U.S. Treasury yields (with the 2-year yield near 4.75%) and hawkish Fed expectations, while silver is further weighed down by the sell-off in tech stocks.
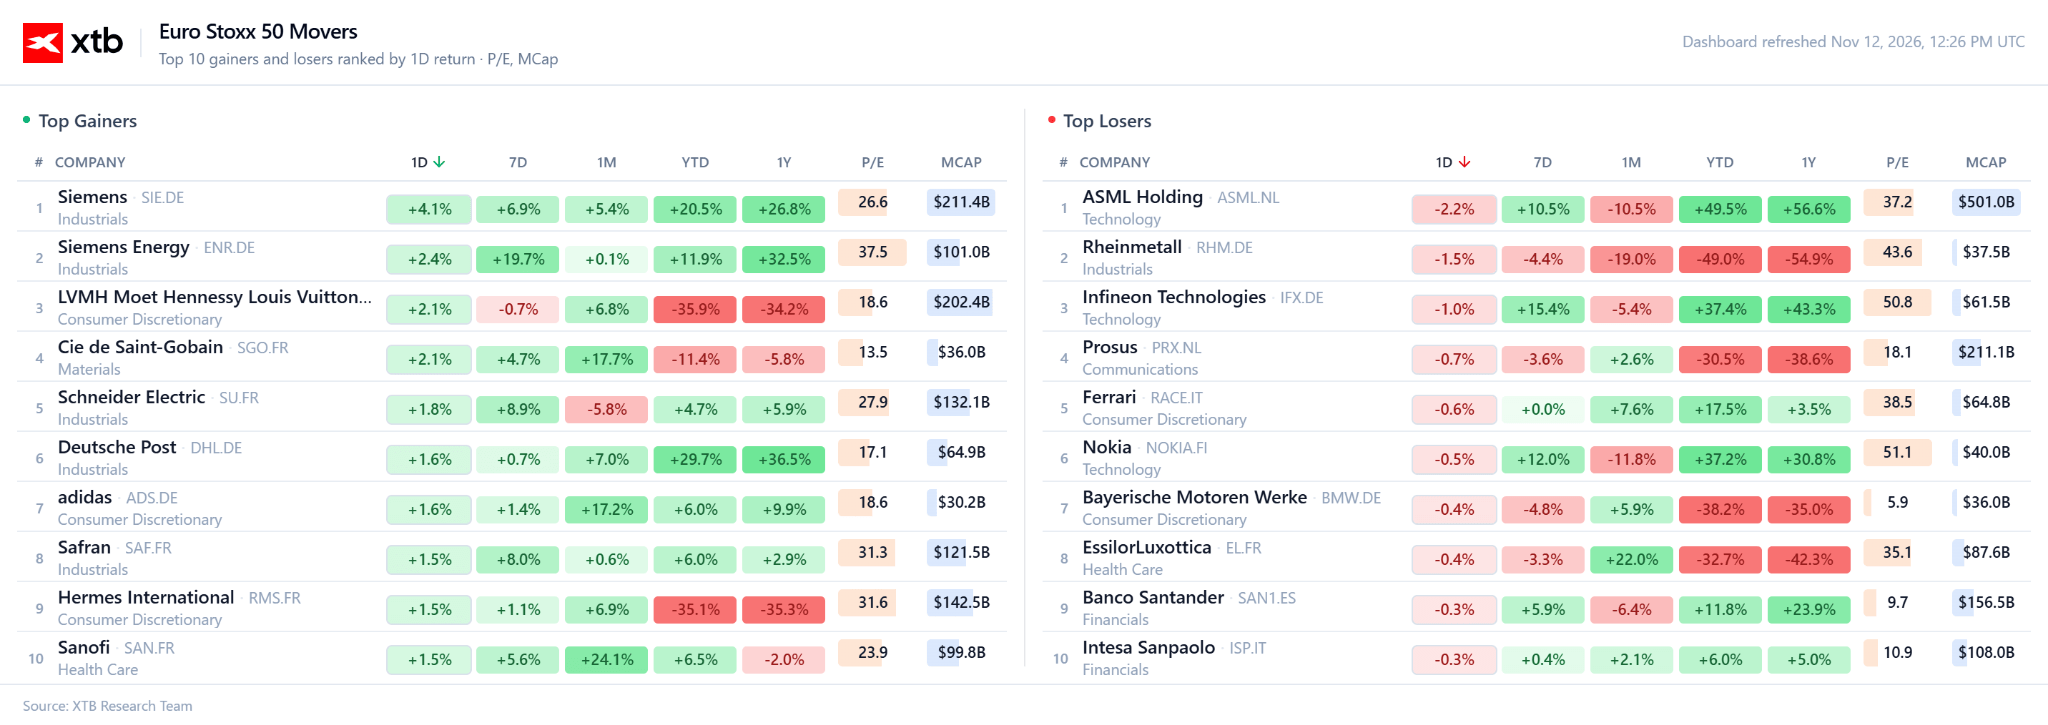
Top Gainers:
- Siemens AG (SIE.DE): The company is leading gains following record full-year results. Q4 industrial profit rose 22% to €3.89 billion, and orders in Smart Infrastructure jumped 40% thanks to contracts with data center operators. Siemens also raised its medium-term sales growth target to 7–11% annually. This serves as a counterpoint to Nvidia’s sell-off, demonstrating that tangible orders for AI infrastructure continue to flow. (+2.8%)
- LVMH (MC.FR): Rebounding from its lowest levels since 2020, as the luxury sector sits at its cheapest valuation in a decade after a string of disappointments. However, the move is largely driven by market rotation, as fundamentals (weaker demand in China and the U.S.) remain unchanged. (Shares up over 2%)
- Hermès (RMS.FR): Following the broader sector higher. The company is recouping part of its losses from October’s earnings release, when the stock fell nearly 5%, benefiting from capital rotation out of tech and into consumer stocks.
Top Losers:
- ASML Holding (ASML.NL): Indirectly reliant on the AI capital expenditure cycle, meaning uncertainty surrounding Nvidia—the central link in that ecosystem—is hitting the entire chip supply chain. (Shares down 2%)
- Nokia Oyj (NOKIA.FI): Nvidia holds roughly a 2.9% stake in the company and collaborates with it on AI-RAN, so Nvidia’s troubles are weighing on the narrative around Nokia. Pressure is compounded by concerns over cash flows and restructuring costs, which dragged the stock down nearly 10% following Q3 results. (Shares down ~1.5%)
- Infineon Technologies AG (IFX.DE): The chipmaker is falling alongside the broader semiconductor sector. It supplies power components for AI servers, leading the market to price in the risk of a slowdown in Nvidia’s supply chain. The contrast with Siemens shows that investors are penalizing stocks tied to AI sentiment today while rewarding those backed by hard orders.
On today’s calendar: U.S. weekly initial jobless claims data at 14:30.