S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

European equities are seeing a moderate rebound for a second session in a row. Today’s trading brings gains in the main indices across the Old Continent, hovering around 0.5%. Switzerland is leading, with SUI20 futures up more than 1%. At the back of the pack are the FTSE and the WIG20, with gains limited to around 0.3%. European investors are temporarily shifting some attention away from the Persian Gulf to focus more on company news and the accelerating quarterly earnings season. This week, LVMH and ASML are in the spotlight. ECB interest rates, both current and implied, are and will remain crucial for European assets. Today’s comments by Pierre Wunsch on Bloomberg TV confirm that the ECB will probably have to raise rates again. Partly in response to this message, moderate gains can be seen in European government bond prices. Italy is an exception in today’s European debt market. ECB officials are expressing concern about Italy’s budget plans and its deficit for 2027 to 2028. Minister Giancarlo Giorgetti points out that the current trajectory could make it harder for Italy to exit the excessive deficit procedure. A series of IRGC strikes on ships in the Strait of Hormuz has been confirmed. According to Bloomberg, the total number of ships hit over the last three days is as many as six. Analysts point to increased training and offensive activity by Iran’s missile forces, which may signal an escalation episode by one side or the other.
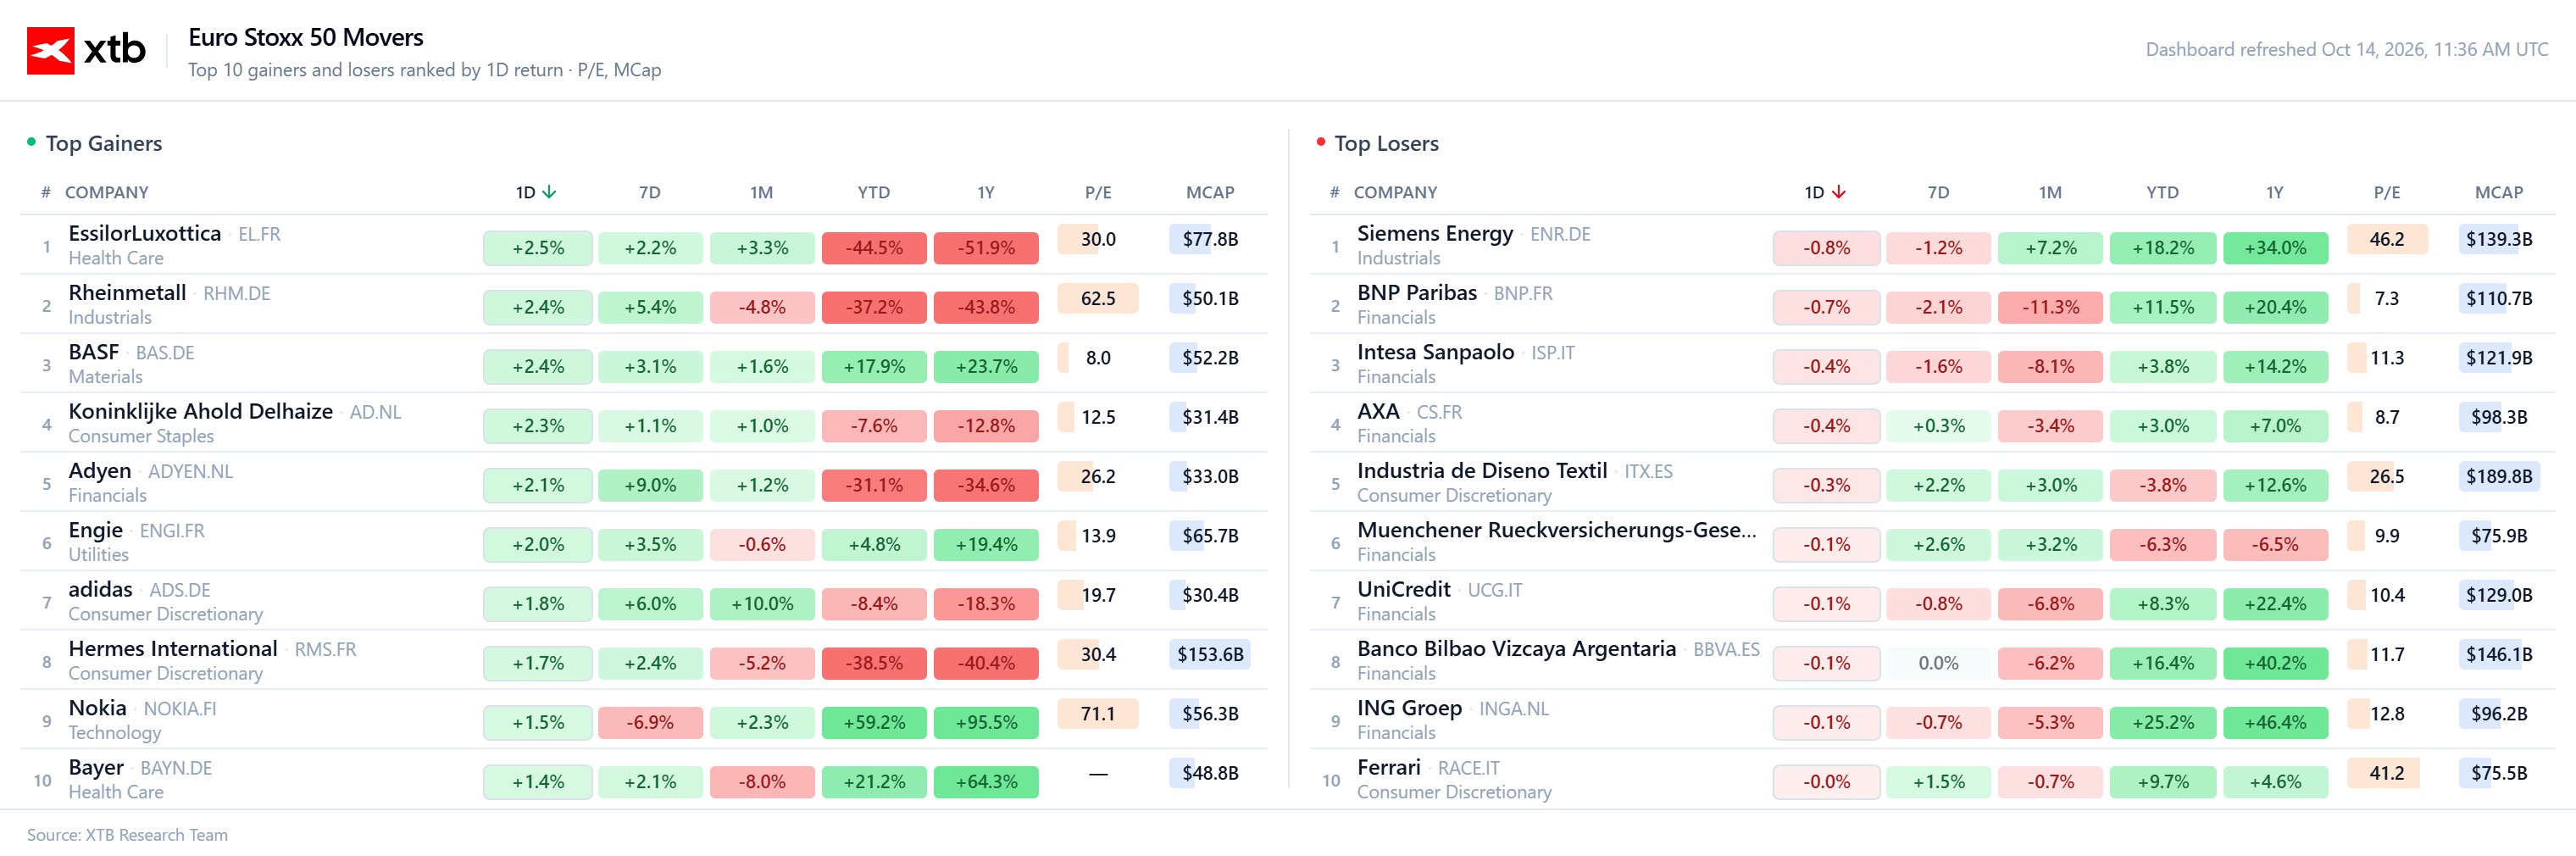
Within the Euro Stoxx 50, fashion, defense, and parts of the semiconductor sector are performing best. The gains in fashion and semiconductors are mainly an after effect of results from LVMH and ASML, while the defense sector has been rebounding in recent days amid analysts’ comments, including from Bloomberg and Morgan Stanley.
Company news
- ASML (ASML.NL): Shares are up 3.6% after the semiconductor equipment maker presented a strong demand outlook, saying customers are expressing interest in placing orders for 2029 and 2030.
- Aker BP (AKERBP.NO): The Norwegian oil company is up around 2.5% after publishing its average production for the third quarter.
- Technip Energies (TE.FR): UBS released a positive note on the company, arguing that a record order backlog and margin improvement will likely turn sentiment around.
- Big Yellow (BYG.UK): Shares are up around 6% after investor Ancora reported holding more than a 4% stake and published a presentation calling on management to conduct a strategic review.
- Ashmore (ASHM.UK): Shares are up around 3% after the emerging markets fund manager’s first quarter update showed assets under management slightly above estimates and gross redemptions at the lowest level in more than 15 years.
- SEB (SEBA.SE): The bank’s shares fell more than 5% after the lender said it expects a Swedish regulator’s ruling that its internal ratings based credit risk models are insufficient to temporarily reduce capital buffers by about 120 bps.
- Orsted (ORSTED.DK): The renewables company fell 4% after the US Department of Justice asked a federal court to postpone a case concerning approval of the plan to build and operate the Danish Revolution Wind project.
Forex
- The main source of volatility among European currency pairs today is the Swiss franc. A slight decline in risk aversion combined with Swiss National Bank rate divergence is pushing the currency down by about 0.2%.
- The British pound is also strengthening moderately, in reaction to a speech and comments from the BoE governor.
Commodities
- Despite ongoing tension in the Middle East, the energy market is giving back part of its gains. Brent crude remains stalled around $106, while NATGAS is down about 2%.
DE40 analysis (D1)
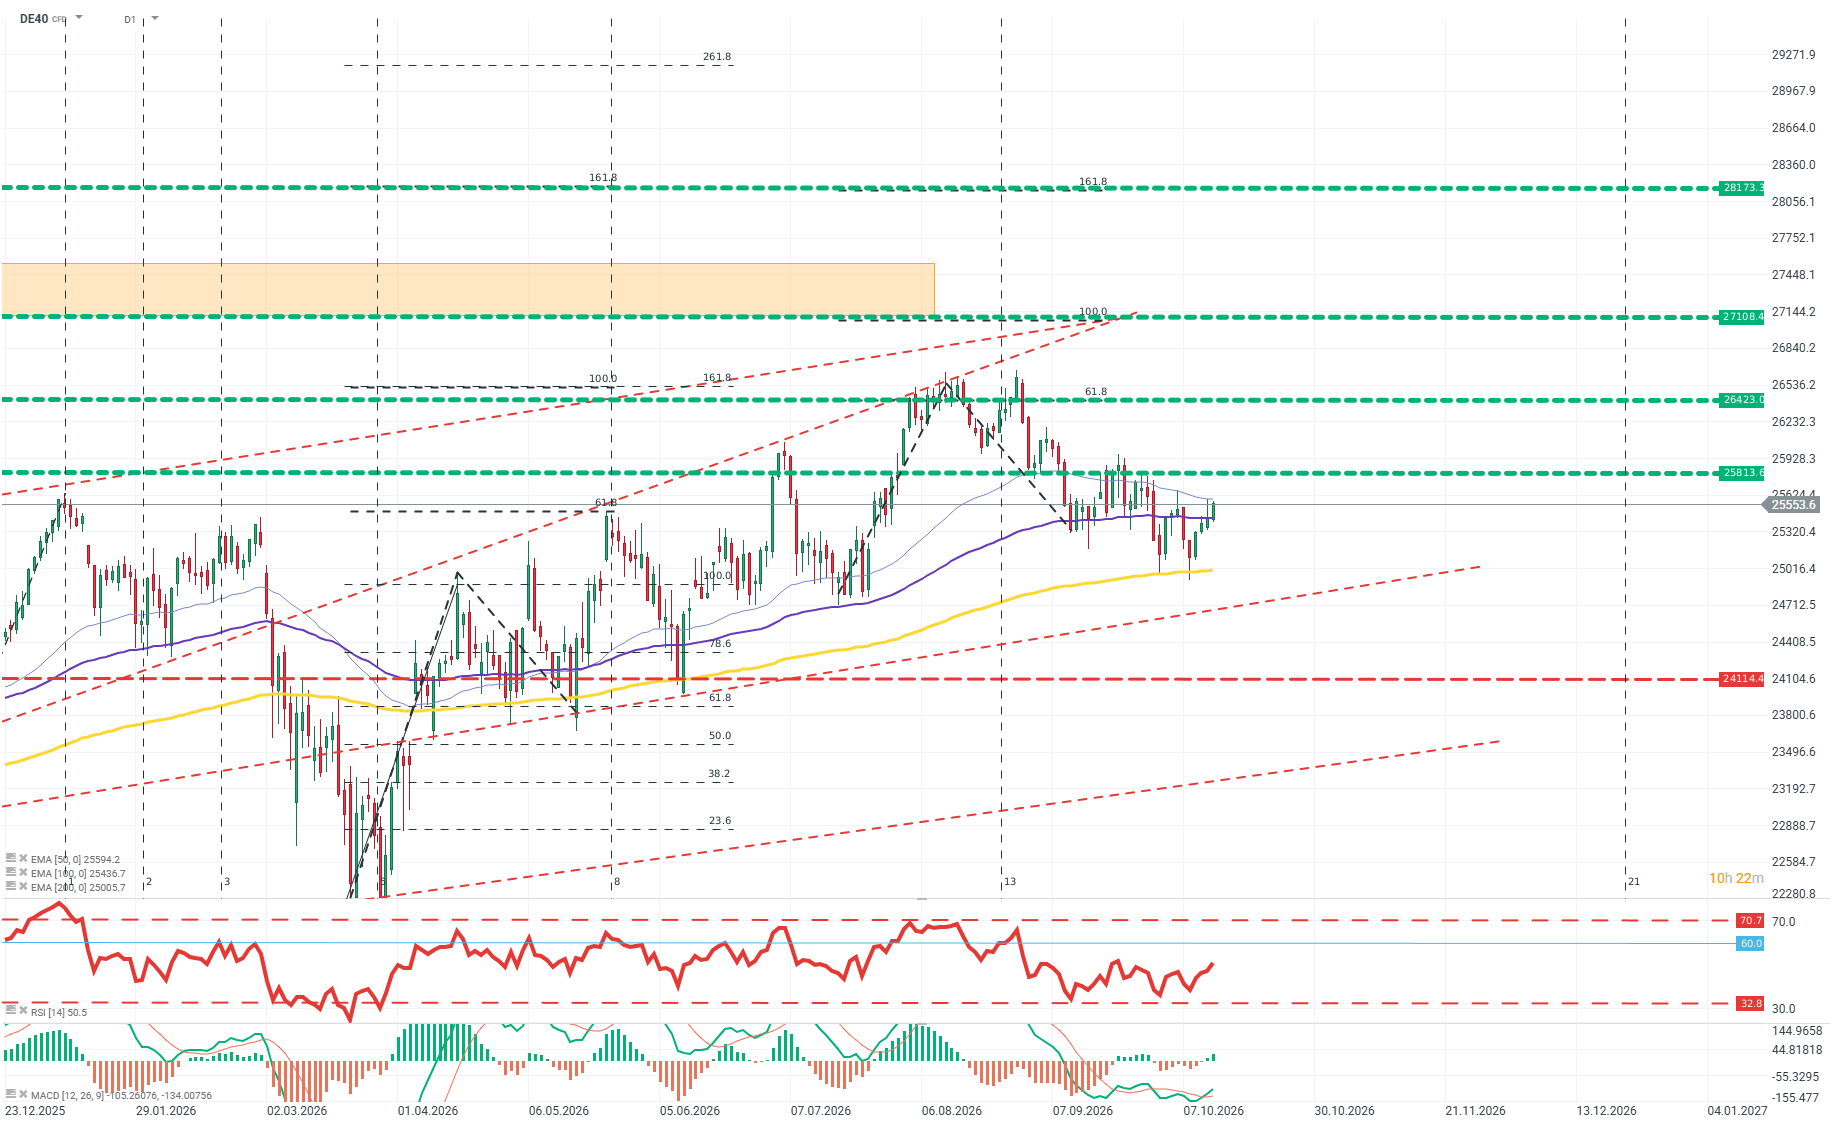
The price defended the EMA200 level twice, located at the lower boundary of an expanding upward channel. Normalized RSI (14) offers an opportunity to attempt a breakout toward the FIBO 61.8 and 100 levels. A key hurdle on the way is nearby resistance around 25,800. If there is a downside break, the target range for the correction could be around 24,100. Source: xStation5
Crypto
- Crypto market sentiment remains moderately negative. Most currencies are posting losses, though with limited momentum.
- Ethereum is down about 0.5%, Solana is down 0.4%, and Bitcoin is down about 0.2%.