S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Key takeaways
- Why rising global bond yields could crush the gold price
- G7 implied yields have reached their highest levels for more than 2 decades
- Why a 10-year US Treasury yield is bad news for gold
- Gold loses its shine as next move for Fed is likely to be a hike
The bear case for gold, why bond yields are a problem The recent spike in global bond yields has left investors pondering whether the gold price may have passed its peak. Fundamentals are also starting to turn against gold bulls. The market reaction to the US producer price report for April, which saw producer prices rise 1.4% last month, the largest monthly gain since 2022, has been moderate so far. The annualized producer price index rose to 6%, driven, unsurprisingly, by a sharp rise in energy prices.
However, gains were broad based, with a 2.7% gain for trade services. This suggests that higher energy costs and tariffs are having a large impact on prices as we move through Q2. Yields on the 10-year Treasury yield may have only rose 3bps, but today’s move is significant since the 10-year yield is now back above 4%, the highest level of the year so far. We are living in a high inflation environment, and the US economy is also showing signs of strength, for example, a robust labour market. This is likely to give the Fed pause for thought, even if the incoming Fed chair, Kevin Warsh, who will take up his new position later this week, is a Trump faithful and reportedly has dovish leanings.
This week’s US inflation data, including a hotter than expected 3.8% reading for April CPI, will make it almost impossible for the Fed to cut rates in the foreseeable future. In May, the US CPI rate is expected to rise to 4%, double the Fed’s target rate. The Fed Fund Futures market is pricing in a 30% chance of a 25bp rate hike by the end of this year, with an 80% chance of a hike in rates in 12 months’ time. The US is not the only country now facing rate hikes, there are also hikes expected from the ECB and the BOE, and the implied yield on long term borrowing costs for the entire G7 is at elevated levels for the long term, as you can see below.
Chart 1: G7 bond yield curves, implied rates are at elevated levels compared to recent history
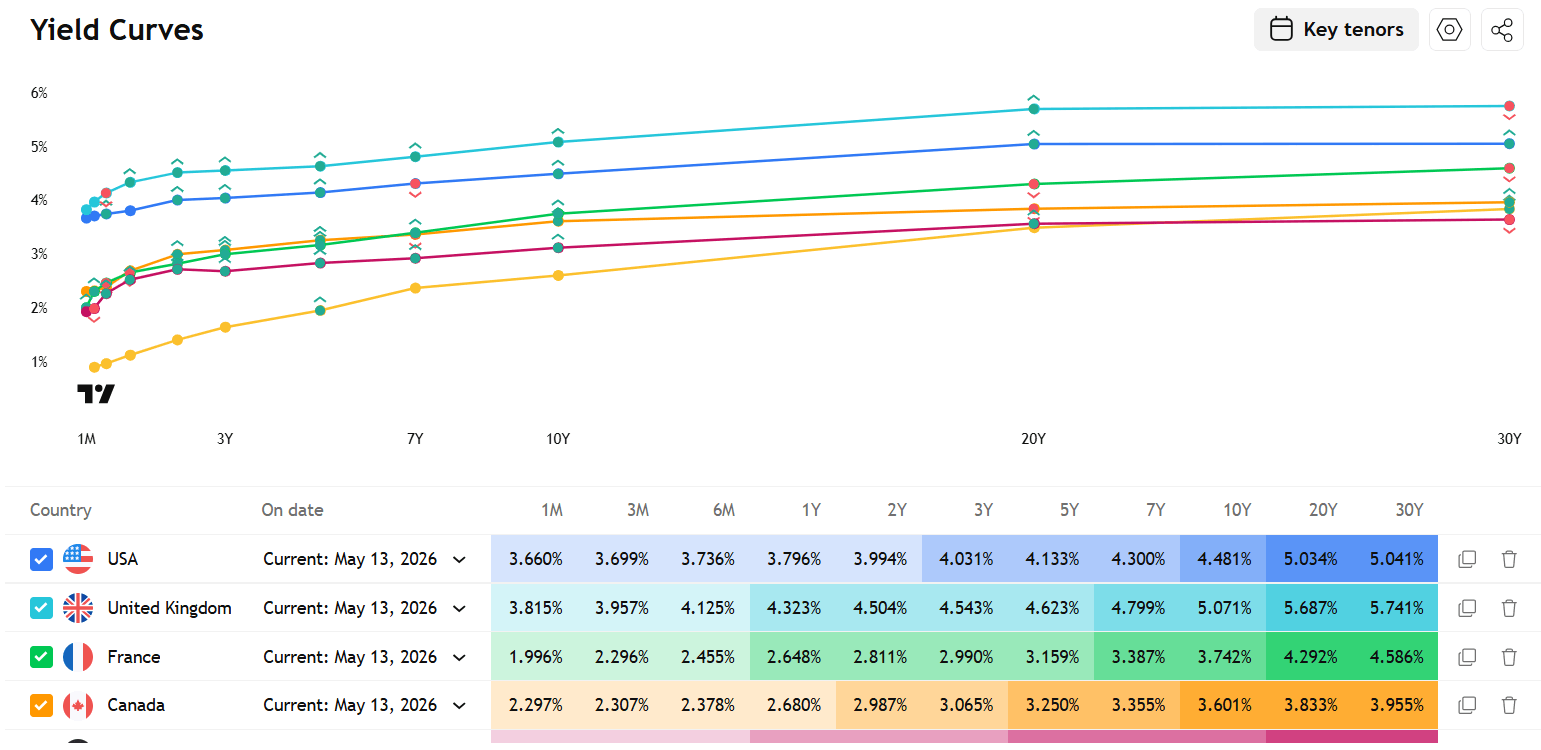
Source: XTB and Trading View
This bond market problem is likely to become a big problem for the gold bulls. The issue with gold is that it does not yield anything. It produces no income, no interest and no dividend, so when you hold gold, you give up gains that you could earn elsewhere. Gold can outperform when yields are rising, but only if real yields (when adjusted for inflation) are negative. Right now, yields are higher than inflation rates, including in the US and the UK, which could weigh on gold’s attractiveness. Gold also suffers from a strong dollar.
The US dollar has been one of the strongest global currencies so far this year, and when it rallies it can weigh on the price of gold. This is because the yellow metal is priced in USD, so you need fewer dollars to buy it. A strong dollar can also dampen foreign demand for gold. The gold price is more than $500 from its early March peak. It has backed away from March’s record high above $5,200 per ounce and has not acted like a safe haven during the war in the Middle East. The rise in bond yields that was triggered by the energy price spike has made gold unattractive in the current environment. With the US -10-year Treasury yield potentially staying above 4% for the long term, the gold price is at risk, with a break below recent lows at $4,575 an ounce a clear bearish signal that could open the gates to further losses in the coming months.
Chart 2: The Gold price
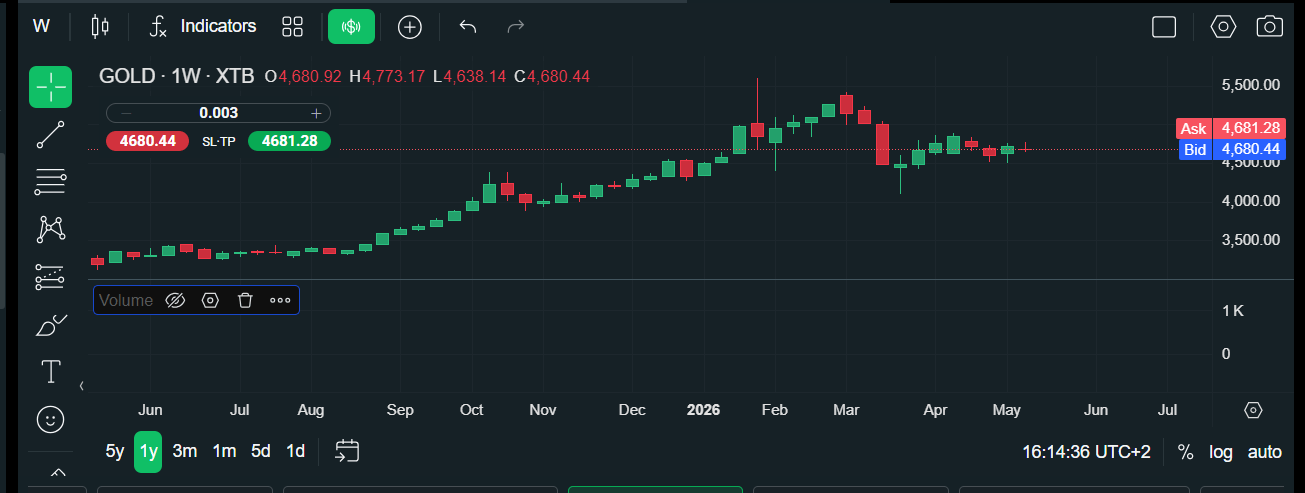
Source: XTB
Overall, there are growing signs that a prolonged energy price spike, inflation risks and political issues could keep global bond yields higher for longer. Rising yields mean that assets like bonds start to pay more, so gold, which pays nothing to its owners, starts to lose its shine.