S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

WTI Crude Oil Falls as Hormuz Talks Ease Supply Risk, but Tight Inventories Support Prices

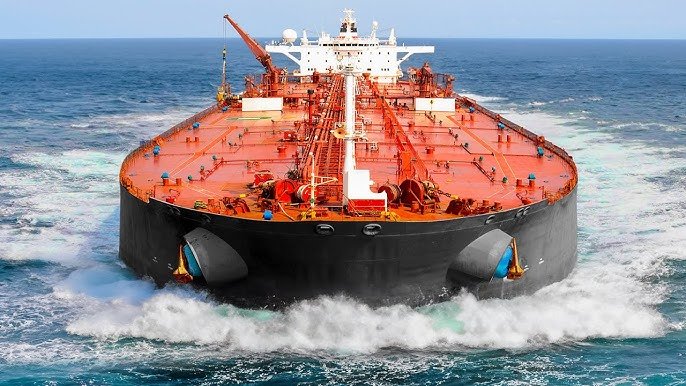
Today Markets Analysis: WTI crude oil fell sharply before recovering part of its losses as reports of diplomatic efforts surrounding the Strait of Hormuz reduced some of the immediate supply-risk premium in oil markets. However, severely depleted global inventories, disrupted Gulf production and elevated freight costs continue to provide an important floor beneath prices.
WTI Pulls Back on Hormuz Arrangement Talks
West Texas Intermediate (WTI) traded near $97.00, down around 3.4%, putting the benchmark on course for its first lower session in five.
The decline followed reports that Gulf foreign ministers are due to meet their Iranian counterpart in Salalah, Oman, in an effort to secure support for a temporary arrangement covering shipping through the Strait of Hormuz.
The possibility of a workable shipping arrangement has encouraged traders to reduce part of the geopolitical risk premium built into crude prices.
However, the physical oil market has not yet returned to normal.
Hormuz Transit Remains Severely Disrupted
Vessel tracking showed only seven ships passing through the Strait of Hormuz on September 10, compared with 11 the previous day.
Before the war began on February 28, the waterway handled roughly 125 cargo vessels a day and around one-fifth of global seaborne crude oil and LNG shipments.
Gulf producers have attempted to maintain exports by moving cargoes to waiting tankers rather than sending fully loaded vessels through the strait. This has allowed exports to remain stronger than transit figures alone would suggest, but at a substantially higher logistical cost.
Tanker earnings have surged as a result, meaning Friday’s decline in crude prices reflects changing expectations around future freight and supply risks rather than a full restoration of normal shipping conditions.
Saudi Arabia’s August production also fell by around 1.9 million barrels per day, while recent Houthi attacks have added further pressure to regional energy infrastructure.
Energy Prices Continue to Feed Into Inflation
The latest US inflation data underline the importance of energy prices for monetary policy.
US CPI increased 0.4% month-on-month in August, while annual inflation remained at 3.4%, broadly matching expectations.
Gasoline prices rose 3.9% during the month and accounted for more than one-third of the overall monthly CPI increase. Fuel costs were around 28% higher year-on-year, while diesel prices were up approximately 52%.
Core CPI also increased 0.3% month-on-month, above the 0.2% consensus estimate, although annual core inflation eased to 2.4%.
The combination leaves energy prices as an important consideration for the Federal Reserve ahead of its September policy decision.
Global Oil Inventories Provide a Significant Floor
The International Energy Agency’s latest monthly report highlighted the scale of the physical supply disruption.
The IEA cut its 2026 demand forecast by a further 940,000 barrels per day, taking the expected full-year decline to 2.5 million barrels per day.
At the same time, global supply is projected to fall by 5.7 million barrels per day during 2026 to around 100.7 million barrels per day.
More than 10 million barrels per day of Gulf production remained shut in through August, while August global production was estimated at 100.1 million barrels per day, down 1.6 million from July.
Despite weaker demand expectations, inventories have absorbed much of the supply shortfall.
Observed global inventories have fallen by approximately 507 million barrels since the war began, equivalent to an average draw of around 2.8 million barrels per day. August alone accounted for roughly 95 million barrels of inventory declines.
That depletion could become increasingly important if supply disruptions persist.
WTI Technical Outlook
WTI’s recent advance remains technically constructive despite Friday’s sharp pullback.
Resistance is seen around $100.50, followed by the psychological $101.00 level. Above that, the next major zone sits just above $103.00, followed by the late-April peak below $107.50.
On the downside, the $95.50 area is the immediate support zone. A break would expose Thursday’s low near $93.00, followed by the $90.00 level.
The technical bias remains higher while $95.50 holds, with $100.50 the first upside objective.
Key WTI Levels
| Level | Significance |
|---|---|
| $107.50 | Major upside resistance |
| $103.00 | Key resistance zone |
| $101.00 | Psychological resistance |
| $100.50 | Initial resistance / upside objective |
| $97.00 | Approximate current price |
| $95.50 | Initial support |
| $93.00 | Key technical support / invalidation |
| $90.00 | Major psychological support |
A daily close below $93.00 would weaken the current bullish technical structure and suggest that the September advance is losing momentum.
Today Markets View
Crude oil markets are being pulled between two opposing forces. The prospect of a temporary Hormuz shipping arrangement is reducing the immediate geopolitical premium, while the physical market remains unusually tight and global inventories have been heavily depleted.
The key question is whether Monday’s diplomatic discussions produce an arrangement that insurers, tanker operators and producers are actually willing to use. If they do, some of the recent supply-risk premium could unwind quickly. If negotiations fail, the market may refocus on disrupted production, depleted inventories and the cost of keeping Gulf exports moving.
“The oil market is pricing the possibility of a solution to the Hormuz disruption, but the physical balance has not yet normalised. With global inventories already significantly depleted, a failure to establish a workable shipping corridor could quickly return supply risk to the forefront. Technically, $95.50 remains the key near-term level for maintaining the bullish structure.”
— Louis Roche, Analyst, Today Markets
For broader energy-market coverage, follow Today Markets. For specialist currency and macro-market intelligence, Currency Hedger provides additional analysis of the forces influencing global markets.
Analysis by Louis Roche, Analyst, Today Markets
Currency Hedger Contributor: Currency Hedger Market Intelligence