S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

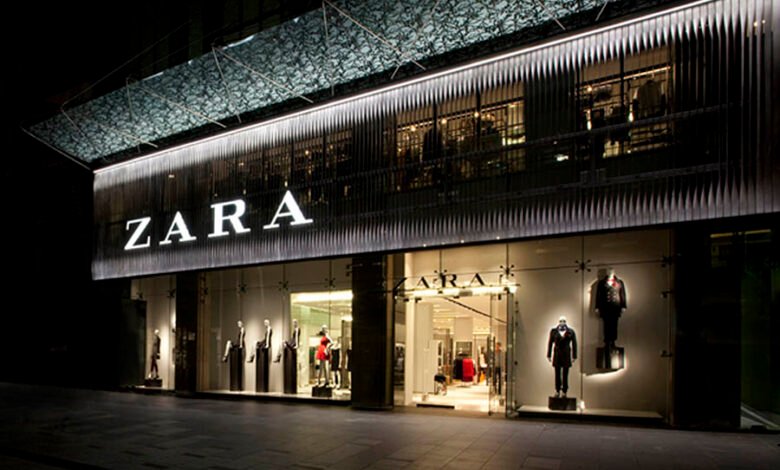
Shares in Inditex (ITX.ES), the owner of the Zara chain, are down by as much as 4.9 per cent today – their sharpest fall in six months – after the Spanish clothing giant published its first-half results, which showed strong sales but fell short of expectations in terms of operating profit.
Company results at a glance
- Sales in H1 2026 rose by 7.6 per cent year-on-year (9.2 per cent in constant currencies) to €19.8 billion, exceeding the consensus estimate (€19.71 billion)
- EBIT stood at €3.84 billion (+7.6 per cent year-on-year), below expectations of €3.92 billion – it is this shortfall that is dragging the share price down
- The EBIT margin fell to 19.5 per cent from the expected 19.9 per cent
- Net profit rose by 6.8 per cent to just under 3 billion euros, slightly below the consensus estimate (3.06 billion euros)
- The gross margin held up well at 58.7 per cent, in line with expectations
- EBITDA rose by 7.8% to €5.51 billion, which was also slightly below forecasts (€5.57 billion)
- Sales between 1 August and 7 September rose by 9 per cent in constant currencies – the trend remains strong as we enter the second half of the year
- The company has announced an additional approximately €200 million in extraordinary capital expenditure (for its new headquarters in Barcelona), on top of its standard capital expenditure of around €2.3 billion
The management board attributed the pressure on margins to higher costs of transport, online order fulfilment and distribution, partly resulting from disruptions in the Middle East. Added to this is rising depreciation linked to the now-completed logistics investment worth €1.8 billion – these costs are now fully recognised in the profit and loss account, weighing on operating profit faster than revenue is growing. The market was also taken by surprise by the decision to make an additional, extraordinary capital expenditure of around 200 million euros, earmarked – as CEO Óscar García Maceiras explained during a teleconference – for the company’s new headquarters in Barcelona. This exceeds the standard investment budget for this year, estimated at around €2.3 billion, and for some analysts it is a sign that pressure on margins may persist for longer than previously anticipated. It is worth bearing in mind that the newly announced capex may result in further depreciation write-offs in the future.
Pricing compared to the competition
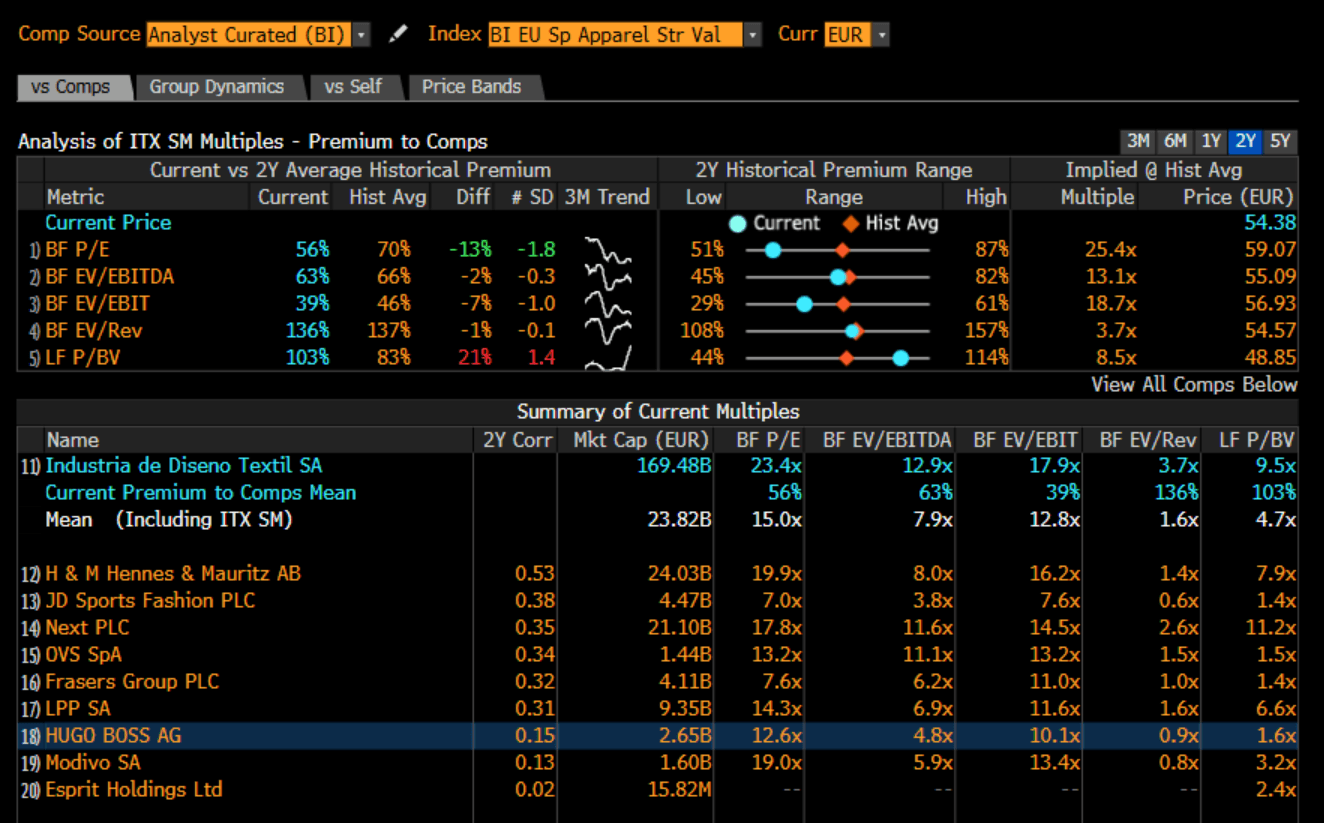
Inditex is still trading at a significant premium to its peer group – currently 56 per cent on a forward P/E basis – but this is still well below the two-year historical average of 70 per cent. In other words, the market has already partially corrected its optimism regarding the company, pushing the premium down to the lower end of the historical range (51–87 per cent). A similar picture can be seen for EV/EBITDA (a 63 per cent premium compared with an average of 66 per cent) and EV/EBIT (39 per cent compared with 46 per cent) – the premium is narrowing across the board relative to historical norms, although it remains clearly positive.
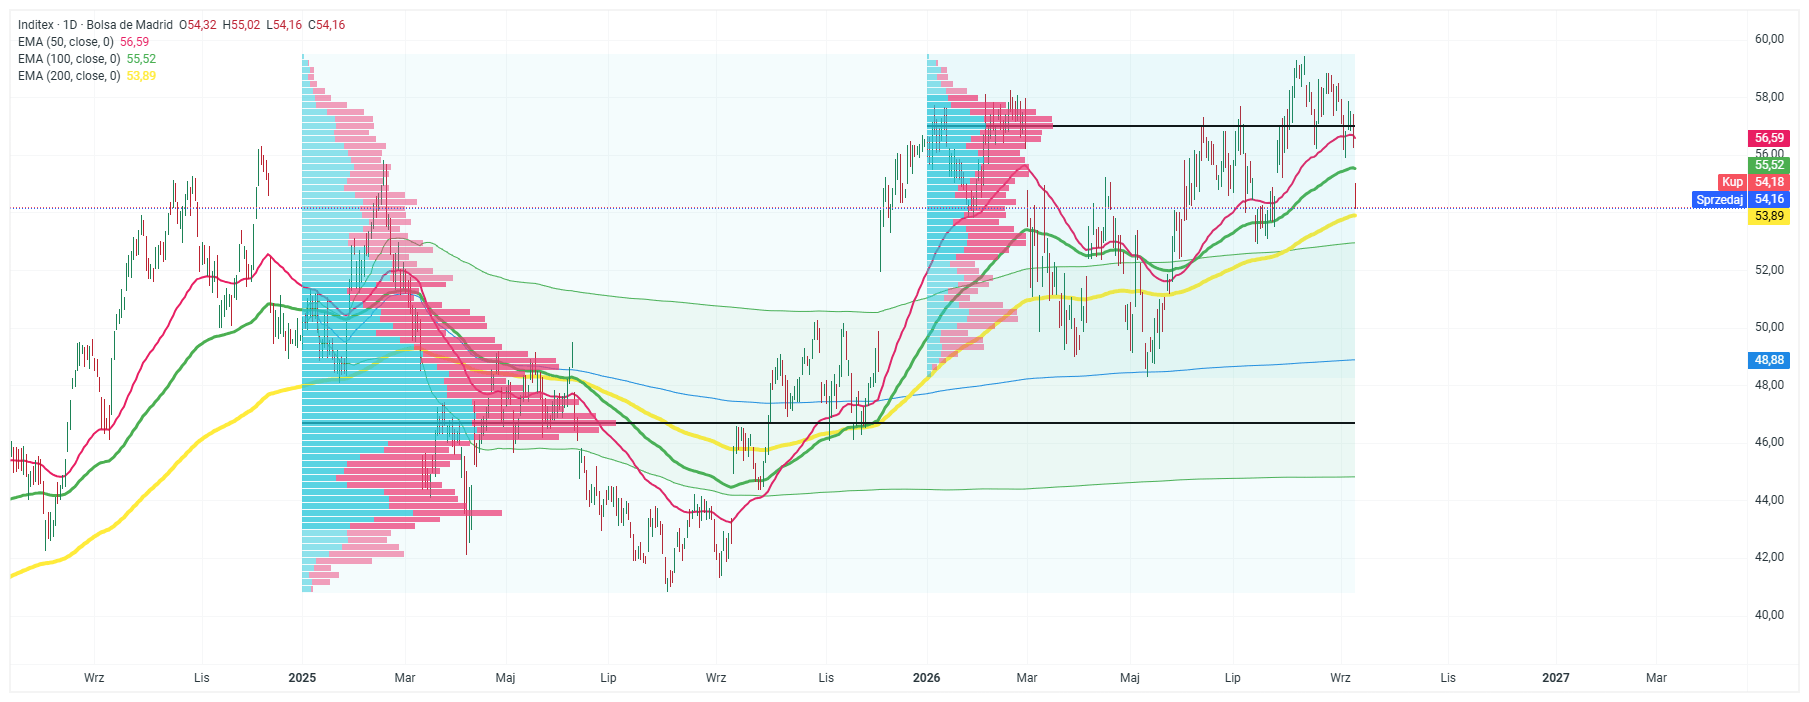
In terms of chart behaviour following today’s slump, the ITX share price is approaching the 200-day EMA, which may serve as a technical support level. Since the start of 2026, the price has not often dipped below this level, which may reinforce the 200-day EMA as a key control point. On the other hand, in terms of valuation, the company is not excessively oversold either; therefore, the future performance of the shares will largely depend on investor sentiment towards companies in this sector (retail/apparel). Source: xStation