S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Key takeaways
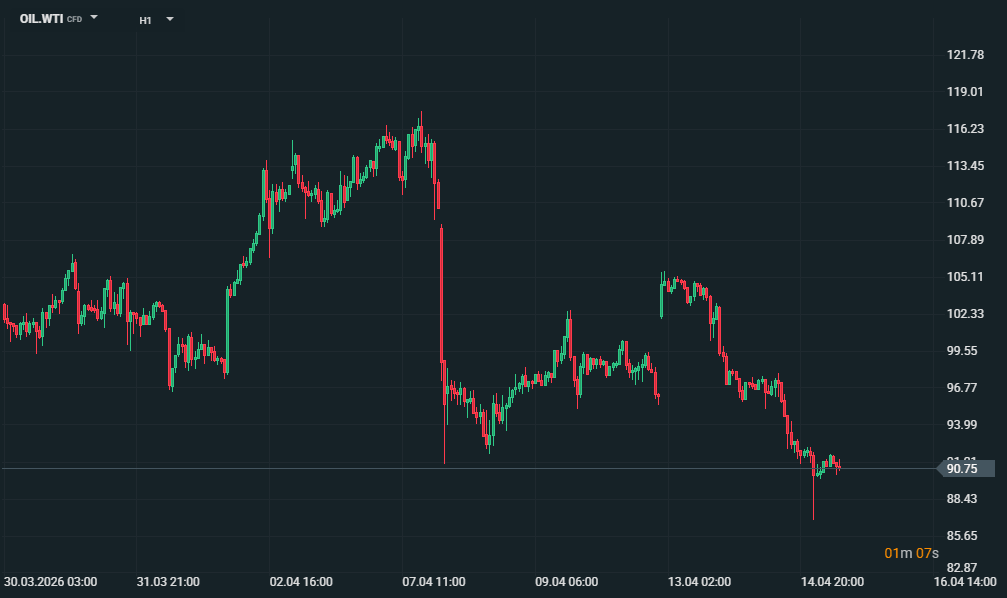
- Oil declines: Brent 94.30 USD, WTI 90.80 USD – fading risk premium
- Markets are pricing progress ahead of the next round of US–Iran talks (Thursday)
- Trump signals a quick resolution; no need to extend the truce
- Vance points to a “grand bargain” and negotiation progress
- Over 100 tankers heading to the US indicate supply reorganization
- The Strait of Hormuz remains a key risk for global energy flows
The oil market is pricing in an increasing probability of a truce between the US and Iran. The geopolitical risk premium is gradually fading. Brent has fallen to 94.30 USD, and WTI to 90.80 USD, approaching the lowest levels in several weeks. This move reflects growing market conviction that a diplomatic solution is possible. Markets have clearly shifted into an “agreement optimism” mode ahead of another round of US–Iran talks scheduled for later this week. President Trump is reinforcing this narrative, stating that the conflict is “very close to over” and suggesting that extending the ceasefire may not be necessary. Vice President Vance highlighted “significant progress” and outlined a potential “grand bargain,” involving Iran’s economic reintegration in exchange for nuclear concessions. This marks a clear contrast to the breakdown in talks over the previous weekend. Market behavior over the past two days confirms this optimism. Equities have rebounded strongly, with US indices once again approaching all-time highs, while demand for safe-haven assets has weakened. At the same time, the energy market is reacting most directly — oil prices have declined significantly from recent highs, with WTI down more than 22% from its peak. Despite this, the situation remains fragile: flows through the Strait of Hormuz are still significantly constrained, and any disruption or breakdown in negotiations could quickly reverse the current trend. The fact that more than 100 empty tankers are heading toward the US suggests a reorganization of supply rather than a full normalization of the market. Despite improving sentiment, markets remain caught between optimism and structural uncertainty. A potential agreement could gradually reduce the geopolitical risk premium, but key issues — particularly regarding nuclear commitments and long-term regional influence — remain unresolved. For now, oil remains the most sensitive barometer of sentiment: it declines on positive headlines but remains vulnerable to sharp rebounds in case of negative developments.
The material on this page does not constitute financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other specific needs. All information provided, including opinions, market research, mathematical results and technical analyzes published on the Website or transmitted To you by other means, it is provided for information purposes only and should in no way be construed as an offer or solicitation for a transaction in any financial instrument, nor should the information provided be construed as advice of a legal or financial nature on which any investment decisions you make should be based exclusively To your level of understanding, investment objectives, financial situation, or other specific needs, any decision to act on the information published on the Website or sent to you by other means is entirely at your own risk if you In doubt or unsure about your understanding of a particular product, instrument, service or transaction, you should seek professional or legal advice before trading. Investing in CFDs carries a high level of risk, as they are leveraged products and have small movements Often the market can result in much larger movements in the value of your investment, and this can work against you or in your favor. Please ensure you fully understand the risks involved, taking into account investments objectives and level of experience, before trading and, if necessary, seek independent advice.