S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

ServiceNow plunges 13% after earnings, Software sell-off kick-off again?

The sharp sell-off in ServiceNow shares following its Q1 2026 results may seem exaggerated at first glance. The company did not disappoint in the traditional sense: revenue came in at $3.77 billion versus $3.75 billion expected, while adjusted earnings per share reached $0.97, exactly in line with consensus. Despite this, the stock dropped significantly, as the market was expecting more than just “solid” results. In ServiceNow’s case, investors were looking for clear acceleration, stronger AI monetization, and confirmation that the company remains one of the most dynamic assets in the entire software sector.
The broader software space is also under pressure in premarket trading. Snowflake is down around 3%, Salesforce over 4%, HubSpot 4.5%, Workday 5%, and Atlassian roughly 6%. IBM is also falling more than 7% after reporting weaker software revenue data. The biggest disappointment: subscription growth The key issue in the report was subscription revenue, the core of ServiceNow’s business model. It reached $3.67 billion, representing a slight beat and 22% year-over-year growth. However, investors were expecting something materially stronger. Management explained that approximately 75 basis points of growth were lost due to delays in closing several large on-premise deals in the Middle East, linked to ongoing regional conflict. Fundamentally, this looks like a timing issue rather than a sign of weakening demand. However, in the current market environment, investors are reacting more to momentum than to nuance.
Raised guidance failed to reassure the market
Under normal circumstances, raising full-year guidance would support the stock. ServiceNow increased its full-year subscription revenue outlook to $15.74–$15.78 billion, up from $15.53–$15.57 billion previously. CFO Gina Mastantuono emphasized that the updated guidance already includes conservative assumptions around delayed deal timing in the Middle East. This is an important signal, suggesting management does not see structural weakness in demand. However, investors interpreted the move more as an attempt to stabilize sentiment than as a strong catalyst for a turnaround.
AI narrative still ahead of monetization
From a sector perspective, the key question around ServiceNow is no longer whether it is growing, but whether it is growing fast enough to justify its positioning as a major AI beneficiary. The company has been framing itself as an “AI control tower” for enterprise clients. The issue is that the market now demands not just a compelling narrative, but tangible financial impact. Management indicated that its AI product line is on track to exceed $1 billion in revenue in 2026, with CEO Bill McDermott suggesting that $1.5 billion could be a more realistic figure. While promising, forward-looking potential is no longer sufficient if quarterly results do not demonstrate a clear inflection point.
Fundamentals remain strong
This is where the disconnect between market reaction and operational reality becomes most visible. ServiceNow does not appear to be a business facing structural deterioration. On the contrary, the company continues to deliver strong growth, raise guidance, execute aggressive share buybacks, and close strategic acquisitions. The company repurchased roughly 20 million shares during the quarter—more than double the total for all of 2025. It also completed the $7.75 billion acquisition of cybersecurity firm Armis ahead of schedule. These are not signs of a company under pressure, but rather of one with strong financial capacity and confidence in its long-term trajectory.
Why the reaction was so severe
The explanation lies in how ServiceNow is being valued. The company is no longer treated as a typical growth stock, but as one of the flagship AI stories in enterprise software. That raises the bar significantly. With the stock already down sharply year-to-date, the market was not looking for a “good enough” quarter, but for results that would clearly shift the narrative. Instead, investors got a marginal beat, explanations around delayed deals, and guidance to wait for a broader strategic update at the upcoming Analyst Day. That proved insufficient, triggering a sharp sell-off that spilled over into other software names such as Salesforce, Oracle, and Adobe.
A crisis of patience, not a crisis of business
This reaction can be seen primarily as a reset of expectations rather than a signal of deteriorating fundamentals. The market is punishing ServiceNow not for weak results, but for failing to deliver a sufficiently strong proof of AI-driven acceleration—something investors have increasingly come to expect from infrastructure and enterprise software leaders. This distinction matters. In the short term, sentiment may remain fragile. In the longer term, the key question will be whether delayed deals return to the pipeline and whether AI meaningfully accelerates growth. At present, this looks more like a company that disappointed on pace rather than one losing control of its business. The valuation, based on forward 12-month earnings, currently stands at around 23x and may decline toward 21x after the market open, suggesting a meaningful cooling in investor expectations.
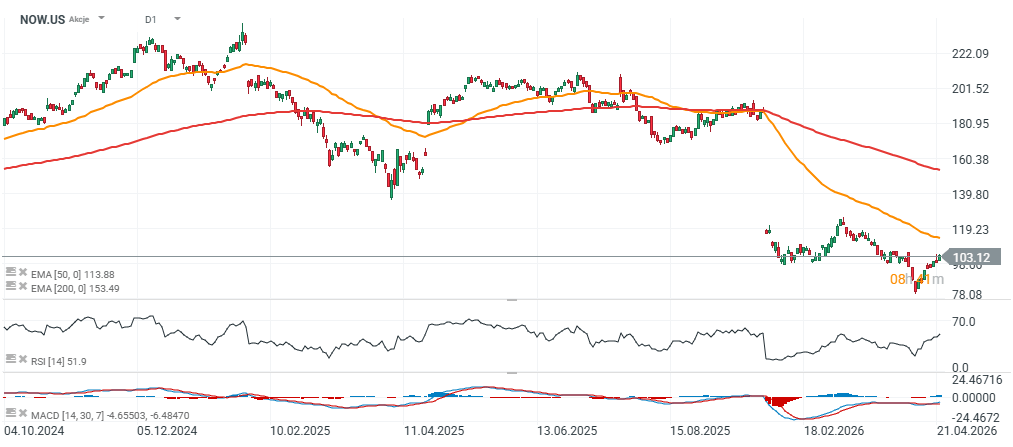
Source: xStation5