S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Today Markets Analysis: Global markets close the week with investors balancing hotter-than-expected US inflation, shifting Federal Reserve expectations, falling oil prices and escalating geopolitical risks. Wall Street stages a strong rebound despite the renewed prospect of tighter monetary policy, while precious metals recover and crude oil records a sharp correction after a powerful weekly rally.
As markets move into the weekend, attention now turns to Monday’s opening, with investors assessing whether Friday’s risk appetite can continue or whether the inflation and geopolitical risks that have dominated the week return to the forefront.
The Federal Reserve’s upcoming policy decision remains the central macroeconomic event, while developments across the Middle East, energy markets, European monetary policy and technology stocks are likely to shape sentiment at the start of the new week.
Macroeconomics: Inflation Raises Fed Pressure, but Consumers Remain Resilient
The latest US inflation data provides a hawkish signal heading into the Federal Reserve’s upcoming meeting.
August core inflation comes in above expectations, while the unofficial SuperCore inflation measure rises 0.5% month-on-month, taking its annual rate to approximately 3%. The figures reinforce concerns that underlying price pressures remain persistent.
Markets consequently move close to fully pricing a Federal Reserve rate increase at the upcoming meeting.
Yet Wall Street’s reaction is notably different from what might normally be expected from a hawkish inflation surprise. Rather than triggering a broad risk-off move, US equities rebound strongly, with investors instead focusing on falling oil prices, corporate earnings and continued strength in the technology sector.
That divergence is one of the most important signals heading into Monday.
If equities continue to absorb higher-rate expectations without a significant deterioration in risk appetite, it would suggest that investors are increasingly looking beyond the immediate monetary-policy threat.
European monetary policy also remains in focus. Expectations surrounding further ECB tightening continue to influence the euro-area outlook, while Poland’s market remains positioned for a relatively prolonged pause in domestic monetary policy.
Meanwhile, BRICS finance chiefs call for reforms to global development-finance institutions, seeking to reduce the dominance of traditional Western financial systems and diversify international sources of capital.
The resilience of the US private sector provides another important counterweight to monetary-policy concerns. American household net worth increases by approximately $12.803 trillion in the second quarter, highlighting the strength of household balance sheets despite elevated interest rates and persistent macroeconomic uncertainty.
What It Means for Monday
The key question for the new week is whether Friday’s equity resilience represents genuine confidence in the economic outlook or simply a temporary willingness to look through higher inflation.
The Fed remains the dominant catalyst, but investors also have to contend with the possibility that strong household balance sheets and resilient corporate earnings allow the US economy to withstand restrictive monetary policy for longer.
Wall Street: Four-Day Losing Streak Ends
US equities finish Friday’s session with a strong rebound, breaking a four-day losing streak.
Investors largely dismiss the hawkish implications of the latest inflation data, instead focusing on falling crude oil prices and encouraging technology earnings.
As of the Friday 19:44 snapshot:
| Market | Friday Session | Weekly Performance |
|---|---|---|
| S&P 500 | +1.00% | -0.49% |
| Dow Jones | +1.10% | -1.14% |
| DE40 | +0.93% | -1.93% |
| WIG20 | +0.68% | +1.38% |
| Tesla | +0.55% | +3.30% |
| Meta | +0.83% | +5.32% |
The weekly figures show that Friday’s rebound does not completely erase the pressure accumulated during the week, particularly across major European indices.
Technology Remains a Major Market Driver
Corporate earnings provide an important source of support.
Oracle attracts significant attention after reporting a 30% increase in total revenue, while cloud infrastructure revenue surges 121%, supported by strong demand associated with artificial intelligence projects.
Dell also performs strongly following a positive recommendation from RBC, which highlights approximately $16.4 billion in AI-server sales during the second quarter.
Adobe provides a contrasting example. Although its results remain solid, the company’s performance fails to satisfy elevated market expectations, highlighting how selectively investors are currently evaluating technology valuations.
Tesla also remains in focus after announcing the European market debut of its Semi electric truck, opening a potential new revenue stream in the strategically important European freight market.
Monday Watch
The major question for Monday is whether Friday’s rebound develops into a broader recovery or represents a temporary relief rally.
Technology earnings remain a powerful source of support, but elevated Treasury yields and the Federal Reserve’s policy outlook continue to provide an important counterweight.
Commodities: Oil Retreats While Precious Metals Recover
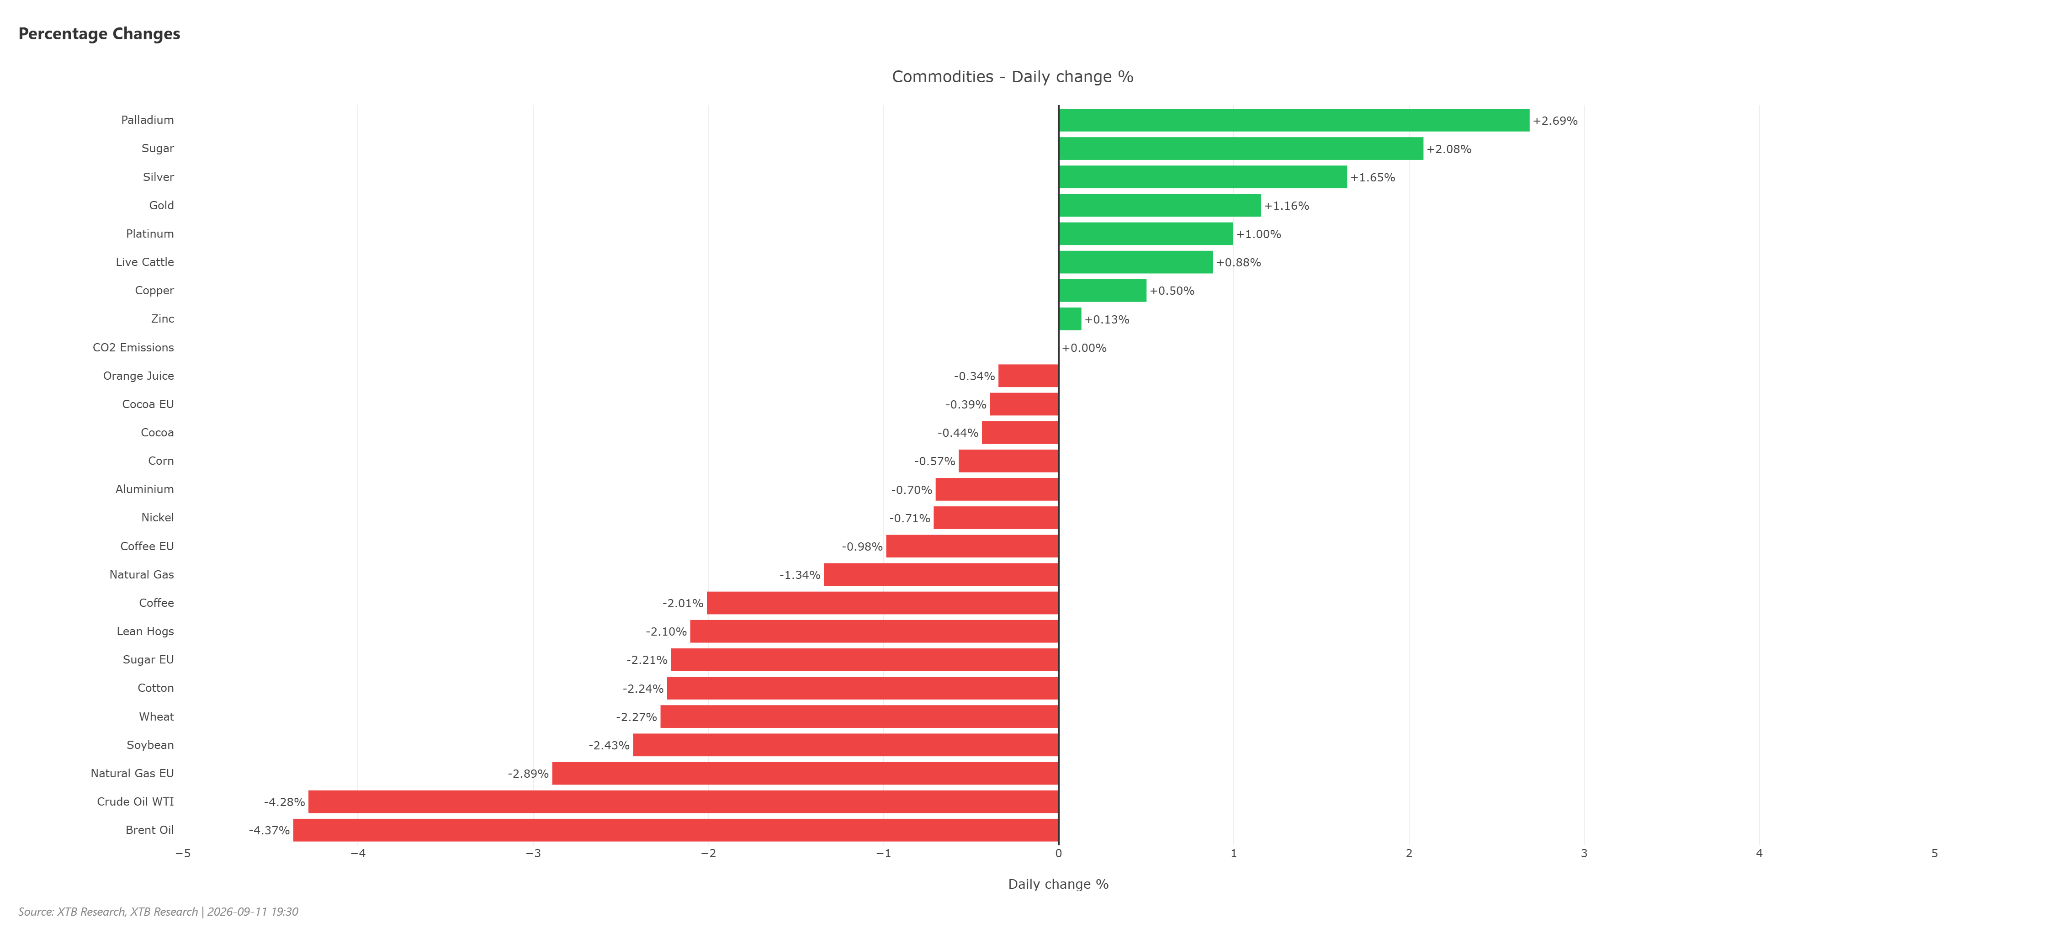
Crude oil experiences one of the week’s sharpest reversals on Friday.
WTI falls approximately 3.95%, while Brent declines 4.05% during the session, despite an intensification of geopolitical risks in the Persian Gulf.
The decline is largely attributed to significant profit-taking following the strong rally earlier in the week.
WTI nevertheless finishes the week approximately 9.44% higher, while Brent remains 9.07% higher on a weekly basis.
The contrast between Friday’s sharp correction and the broader weekly gain is important. Oil remains heavily influenced by geopolitical developments, but extremely strong recent gains create conditions for aggressive profit-taking.
The International Energy Agency’s reduction in its 2026 global supply forecast by approximately 1.4 million barrels per day would normally provide additional support for prices.
Instead, technical selling dominates Friday’s session.
Geopolitical risks remain elevated. Rebels damage a key Saudi East-West pipeline, while tanker freight rates on the route from the Middle East towards China surge to approximately $800,000 per day.
The disruption creates further pressure across global energy supply chains, with the US administration also considering use of the Defense Production Act to encourage additional domestic refining capacity.
Precious Metals Recover
Gold and silver respond positively after initially coming under pressure from the latest US inflation data.
Silver rebounds sharply from a three-week low and returns to approximately $64.45 per ounce, while gold regains the important 100-day simple moving average.
The recovery suggests that investors continue to view precious metals as a potential hedge against geopolitical and monetary uncertainty, even as higher US yields remain a structural headwind.
Friday’s commodity snapshot:
| Commodity | Friday Session | Weekly Performance |
|---|---|---|
| Gold | +1.04% | -1.54% |
| Silver | +1.44% | -2.60% |
| WTI Crude | -3.95% | +9.44% |
| Brent Crude | -4.05% | +9.07% |
| Copper | +0.50% | -0.92% |
| Corn | -0.71% | -2.01% |
Agriculture and Industrial Metals
Corn and other grains remain under pressure following the latest WASDE report.
Although the US Department of Agriculture lowers crop-yield forecasts, US ending stocks of approximately 1,567 million bushels exceed market expectations of 1,521.5 million bushels.
The larger-than-expected inventory figure creates immediate downward pressure on grain prices.
Copper remains close to historically elevated levels, with its five-year z-score around +2.65. The metal therefore remains an important indicator for global industrial demand and expectations surrounding the energy transition.
Markets are also beginning to assess the potential impact of El Niño on agricultural and industrial commodities, given its historical ability to create significant global price volatility.
Currencies: Dollar Strength Fails to Fully Overwhelm Sterling
The US inflation surprise provides renewed support for the dollar, but Friday’s currency moves remain relatively contained.
EUR/USD edges lower, while EUR/GBP moves towards 0.8580 as the euro struggles to generate upside momentum from European monetary policy expectations.
The British pound performs better.
Sterling resists the broader dollar-strengthening environment, supported by more constructive expectations surrounding UK economic growth.
Friday’s snapshot:
| Pair | Friday Session | Weekly Performance |
|---|---|---|
| EUR/USD | -0.01% | -0.05% |
| GBP/USD | +0.15% | +0.08% |
For Monday, currency markets are likely to remain highly sensitive to changes in US rate expectations, Treasury yields and the relative outlook for European and UK monetary policy.
Cryptocurrencies: Ethereum Leads as Bitcoin Remains Under Pressure
Crypto markets finish Friday on a firmer footing, led by Ethereum.
Bitcoin remains relatively stable but still records a weekly decline, while Ethereum recovers strongly and finishes the week higher.
| Asset | Friday Session | Weekly Performance |
|---|---|---|
| Bitcoin | +0.63% | -2.93% |
| Ethereum | +4.58% | +2.48% |
Zcash attracts particular attention after its five-year z-score reaches an extreme +5.12, indicating exceptionally stretched conditions.
That level points to significant medium-term overbought risk and leaves the token vulnerable to a sharp correction.
For Monday, the relative strength of Ethereum versus Bitcoin is worth monitoring for signs of continued capital rotation within the cryptocurrency market.
Geopolitics: Energy and Shipping Risks Remain Elevated
Geopolitical developments remain one of the biggest risks heading into Monday.
Iran-backed Houthi forces reportedly take control of the strategic island of Perim, providing a stronger position around the Bab al-Mandab Strait, one of the world’s most important maritime routes.
Any sustained deterioration in shipping conditions around the Red Sea and Persian Gulf could quickly feed into freight rates, energy prices and inflation expectations.
The US Treasury also signals that new sanctions against a major financial institution could be introduced as early as Monday as Washington increases financial pressure on Iran.
Meanwhile, Israeli forces announce the destruction of a major underground Hezbollah command centre, further highlighting the intensity of the regional conflict.
For financial markets, the important issue is increasingly the economic transmission mechanism: geopolitical escalation can affect oil, shipping costs, inflation expectations, central-bank policy and ultimately global risk appetite.
Monday Market Outlook
The weekend provides markets with a brief opportunity to digest a week in which several seemingly contradictory forces emerge.
US inflation is hotter than expected.
Federal Reserve rate-hike expectations rise sharply.
Treasury yields remain elevated.
Yet Wall Street rebounds strongly.
Oil prices fall sharply despite worsening geopolitical risks.
Gold and silver recover.
Technology stocks continue to attract capital.
This combination suggests that investors are not responding mechanically to macroeconomic headlines. Instead, capital is rotating between individual themes according to perceived earnings strength, geopolitical risk and the expected path of monetary policy.
For Monday, several areas deserve particular attention:
US Equities: Can Friday’s rebound extend into the new week despite higher rate expectations?
Oil: Does the sharp correction continue, or do geopolitical supply risks reassert themselves?
Silver: Can the recovery from the three-week low develop into a broader move higher?
Copper: Does the metal’s proximity to historic highs continue to signal underlying industrial optimism?
Currencies: Can sterling maintain its relative strength while the dollar remains supported by higher US rate expectations?
Ethereum: Does Friday’s strong outperformance represent the beginning of a broader rotation into higher-beta crypto assets?
Zcash: Does its extreme technical reading trigger profit-taking?
Today Markets View
The most important takeaway from the week is that markets are refusing to react to individual macroeconomic signals in isolation.
The hotter US inflation reading strengthens the case for tighter monetary policy, yet equities recover. Oil falls despite geopolitical escalation, while precious metals rebound despite elevated Treasury yields.
That tells us that positioning, expectations and cross-asset correlations are becoming just as important as the headline economic data.
“Friday’s market action is particularly interesting because investors absorb a hawkish inflation surprise without abandoning risk assets. Going into Monday, the question is whether this resilience represents genuine confidence in the economic outlook or simply a temporary willingness to look through higher rates. The answer is likely to emerge as markets increasingly focus on the Federal Reserve’s next move and the guidance surrounding it.”
— Louis Roche, Analyst at Today Markets
The new week therefore begins with a delicate balance between inflation, interest rates, corporate earnings, energy supply risks and geopolitics.
For investors and traders, the ability of markets to maintain Friday’s recovery while these risks remain elevated will provide an important early signal for the direction of the week.
Stay ahead of the developing global market picture with Today Markets, with additional currency and hedging intelligence available through Currency Hedger.
Analysis by Louis Roche, Analyst, Today Markets