S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market


- The US ADP Employment Change report is forecast to show a 69K increase in net jobs in October.
- Barring a strong disappointment, October’s ADP is unlikely to hurt confidence in the upbeat US economic momentum.
- The impact on the US Dollar is likely to be limited, with the outcome of the midterm elections front and center and ahead of the NFP report on Friday.
The Automatic Data Processing (ADP) Research Institute is due to release October’s private-sector employment report on Wednesday. The market consensus anticipates a moderate slowdown in job creation, with the ADP Employment Change expected to show 69K new private jobs in October, down from 90K in September.
ADP data is closely watched by financial markets, as it sets the stakes for the all-important Nonfarm Payrolls (NFP) report, normally released a couple of days later by the US Bureau of Labor Statistics (BLS). On Wednesday, however, the ADP report will have to share the spotlight with the US ISM Services Purchasing Managers Index (PMI) and, above all, market speculation about the consequences of the Democrats’ victory in the US midterm elections.
ADP Jobs Report set to show lower employment growth but a solid labour market
October’s ADP employment report comes after a string of strong US macroeconomic releases that have boosted investors’ confidence in the US economic outlook. Preliminary Gross Domestic Product (GDP) data released last week shows that the economy grew at a 3.4% annualised rate in the third quarter, with consumer spending, investment and government expenditure leading growth.
Beyond that, Monday’s US ISM Manufacturing PMI showed factory activity accelerated beyond expectations, suggesting that the economy entered the fourth quarter on a strong footing.
All this supports the theory of US economic exceptionalism, which, coupled with the strong inflation pressures, provides the ideal scenario for the Federal Reserve (Fed) to tighten its monetary policy further. According to the CME FedWatch tool, futures markets are pricing in a 75% chance of another quarter-point rate hike in December, a scenario that is keeping the US Dollar Index (DXY) relatively steady near year-to-date highs.
Against this background, October’s ADP employment report should show a strong setback to cause a major disruption. September’s Nonfarm Payrolls report showed a 29K increase in employment following 133K new jobs in August, which suggests that the labour market is stabilising, with no clear signs of a decline so far.
That said, the Greenback might remain on the defensive on Wednesday, amid the consequences of the sound Democratic win in the US midterm elections. Francesco Pesole, Analyst at ING assesses that “a Democratic sweep (…) could be seen as slightly negative for the US Dollar from a few angles, from higher risk of government shutdown and gridlock on debt ceiling negotiations to potential damage to already shaky AI-related sentiment.”
When will the ADP report be released, and how could it affect the US Dollar?
The US ADP Employment Change report will be out on Wednesday at 13:15 GMT, and it is expected to show that the private sector created 69K new jobs in October. The final data is unlikely to alter market expectations of a Fed rate hike in December, and therefore, its impact on the US Dollar (USD) is likely to be limited, with markets focused on the outcome of the midterm elections ahead of the all-important NFP report on Friday.
A few hours later on Wednesday, the US ISM Services PMI is expected to show a mild slowdown in October, yet at levels consistent with expansion and solid business activity in the sector. Again, it would require very disappointing figures to dent markets’ confidence in the strength of the US economy.
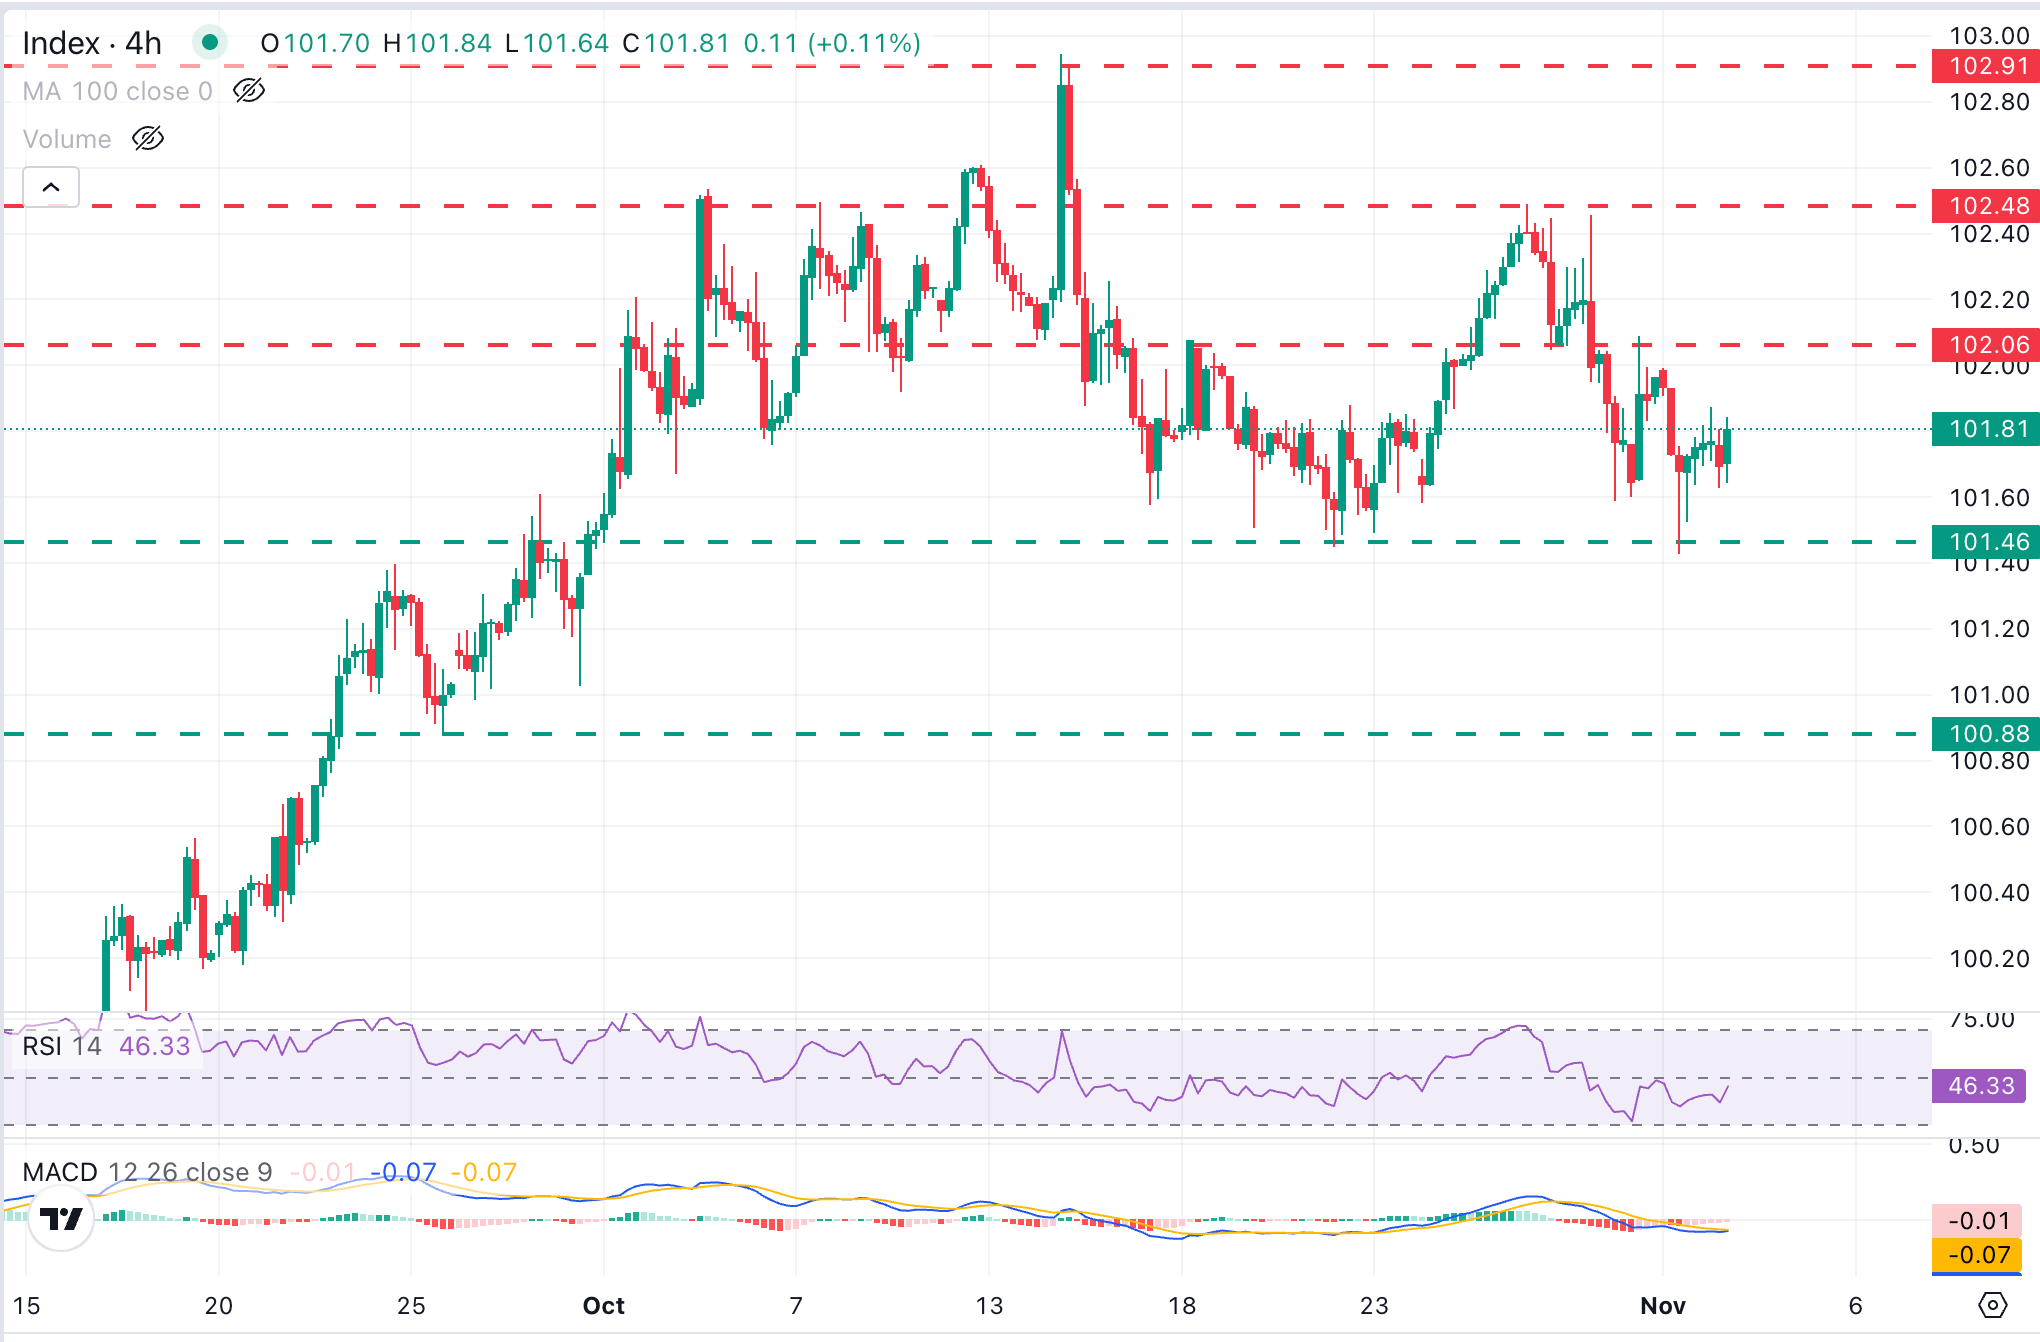
The US Dollar Index (DXY) technical picture shows the index hovering within the lower end of its trading range since early October, with the 4-hour chart showing a neutral-to-bearish near-term tone. The Relative Strength Index (14) sits below the mid-50 area, hinting at subdued directional conviction, while the Moving Average Convergence Divergence (MACD) histogram remains negative, all in all highlighting mild bearish pressure rather than a decisive negative trend.
According to Guillermo Alcalá, FX analyst at FXStreet, the DXY should break support at the 101.50 area (October 22 and November 2 lows) to confirm a trend shift and clear the path towards the late-September lows between 101.00 and 100.90.
On the upside, Alcalá sees the October 30 high, just above 102.00, and the October 28 and 29 highs around 102.50 as major resistances ahead of the 18-month high, at 102.95, hit in mid-October.