S&P 500 — US Large Cap Index
 FTSE 100 — UK Blue Chips
 Euro Stoxx 50 — Eurozone Leaders
 DAX 40 — German Equities
 CAC 40 — French Market Index
 Nikkei 225 — Japan Benchmark
 Hang Seng — Hong Kong Index
 Shanghai Composite — China Mainland
 ASX 200 — Australian Market
 TSX Composite — Canada Index
 Nifty 50 — India Large Cap
 STI Index — Singapore Market
 KOSPI — South Korea Index
 Bovespa — Brazil Equities
 JSE Top 40 — South Africa Index
 IPC Index — Mexico Market

Cocoa Prices Rebound as West African Dryness Threatens the 2026/27 Crop Outlook

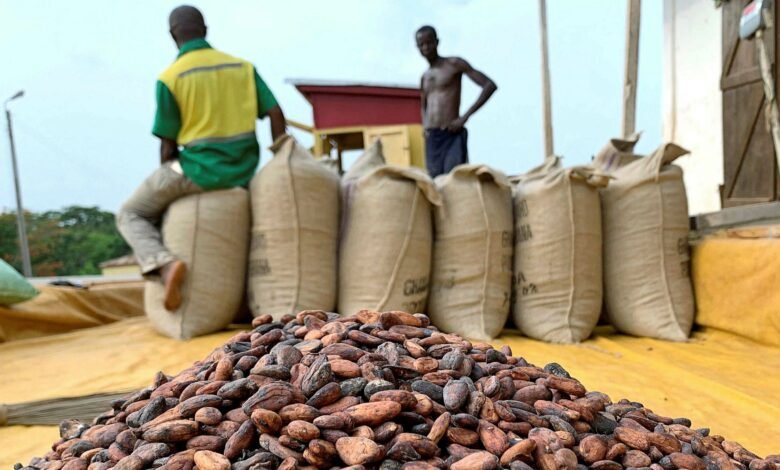
Cocoa prices are extending their rebound as dry conditions across West Africa raise fresh concerns about the development of the 2026/27 crop. December ICE New York cocoa is trading around $5,600 per metric ton, while December London cocoa is near £4,200, with both markets posting a third consecutive session of gains.
The immediate catalyst is weather. Forecasts for below-normal rainfall across the Ivory Coast over the coming week could increase moisture stress at a critical stage of the new crop cycle, while longer-term concerns surrounding pod development, disease and the potential impact of El Niño continue to create uncertainty around West African production.
At the same time, the market is balancing these crop risks against evidence that physical cocoa availability has improved substantially during the current season. Ivory Coast production and shipments have increased, while ICE inventories have climbed to their highest level in more than two years. This leaves cocoa caught between improving near-term supply and growing concerns about the next crop.
Market Snapshot
| Factor | Current Market Signal |
|---|---|
| December NY Cocoa | Around $5,600/MT, extending rebound |
| December London Cocoa | Around £4,200/MT, supported by weaker GBP |
| Ivory Coast 2025/26 Harvest | 2.06 MMT, up 30% y/y |
| Ivory Coast Shipments | 2.14 MMT through September 13, up 18% y/y on international-year comparison |
| ICE Cocoa Inventories | 3.44 million bags, highest in about 2.25 years |
| Ivory Coast 2026/27 Crop Assessment | Around 1.8 MMT, potentially 18% below 2025/26 |
| Ghana 2026/27 Crop Estimate | 650,000 MT, down 13% from 2025/26 |
| Global 2026/27 Balance | Surplus estimates have narrowed sharply |
| Key Weather Risk | Below-normal West African rainfall and potential El Niño impact |
Current Cocoa Price Action
Cocoa is recovering after falling to approximately 1.75-month lows earlier in the month. The rebound is now being driven primarily by renewed weather risk rather than a deterioration in current physical availability.
New York cocoa has also been supported by concerns surrounding the quality and development of the upcoming West African crop. London cocoa has received an additional boost from sterling weakness, which makes sterling-denominated cocoa more attractive in currency-adjusted terms.
The market therefore remains highly sensitive to changes in West African weather forecasts. A continuation of dry conditions could increase the premium attached to the 2026/27 crop, particularly if early signs of weaker pod development are confirmed.
Ivory Coast Production and Shipments
The Ivory Coast remains the dominant influence on the global cocoa supply outlook.
The country’s cocoa regulator reported that 2.06 million metric tons were harvested between June 2025 and June 2026, representing a 30% increase from the previous season’s 1.58 million tons.
Shipments have also remained strong. Cumulative exports to ports reached approximately 2.14 million tons through September 13, an increase of around 18% from the comparable period a year earlier under the international cocoa marketing calendar.
However, the comparison becomes more complicated because the Ivory Coast has shifted its own marketing year to begin on September 1. Deliveries during the first part of the new season were considerably lower than the comparable period under the previous calendar.
This creates an important distinction for traders: current-season availability remains relatively strong, but early flows for the new crop are providing a less comfortable signal.
2026/27 Ivory Coast Crop Faces Weather Risk
The biggest medium-term concern is the condition of the crop now entering the new season.
Early field assessments indicate poor cherelle formation and weaker-than-average pod development. Initial estimates put the 2026/27 Ivory Coast crop around 1.8 million tons, compared with approximately 2.2 million tons in 2025/26.
That would represent a decline of roughly 18%.
The forecast becomes more significant if below-normal rainfall develops across the main cocoa-growing regions. Cocoa trees require adequate moisture during pod development, meaning persistent dryness could further reduce yields and bean quality.
Ghana Production Outlook Weakens
Ghana provides another important source of supply risk.
The country’s cocoa regulator estimates 2026/27 production at approximately 650,000 MT, around 13% below the 750,000 MT expected for 2025/26.
A more bearish production scenario has also been discussed, with Ghana’s cocoa regulator previously indicating that output could fall toward 450,000–550,000 MT because of swollen shoot disease, aging farms and adverse weather associated with El Niño.
The current season, however, remains strong. Ghana has reported approximately 750,000 MT of harvested cocoa for 2025/26, up 25.6% from the previous season.
This again highlights the two-speed nature of the market: current supply is comparatively comfortable, while the next crop carries significantly greater uncertainty.
ICE Cocoa Inventories Signal Comfortable Near-Term Supply
One of the strongest bearish factors remains the level of exchange inventories.
ICE cocoa stocks have risen to approximately 3.44 million bags, the highest level in around 2.25 years.
Rising certified inventories suggest that physical availability has improved considerably from the extremely tight conditions that characterised the previous cocoa price spike.
Barry Callebaut has also indicated that the global cocoa market is currently well supplied and better positioned to absorb weather-related risks than it was during the 2023/24 El Niño episode.
This provides an important counterweight to the emerging crop concerns.
Global Cocoa Surplus Is Narrowing
The global balance is becoming less comfortable for 2026/27.
StoneX has reduced its projected global cocoa surplus to approximately 25,000 MT from 149,000 MT previously, citing increased production risks associated with expected El Niño conditions.
Another estimate puts the 2026/27 surplus at around 80,000 MT, down sharply from approximately 415,000 MT in 2025/26. That projection is based on global production falling toward 4.87 million tons from approximately 5.11 million tons.
The forecasts do not yet establish a global deficit, but the direction is important: expectations for a large surplus are being reduced as production risks increase.
El Niño Adds Medium-Term Weather Risk
The developing El Niño pattern remains one of the most important variables for cocoa traders.
El Niño conditions can produce warmer and drier weather across parts of West Africa, potentially reducing soil moisture and increasing stress on cocoa trees.
If the weather pattern becomes stronger or persists through key crop-development periods, the effect could be reflected in lower yields, poorer bean quality and tighter global availability later in the season.
The market is therefore likely to place increasing emphasis on rainfall forecasts and field reports as the 2026/27 crop develops.
Cocoa Demand Remains Mixed Across Major Grinding Regions
Demand signals remain uneven.
European cocoa grindings fell 4.6% year-on-year in Q2 to approximately 316,366 MT, representing the weakest second-quarter level in six years and reinforcing concerns about high cocoa prices weighing on processing demand.
North American grindings provided a contrasting signal, rising 7.7% year-on-year to approximately 109,659 MT.
Asian grinding activity was even stronger, increasing 25% year-on-year to approximately 224,646 MT.
The regional divergence means that the demand outlook cannot be characterised as uniformly weak. European processing remains a concern, while North American and Asian activity indicates that consumption and processing demand remain capable of absorbing significant cocoa volumes.
Bullish Sentiment
- Dry West African weather: Below-normal rainfall forecasts for the Ivory Coast could increase crop stress and reduce 2026/27 production potential.
- Weak early crop development: Poor cherelle formation and pod development are already raising concerns about the next Ivory Coast harvest.
- Ghana production risk: Estimates for Ghana’s 2026/27 crop point to another significant decline, with disease, aging farms and weather risks weighing on output.
- Narrowing global surplus: Major forecasts have reduced expected 2026/27 surpluses substantially, leaving less supply cushion against weather disruptions.
- El Niño threat: A stronger El Niño could create warmer and drier conditions across key West African growing areas.
- Asian and North American demand: Strong Q2 grinding figures from Asia and North America demonstrate that global processing demand remains resilient in important markets.
Bearish Sentiment
- Large current-season harvest: Ivory Coast production reached 2.06 MMT in 2025/26, substantially above the previous season.
- Strong export flows: Ivory Coast shipments remain elevated on the international marketing-year comparison, signalling substantial physical availability.
- High ICE inventories: Exchange stocks around 3.44 million bags provide a significant nearby supply buffer.
- European demand weakness: European grinding volumes have fallen sharply, indicating that high cocoa prices are already affecting processing demand.
- Global surplus remains possible: Even after downward revisions, several forecasts still point toward a small 2026/27 global surplus rather than an outright deficit.
- Recent price recovery could face resistance: Cocoa has already experienced a substantial rebound from its recent lows, leaving the market vulnerable to profit-taking if weather concerns fail to intensify.
Price Forecast: What Traders Are Watching
The next major directional signal is likely to come from the interaction between West African weather and physical cocoa availability.
A continuation of dry conditions across the Ivory Coast would strengthen the argument that 2026/27 production could fall materially below the previous season. Confirmation of poor pod development or deteriorating crop conditions could increase the weather premium embedded in cocoa futures.
Conversely, improved rainfall combined with continued strong deliveries and elevated ICE inventories would reinforce the view that near-term supply remains comfortable.
The key question is therefore whether the market begins pricing the potential 2026/27 supply reduction more aggressively than it discounts the substantial availability carried over from the current season.
Supply Outlook
Near-term cocoa supply remains relatively comfortable, supported by strong Ivory Coast and Ghana production during 2025/26 and elevated exchange inventories.
The outlook becomes more uncertain further into the 2026/27 season. Lower projected output from the Ivory Coast and Ghana, disease pressure, aging plantations and the possibility of El Niño-related weather stress all point toward a tighter production environment.
The coming weeks will be particularly important because rainfall and early pod-development conditions can influence expectations for the main crop well before final production numbers become available.
Demand Outlook
Demand is mixed rather than uniformly weak.
European grinding remains under pressure, while North American and Asian processing activity has been considerably stronger. The regional divergence suggests that high prices are affecting some consumers and processors without eliminating global demand.
If cocoa prices remain elevated, European demand could remain a limiting factor. However, continued strength in Asian processing and resilient North American grinding would provide support to the broader consumption outlook.
Market Outlook for the Coming Sessions
Cocoa is entering a period where weather may increasingly compete with inventory data as the dominant price driver.
Traders will monitor Ivory Coast rainfall forecasts, crop-development reports and early-season deliveries for evidence that the projected 2026/27 production decline is becoming more tangible.
At the same time, ICE inventories remain a substantial bearish buffer. If stocks continue rising while West African weather improves, the recent rebound could struggle to extend.
The market therefore remains balanced between comfortable current supply and increasingly uncertain future production. A sustained move higher would require stronger evidence that the emerging crop risks will translate into a materially tighter global balance.
Currency Hedger View
Cocoa’s international pricing structure creates additional currency considerations for producers, processors, exporters and importers.
Sterling movements are particularly relevant to London cocoa. A weaker pound can support sterling-denominated cocoa prices by altering the currency value of the underlying commodity. For companies purchasing cocoa internationally, however, simultaneous movements in cocoa prices and exchange rates can materially change landed costs.
The wider macro environment also remains important. Changes in the US dollar, global interest-rate expectations and risk sentiment can influence commodity investment flows and the relative attractiveness of dollar- and sterling-denominated contracts.
For businesses with cocoa-related FX exposure, managing the currency component separately from the underlying commodity exposure can help provide greater visibility over future costs and margins.
For tailored international FX, payment and currency-management solutions, visit Currency Hedger.
Analysis Louis Roche – Today Markets
Cocoa is increasingly being defined by a conflict between strong current physical availability and a less certain 2026/27 supply outlook.
The substantial Ivory Coast harvest, strong shipments and elevated ICE inventories provide evidence that the market is not currently experiencing the extreme physical tightness that drove previous cocoa price surges.
However, the forward picture is changing. Early crop assessments in the Ivory Coast and Ghana point toward lower production, while the potential for El Niño-related dryness introduces an additional layer of uncertainty. If rainfall deteriorates during critical crop-development periods, the market could begin to price a significantly smaller West African crop.
For now, traders are likely to remain highly responsive to weather forecasts, crop reports and inventory movements. The ability of cocoa to sustain its recovery will depend on whether emerging 2026/27 production risks become sufficiently large to offset the comfortable supply conditions visible in the current season.
Louis Roche – Today Markets